LIC New Jeevan Anand Plan 815 Calculator
Calculation Results
Premium Details
Maturity Benefits (On Survival)
Death Benefit (During Policy Term)
LIC New Jeevan Anand Plan 815 is a participating, non-linked life insurance plan that combines savings with lifelong insurance protection. It pays a lump-sum maturity benefit at the end of the selected policy term. After this payment, life cover equal to the Basic Sum Assured continues for the lifetime of the life assured.
Plan 815 is no longer available for new purchase. LIC withdrew it on 1 February 2020. Therefore, the LIC New Jeevan Anand Plan 815 Maturity Calculator is mainly useful for existing policyholders who want to estimate their maturity amount, understand the bonus component or check how their policy benefits work.
The calculator provides an estimate and not an official LIC quotation. For a reliable result, use the Basic Sum Assured, policy term, premium and vested bonus details shown in the policy bond or LIC records.
LIC New Jeevan Anand Plan 815 Overview
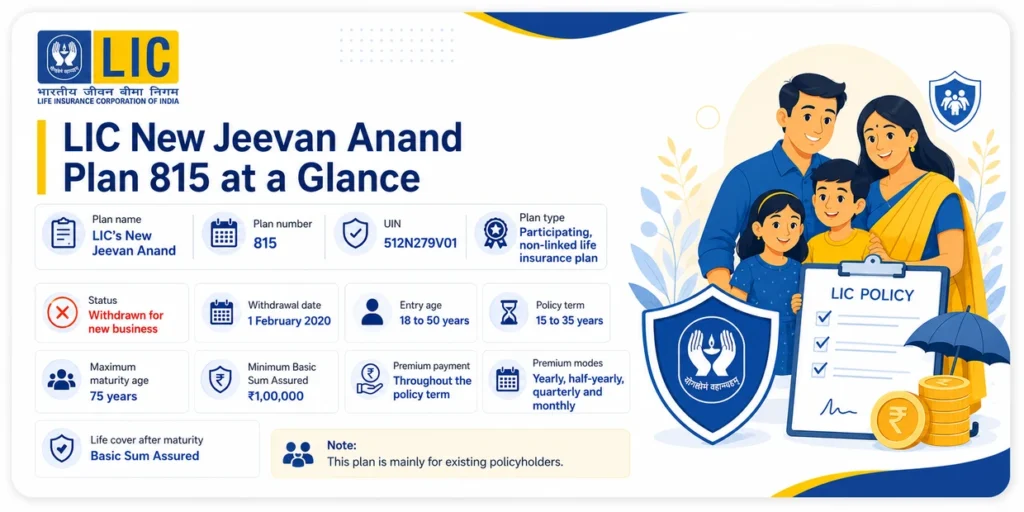
| Particular | Details |
|---|---|
| Plan name | LIC’s New Jeevan Anand |
| Plan number | 815 |
| UIN | 512N279V01 |
| Plan type | Participating, non-linked life insurance plan |
| Current status | Withdrawn for new business |
| Withdrawal date | 1 February 2020 |
| Entry age | 18 to 50 years |
| Policy term | 15 to 35 years |
| Maximum maturity age | 75 years |
| Minimum Basic Sum Assured | ₹1,00,000 |
| Premium payment | Throughout the policy term |
| Premium modes | Yearly, half-yearly, quarterly and monthly |
| Life cover after maturity | Basic Sum Assured |
The Basic Sum Assured had to be selected in multiples of ₹5,000. LIC did not state a maximum Basic Sum Assured in the sales brochure, but acceptance remained subject to its underwriting rules.
What Is LIC New Jeevan Anand Plan 815?
LIC New Jeevan Anand Plan 815 is a traditional endowment plan with a whole-life insurance feature. During the policy term, it provides death cover and may earn Simple Reversionary Bonus. If the life assured survives until maturity, LIC pays the Basic Sum Assured along with vested bonus and Final Additional Bonus, if declared.
The special feature begins after maturity. Even after the maturity amount is paid, insurance cover equal to the Basic Sum Assured continues. No further premium is payable after the selected policy term.
For example, suppose a policy has a Basic Sum Assured of ₹5 lakh and its maturity amount becomes ₹9 lakh after adding applicable bonuses. LIC may pay ₹9 lakh at maturity. The life cover continuing after maturity will still be ₹5 lakh, not ₹9 lakh. The maturity payment and post-maturity death benefit are separate benefits.
Plan 815 should not be confused with later versions of New Jeevan Anand. Plan numbers, UINs, bonus declarations and policy conditions can differ. This article applies only to Plan 815 with UIN 512N279V01.
What Is the LIC New Jeevan Anand Plan 815 Maturity Calculator?
The calculator estimates how much may be payable when a Plan 815 policy completes its term. It separates the Basic Sum Assured from the bonus-based amount, helping policyholders understand which part is fixed under the policy and which part depends on LIC’s declarations.
The main calculation requires the Basic Sum Assured, policy term, vested Simple Reversionary Bonus and applicable Final Additional Bonus. If the calculator also estimates premium, the exact premium rate or annual premium from the policy schedule should be entered.
The selected premium rates printed in LIC’s brochure are examples only. Missing rates for other ages or terms should not be created through interpolation because LIC’s complete premium table may not follow a uniform pattern.
Also Check:
- LIC New Jeevan Anand Plan 915 Maturity Calculator
- LIC New Jeevan Anand Plan 715 Maturity Calculator
- LIC Jeevan Anand Calculator All in One
Highlights of the Calculator
The calculator can show the estimated maturity amount, accumulated bonus, possible Final Additional Bonus and life cover continuing after maturity. It can also explain the difference between guaranteed and non-guaranteed components.
It is particularly useful for checking an old policy because Plan 815 is withdrawn. However, it cannot independently know the exact bonus attached to a policy, an underwriting extra, rider premium, surrender factor or LIC’s final servicing decision. These details must be taken from policy records.
How to Use the Calculator
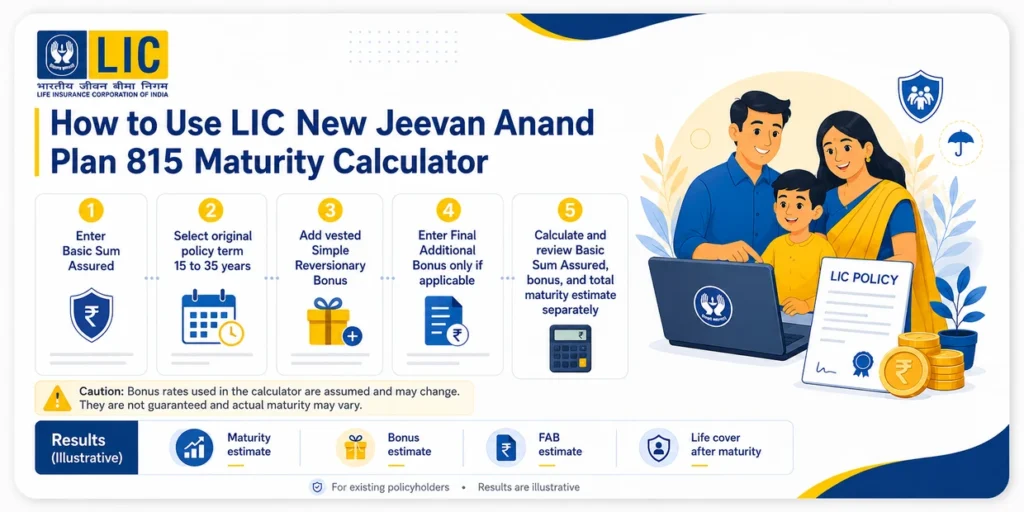
Enter the Basic Sum Assured mentioned in the policy bond. Select the original policy term, which can range from 15 to 35 years. Add the policy commencement year if the calculator provides a maturity-year field.
Next, enter the vested Simple Reversionary Bonus already attached to the policy. If the calculator asks for a bonus rate per ₹1,000, use a properly identified LIC declaration applicable to the policy. Do not enter an assumed high rate as if it were guaranteed.
Enter Final Additional Bonus only when an applicable amount is available. FAB is not automatically payable under every policy. After checking all inputs, calculate and review the Basic Sum Assured, bonus and total maturity estimate separately.
LIC New Jeevan Anand Plan 815 Maturity Formula
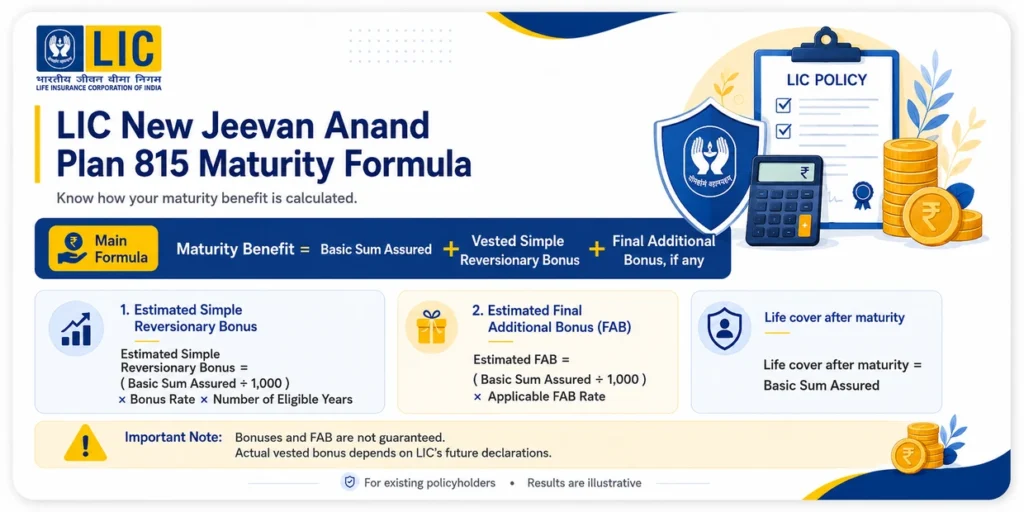
Maturity benefit is payable if the life assured survives until the end of the policy term and all due premiums have been paid.
Maturity Benefit =
Basic Sum Assured
+ Vested Simple Reversionary Bonus
+ Final Additional Bonus, if any
When bonus is entered as a rate per ₹1,000 Basic Sum Assured, an illustrative accumulated bonus can be calculated as:
Estimated Simple Reversionary Bonus =
(Basic Sum Assured ÷ 1,000)
× Bonus Rate
× Number of Eligible Years
This formula gives an illustration only. Actual vested bonus should be calculated using the bonus declared for each relevant financial year. Using one bonus rate for the entire policy term may not match the amount attached to the policy.
Final Additional Bonus may be estimated as:
Estimated FAB =
(Basic Sum Assured ÷ 1,000)
× Applicable FAB Rate
FAB depends on LIC’s declaration and conditions such as policy term, claim event and Sum Assured band. It must not be shown as a guaranteed addition.
Real Calculation Example
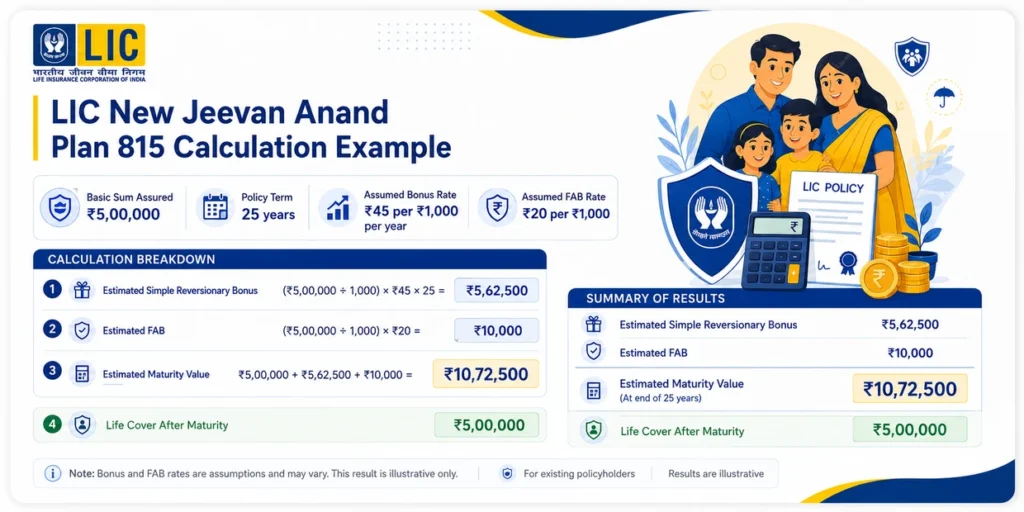
Assume the following policy details only for explanation:
| Input | Value |
| Basic Sum Assured | ₹5,00,000 |
| Policy term | 25 years |
| Assumed bonus rate | ₹45 per ₹1,000 per year |
| Assumed FAB rate | ₹20 per ₹1,000 |
First, calculate the estimated Simple Reversionary Bonus:
(₹5,00,000 ÷ 1,000) × ₹45 × 25
= 500 × ₹45 × 25
= ₹5,62,500
Next, calculate the illustrative FAB:
(₹5,00,000 ÷ 1,000) × ₹20
= 500 × ₹20
= ₹10,000
The estimated maturity value becomes:
₹5,00,000 + ₹5,62,500 + ₹10,000
= ₹10,72,500
In this example, ₹10,72,500 is only an illustrative maturity value. The bonus and FAB rates are assumptions and not promises. After maturity, life cover of ₹5,00,000 continues. The continuing cover is not added to the maturity payment.
Official LIC Benefit Illustration
LIC’s original sales brochure includes an illustration for a standard life aged 30 years, with a 35-year term, yearly premium mode and Basic Sum Assured of ₹1 lakh. It shows an annual premium of ₹3,165, excluding service tax, extra premium and rider premium.
The illustration uses assumed projected investment rates of 4% and 8% per annum to explain variable benefits. At maturity, it shows ₹1 lakh as the guaranteed Basic Sum Assured, with variable benefits of ₹14,000 and ₹1,56,000 under the two scenarios. The illustrated totals are ₹1,14,000 and ₹2,56,000.
These figures are not expected or guaranteed returns. They are statutory illustration scenarios used to explain how variable benefits may change. An individual policy’s maturity amount depends on the bonuses actually vested under that policy.
Premium Calculation
LIC’s brochure provides selected sample premium rates per ₹1,000 Basic Sum Assured. These are not a complete premium chart for every entry age and policy term.
Tabular Annual Premium =
(Basic Sum Assured ÷ 1,000) × Exact Premium Rate
High Sum Assured rebate is calculated as:
High Sum Assured Rebate =
(Basic Sum Assured ÷ 1,000) × Applicable Rebate Rate
Plan 815 offered no high Sum Assured rebate from ₹1 lakh to ₹1.95 lakh. The rebate was ₹1.50 per ₹1,000 for ₹2 lakh to ₹4.95 lakh, ₹2.50 per ₹1,000 for ₹5 lakh to ₹9.95 lakh and ₹3 per ₹1,000 for ₹10 lakh and above.
Yearly mode received a rebate of 2% of tabular premium, while half-yearly mode received 1%. No mode rebate applied to quarterly or monthly payment.
Annual Premium Before Tax =
Tabular Premium
− High Sum Assured Rebate
− Mode Rebate
Tax, rider premium and underwriting extra are added separately where applicable. For an existing policy, the tax rate should match the law applicable on the relevant premium payment date. Tax paid on premium is not included while calculating policy benefits.
Death Benefit During the Policy Term
If death occurs during the policy term while the policy is in force, the benefit includes Sum Assured on Death, vested Simple Reversionary Bonus and FAB, if any.
Sum Assured on Death = Higher of:
125% of Basic Sum Assured
or
10 × Annualised Premium
The total death benefit cannot be less than 105% of all premiums paid up to the date of death. Taxes, rider premiums and extra premiums are excluded for this condition.
After the policy term, the death benefit under a fully paid policy is the Basic Sum Assured. Bonuses paid at maturity are not paid again after death.
Surrender Value of Plan 815
The policy can be surrendered after at least three full years’ premiums have been paid. Its Guaranteed Surrender Value has a premium component and a separate value for vested bonus.
Premium-Based GSV =
Total Eligible Premiums Paid
× Applicable GSV Factor ÷ 100
Surrender Value of Vested Bonus =
Vested Simple Reversionary Bonus
× Applicable Bonus Surrender Factor ÷ 100The applicable factors depend on the policy term and completed policy year. Eligible premiums exclude tax, extra premium and rider premium. LIC may pay a Special Surrender Value when it is more favourable. The original brochure also states that residual life cover after maturity may be eligible for Special Surrender Value.
A calculator should use the exact factors from the Plan 815 brochure. It should not apply a fixed percentage to every policy year.
Paid-Up Value When Premiums Stop
If at least three full years’ premiums have been paid and later premiums are not paid, the policy may continue with reduced paid-up benefits.
Paid-Up Sum Assured =
Basic Sum Assured
× Number of Premiums Paid
÷ Total Number of Premiums Payable
For example, if 10 out of 25 yearly premiums have been paid on a ₹5 lakh policy:
₹5,00,000 × 10 ÷ 25 = ₹2,00,000The reduced Paid-Up Sum Assured and vested bonus already attached may be payable on maturity or earlier death according to the policy conditions. No future bonus accrues after the policy becomes paid-up. If death occurs after the original policy term, the reduced Paid-Up Sum Assured is payable, not the original Basic Sum Assured. Rider benefits also stop when the policy is in lapsed or paid-up condition.
Loan, Grace Period and Revival
A policy loan may be available after the policy acquires surrender value. The permitted amount and interest rate depend on LIC’s servicing rules at that time, so a calculator should not present a fixed loan percentage without verified policy data.
The grace period is one calendar month, but not less than 30 days, for yearly, half-yearly and quarterly premiums. It is 15 days for monthly premiums.
Under the original Plan 815 brochure, a lapsed policy could be revived within two consecutive years from the date of the first unpaid premium and before the end of the policy term. Revival was subject to payment of arrears with interest, proof of continued insurability and LIC’s approval.
Frequently Asked Questions
Is LIC New Jeevan Anand Plan 815 still available?
No. LIC withdrew Plan 815 from new sales on 1 February 2020. Existing policies continue according to their policy conditions.
How is Plan 815 maturity value calculated?
The maturity benefit is Basic Sum Assured plus vested Simple Reversionary Bonus and Final Additional Bonus, if any.
Is the maturity amount guaranteed?
The Basic Sum Assured is the fixed base component. Simple Reversionary Bonus and FAB depend on LIC’s declarations and are not guaranteed in advance.
What happens to life cover after maturity?
For a fully paid policy, life cover equal to the Basic Sum Assured continues after maturity. No further premium is payable.
When can Plan 815 be surrendered?
The policy can acquire surrender value after at least three full years’ premiums have been paid. The final amount depends on applicable factors and LIC’s calculation.
What happens if premium payment stops?
After at least three full years’ premiums, the policy may continue with reduced paid-up benefits. It will not continue with the original full benefit.
Can a loan be taken under Plan 815?
A loan may be available after the policy acquires surrender value, subject to LIC’s applicable conditions and interest rate.
Conclusion
The LIC New Jeevan Anand Plan 815 Maturity Calculator helps existing policyholders estimate maturity value by separating the Basic Sum Assured, vested bonus and possible FAB. It also explains the important lifelong-cover feature that continues after maturity.
For the most reliable calculation, use the exact details from the policy bond, premium receipts and LIC bonus records. Do not estimate missing premium rates from a few brochure examples or treat an assumed bonus as guaranteed. LIC’s final servicing or claim calculation will remain authoritative.