LIC Jeevan Utsav Plan 871 Calculator
Non-Linked, Non-Participating, Individual, Savings, Whole Life Insurance Plan
UIN: 512N363V01📊 Calculation Results
💰 Premium Breakdown
—
| Payment Mode | Installment Premium |
|---|
🎁 Guaranteed Benefits
📈 Flexi Income Projection
🗓 Benefit Timeline
Important update: LIC Jeevan Utsav Plan 871, UIN 512N363V01, was withdrawn from sale on 1 October 2024. This calculator and guide are mainly useful for existing policyholders who want to understand their premium, income benefit, Guaranteed Additions, death benefit, surrender value and policy rules. The launch and withdrawal dates are available on the official LIC Plan 871 page.
What Is LIC Jeevan Utsav Plan 871?
LIC Jeevan Utsav Plan 871 was a non-linked, non-participating, individual savings and whole life insurance plan. It was designed to provide life cover along with yearly income after a selected waiting period.
The plan did not depend on stock market performance. Its benefits were fixed according to policy terms. It offered two survival benefit choices: Regular Income Benefit and Flexi Income Benefit. It also provided Guaranteed Additions during the premium payment period.
The main point to understand is that this is not a traditional endowment policy. It does not pay a fixed maturity amount at the end of a policy term. Instead, it provides income during the lifetime of the Life Assured, subject to the policy remaining active.
What Is LIC Jeevan Utsav Plan 871 Calculator?
The LIC Jeevan Utsav Plan 871 Calculator helps estimate the important values attached to an existing policy. It can show:
- Indicative annual premium
- Half-yearly, quarterly and monthly premium estimate
- Total premium payable during the Premium Paying Term
- Annual Guaranteed Addition
- Total Guaranteed Additions during the premium payment period
- Annual Regular Income or Flexi Income
- First income benefit year
- Sum Assured on Death
- Illustrative death benefit
- Flexi Income accumulation value when income is deferred
The premium result should be treated as an estimate unless the original LIC premium from the policy schedule or benefit illustration is entered. LIC premium can vary depending on age, Premium Paying Term, Basic Sum Assured, rebate, mode, underwriting decision, riders and applicable taxes.
If an official policy premium is not entered, the calculator may estimate it from limited sample data. Any interpolation or proportional scaling used for a different age or Basic Sum Assured is only an approximation and is not an LIC quotation.
Also Check:
- LIC Jeevan Utsav Plan 771 Calculator
- LIC Jeevan Utsav Calculator All in One
- LIC Jeevan Utsav Plan 833 Calculator
How to Use LIC Jeevan Utsav Plan 871 Calculator
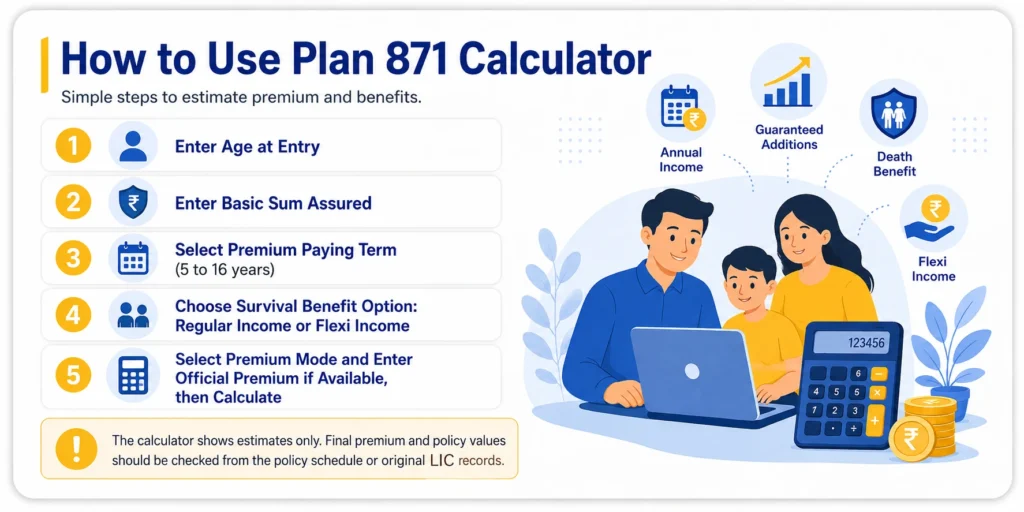
Using the calculator is simple.
Step 1: Enter Age at Entry
Enter the age when the policy was purchased. Plan 871 uses age conditions based on the selected Premium Paying Term.
Step 2: Enter Basic Sum Assured
Enter the original Basic Sum Assured mentioned in the policy bond.
The minimum Basic Sum Assured was ₹5 lakh. Amounts from ₹5,00,000 to ₹24,00,000 had to be in multiples of ₹25,000. Amounts of ₹25,00,000 and above had to be in multiples of ₹1,00,000. There was no fixed maximum, but the amount accepted was subject to LIC’s underwriting decision.
Step 3: Select Premium Paying Term
Choose the original Premium Paying Term between 5 years and 16 years.
The calculator uses this input to calculate:
- Income start year
- Total Guaranteed Additions
- Premium payment duration
- Policy eligibility checks
Step 4: Select Survival Benefit Option
Choose the option written in the policy schedule.
Option I – Regular Income Benefit:
The policyholder receives yearly income directly.
Option II – Flexi Income Benefit:
Each due yearly benefit is retained and accumulated at 5.5% per year, compounded yearly for completed months. A withdrawal can be requested according to the policy rules.
Step 5: Select Premium Payment Mode
Select yearly, half-yearly, quarterly or monthly premium mode.
The original brochure listed modal loadings of 1.75% for half-yearly mode, 2.50% for quarterly mode and 3.25% for monthly mode. Yearly mode had no modal loading. The instalment premium is the amount payable in the selected mode and may include modal loading.
Step 6: Enter Official Premium if Available
For the closest result, enter the premium shown in the original LIC benefit illustration or policy schedule. Annualised Premium means the premium payable in one policy year, excluding taxes, rider premium, underwriting extra premium and modal loading. It is different from an instalment premium payable in a non-yearly mode.
Without the official premium, the calculator may show an indicative estimate based on available sample premium data. The final premium for an individual policy must always be taken from LIC’s policy schedule.
Step 7: Click Calculate Premium & Benefits
The calculator will show the yearly income amount, Guaranteed Additions, income start year and death benefit estimate.
Use the Reset button to clear the entered values and start again.
Does LIC Jeevan Utsav Plan 871 Have a Maturity Amount?
No. LIC Jeevan Utsav Plan 871 does not have a maturity benefit.
This is important because many people search for “LIC Jeevan Utsav Plan 871 premium and maturity calculator.” The phrase is common, but the plan itself does not pay a maturity lump sum at a fixed age or policy term end.
Instead, the plan offered yearly survival income after the applicable start year and continued life cover until death, surrender, foreclosure or another termination condition under the policy.
LIC Jeevan Utsav Plan 871 Overview
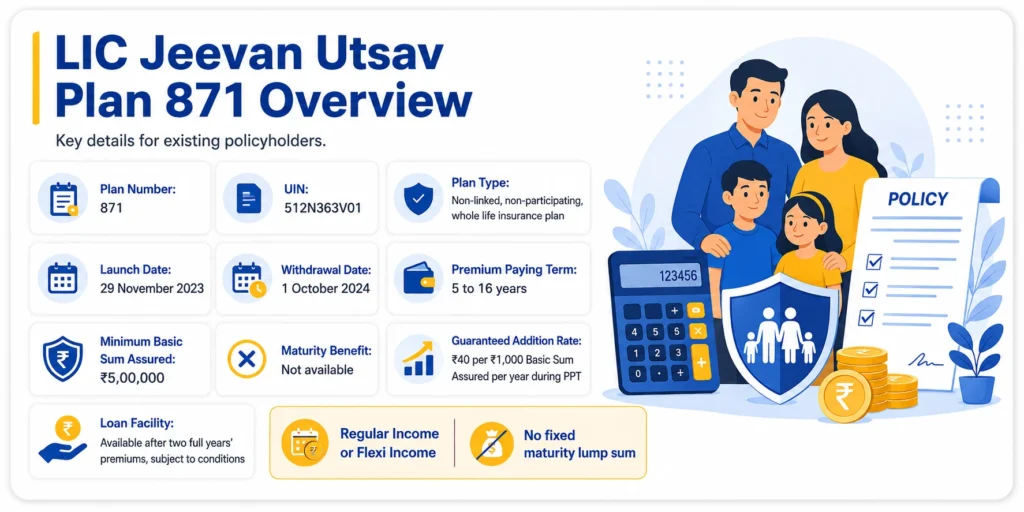
| Feature | Details |
|---|---|
| Plan Name | LIC Jeevan Utsav |
| Plan Number | 871 |
| UIN | 512N363V01 |
| Plan Type | Non-linked, non-participating, whole life insurance plan |
| Launch Date | 29 November 2023 |
| Withdrawal Date | 1 October 2024 |
| Premium Paying Term | 5 to 16 years |
| Policy Term | Whole life, subject to policy termination conditions |
| Minimum Basic Sum Assured | ₹5,00,000 |
| Maturity Benefit | Not available |
| Survival Benefit Options | Regular Income or Flexi Income |
| Guaranteed Addition Rate | ₹40 per ₹1,000 Basic Sum Assured per year during PPT |
| Loan Facility | Available after two full years’ premiums, subject to conditions |
LIC Jeevan Utsav Plan 871 Eligibility Criteria
| Premium Paying Term | Minimum Entry Age | Maximum Entry Age |
| 5 years | 8 years | 65 years |
| 6 years | 8 years | 65 years |
| 7 years | 8 years | 65 years |
| 8 years | 8 years | 65 years |
| 9 years | 7 years | 65 years |
| 10 years | 6 years | 65 years |
| 11 years | 5 years | 64 years |
| 12 years | 4 years | 63 years |
| 13 years | 3 years | 62 years |
| 14 years | 2 years | 61 years |
| 15 years | 1 year | 60 years |
| 16 years | 90 days | 59 years |
The maximum premium ceasing age was 75 years nearer birthday. The Life Assured also had to be at least 18 years old at the beginning of the policy year in which the first Regular Income or Flexi Income became due.
Guaranteed Additions in LIC Jeevan Utsav Plan 871
Guaranteed Additions were one of the strongest features of Plan 871.
LIC credited Guaranteed Additions at the rate of ₹40 per ₹1,000 of Basic Sum Assured at the end of every policy year during the Premium Paying Term. No further Guaranteed Additions accrued after the premium payment period ended.
The formula is:
Annual Guaranteed Addition
= Basic Sum Assured ÷ 1,000 × ₹40
For example, if the Basic Sum Assured is ₹10 lakh:
₹10,00,000 ÷ 1,000 × ₹40
= ₹40,000 per year
For a 10-year Premium Paying Term:
₹40,000 × 10 years
= ₹4,00,000 total Guaranteed Additions
If death occurs during the Premium Paying Term while the policy is in force, the Guaranteed Addition for the policy year of death is payable for the complete policy year. When a policy becomes paid-up, Guaranteed Additions already accrued remain attached, but no future additions accrue. If only part of the final policy year’s premium was received before paid-up status, that year’s addition is calculated proportionately according to the policy conditions. On surrender during the Premium Paying Term, the addition for that policy year is calculated proportionately for completed months.
Regular Income Benefit vs Flexi Income Benefit
| Point | Regular Income Benefit | Flexi Income Benefit |
| Annual benefit | 10% of Basic Sum Assured | 10% of Basic Sum Assured |
| Payment style | Paid yearly | Can be deferred |
| Interest on deferred value | Not applicable | 5.5% p.a. compounded yearly |
| Withdrawal | Regular yearly payment | Maximum 75% of accumulated balance once in a policy year |
| Best suited for | Regular yearly income | Delayed withdrawal and accumulation |
Under both options, the annual survival benefit equals 10% of the Basic Sum Assured. Under the Flexi option, each due benefit accumulates at 5.5% per year, compounded yearly for completed months. A written request can be made to withdraw up to 75% of the eligible accumulated balance once in a policy year. The remaining amount continues to accumulate.
When Does LIC Jeevan Utsav Income Start?
The income does not begin immediately after the last premium. It starts according to the selected Premium Paying Term.
| Premium Paying Term | First Income Benefit Due at End of |
| 5 years | 11th policy year |
| 6 years | 11th policy year |
| 7 years | 11th policy year |
| 8 years | 11th policy year |
| 9 years | 12th policy year |
| 10 years | 13th policy year |
| 11 years | 14th policy year |
| 12 years | 15th policy year |
| 13 years | 16th policy year |
| 14 years | 17th policy year |
| 15 years | 18th policy year |
| 16 years | 19th policy year |
The selected income option could be changed up to six months before the beginning of the policy year in which the first income benefit became due.
Real Calculation Example of LIC Jeevan Utsav Plan 871
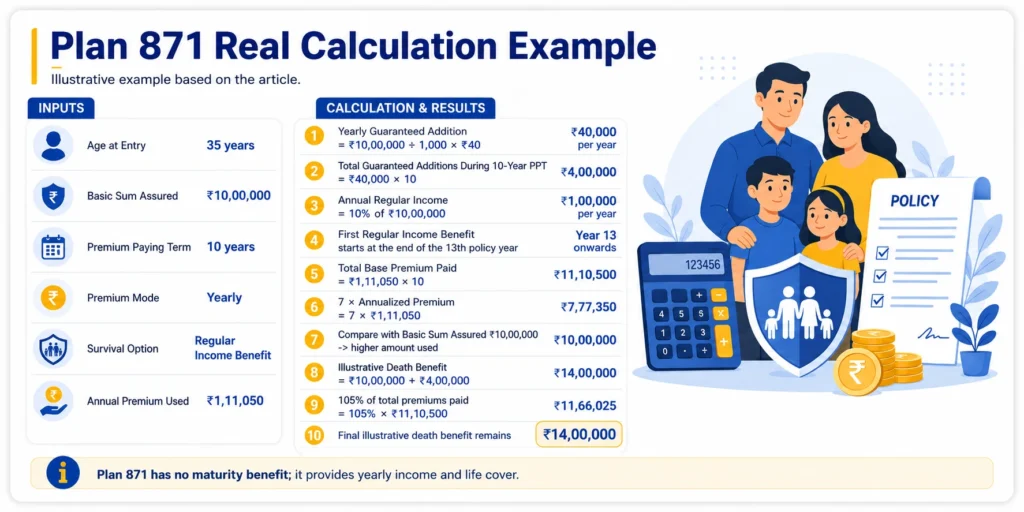
Here is a practical example based on the original LIC benefit illustration structure.
| Input | Value |
| Age at Entry | 35 years |
| Basic Sum Assured | ₹10,00,000 |
| Premium Paying Term | 10 years |
| Premium Mode | Yearly |
| Survival Option | Regular Income Benefit |
| Annual Premium Used | ₹1,11,050 |
| Premium Payment Duration | 10 years |
The historical LIC brochure used this type of illustration for a standard life with ₹10 lakh Basic Sum Assured and a 10-year Premium Paying Term. This example assumes death occurs after completion of the 10-year Premium Paying Term, all ten yearly premiums have been paid, no income benefit has yet been paid and the policy is in force.
Yearly Guaranteed Addition
₹10,00,000 ÷ 1,000 × ₹40
= ₹40,000 per year
Total Guaranteed Additions During 10-Year PPT
₹40,000 × 10
= ₹4,00,000
Annual Regular Income
10% of ₹10,00,000
= ₹1,00,000 per year
Since the Premium Paying Term is 10 years, the first Regular Income Benefit starts at the end of the 13th policy year.
Total Base Premium Paid
₹1,11,050 × 10
= ₹11,10,500
Taxes, rider premiums and underwriting extra premiums are not included in the policy definition of Annualised Premium or Total Premiums Paid. Total Premiums Paid for the 105% test means eligible premiums actually received up to the date of death, subject to the exclusions in the policy definition.
Sum Assured on Death
7 × Annualized Premium
= ₹1,11,050 × 7
= ₹7,77,350
Compare this with Basic Sum Assured:
Basic Sum Assured = ₹10,00,000
7 × Annualized Premium = ₹7,77,350
The higher amount is ₹10,00,000.
Death Benefit After Premium Payment Term
Sum Assured on Death = ₹10,00,000
Accrued Guaranteed Additions = ₹4,00,000

Death Benefit = ₹14,00,000
The policy also checks whether this amount is at least 105% of total premiums paid. In this example:
105% of ₹11,10,500
= ₹11,66,025
Since ₹14,00,000 is higher, the illustrative death benefit remains ₹14,00,000, subject to the policy being in force and any outstanding loan or dues.
Paid-Up Policy Rules
If at least two full years’ premiums were paid and later premiums were stopped, the policy could continue as a paid-up policy.
The Paid-up Sum Assured is calculated as:
Paid-up Sum Assured
= Basic Sum Assured ×
(Number of Premiums Paid ÷ Total Number of Premiums Originally Payable)
For example, if a ₹10 lakh policy with a 10-year Premium Paying Term became paid-up after five full premiums:
₹10,00,000 × 5 ÷ 10
= ₹5,00,000 Paid-up Sum Assured
The death cover is reduced separately:
Death Paid-up Sum Assured
= Original Sum Assured on Death ×
(Number of Premiums Paid ÷ Total Number of Premiums Originally Payable)
Accrued Guaranteed Additions remain attached according to the policy conditions.
| Paid-up Sum Assured | Annual Paid-up Income |
| Below ₹2,00,000 | No income benefit |
| ₹2,00,000 to below ₹3,00,000 | 5% of Paid-up Sum Assured |
| ₹3,00,000 to below ₹4,00,000 | 6% of Paid-up Sum Assured |
| ₹4,00,000 to below ₹5,00,000 | 7% of Paid-up Sum Assured |
| ₹5,00,000 and above | 10% of Paid-up Sum Assured |
These slabs apply to the reduced Regular Income or Flexi Income benefit under an eligible paid-up policy.
LIC Jeevan Utsav Plan 871 Surrender Value
Surrender was available after payment of at least two full years’ premiums.
LIC pays the higher of:
- Guaranteed Surrender Value
- Special Surrender Value
For Regular Income option, Guaranteed Surrender Value is based on paid premiums, accrued Guaranteed Additions, applicable GSV factors and income already paid.
For the Flexi Income option, the unwithdrawn accumulated Flexi Income with applicable interest is also payable on surrender as a separate component. It should not be confused with the base surrender value. Unless the calculator contains the official policy-year GSV factors and all inputs required for Special Surrender Value, its surrender result is only indicative.
Loan Facility Under Plan 871
A policy loan was available after at least two full years’ premiums had been paid.
Before the income benefit starting year, the maximum loan was up to 75% of surrender value for an in-force policy and up to 50% for a paid-up policy.
After the income start year, the loan amount was restricted so that effective annual loan interest did not exceed 50% of the yearly Regular Income or Flexi Income benefit, subject to the surrender-value limits. Flexi Income policies could also allow a loan of up to 50% of due but unwithdrawn Flexi Income.
An exact loan amount cannot be calculated from Basic Sum Assured and premiums alone. It requires the applicable surrender value, policy status, income already paid, Flexi Income balance and LIC’s loan-interest conditions. A loan estimate based on a manually entered surrender value is therefore indicative.
Grace Period, Lapse and Revival
The policy had a 30-day grace period for yearly, half-yearly and quarterly premiums. Monthly premiums had a 15-day grace period.
If the premium remained unpaid after the grace period, the policy lapsed. A lapsed policy could be revived within five consecutive years from the first unpaid premium date, subject to LIC’s revival terms, arrears, interest and underwriting requirements.
Riders Available Under LIC Jeevan Utsav Plan 871
Existing policies could include riders if they were selected and approved.
- LIC Accidental Death and Disability Benefit Rider
- LIC Accident Benefit Rider
- LIC New Term Assurance Rider
- LIC New Critical Illness Benefit Rider
- LIC Premium Waiver Benefit Rider
The Accidental Death and Disability Rider and Accident Benefit Rider could not be selected together. Rider terms, eligibility and premiums depend on the rider chosen in the original policy.
The available combination depended on age, selection timing, premium limits and individual rider conditions. The issued policy schedule should be checked to confirm which rider was actually selected.
Tax Rule
Tax deduction on premiums and the taxability of policy receipts depend on the Income Tax Act provisions applicable to the policy and the policyholder’s circumstances. Annual income should not automatically be treated as tax-free. The issue date, premium-to-Sum-Assured ratio and nature of the receipt can affect the result. Current rules should be checked with a qualified tax professional.
Frequently Asked Questions
Is LIC Jeevan Utsav Plan 871 still available?
No. Plan 871 was withdrawn from sale on 1 October 2024. This calculator is useful for existing policyholders and historical benefit understanding.
Does LIC Jeevan Utsav Plan 871 provide maturity amount?
No. There is no maturity benefit under Plan 871. It provides yearly income after the applicable start year and life cover subject to policy conditions.
How much yearly income is payable?
Regular Income Benefit and Flexi Income Benefit are both equal to 10% of the Basic Sum Assured for an in-force policy.
How are Guaranteed Additions calculated?
Guaranteed Addition is calculated at ₹40 per ₹1,000 of Basic Sum Assured for every policy year during the Premium Paying Term.
Can Flexi Income be withdrawn?
Yes. Under the Flexi option, up to 75% of accumulated Flexi Income including interest can be withdrawn once in a policy year, subject to written request and policy terms.
Final Words
LIC Jeevan Utsav Plan 871 was structured for limited premium payment, yearly lifetime income and whole-life protection. Its main value was not a maturity corpus, but the combination of Guaranteed Additions, annual income and death benefit.
The calculator makes it easier to understand policy values, but the original LIC policy schedule and benefit illustration remain the final record for premium, rider details, tax, surrender value and claim eligibility.