LIC Jeevan Tarun Plan 834 Calculator
LIC Jeevan Tarun
A participating, non-linked, limited premium payment child savings plan. It provides survival benefits from age 20 to 24 years and a maturity benefit at age 25 years.
Enter Policy Details
Calculation Results
All values are indicative and rounded to the nearest rupee.
- Child's Age at Entry
- —
- Sum Assured
- —
- Selected Option
- —
- Policy Term
- —
- Premium Paying Term
- —
- Payment Mode
- —
| Child's Age | Benefit Type | Guaranteed | Illustrative Total |
|---|
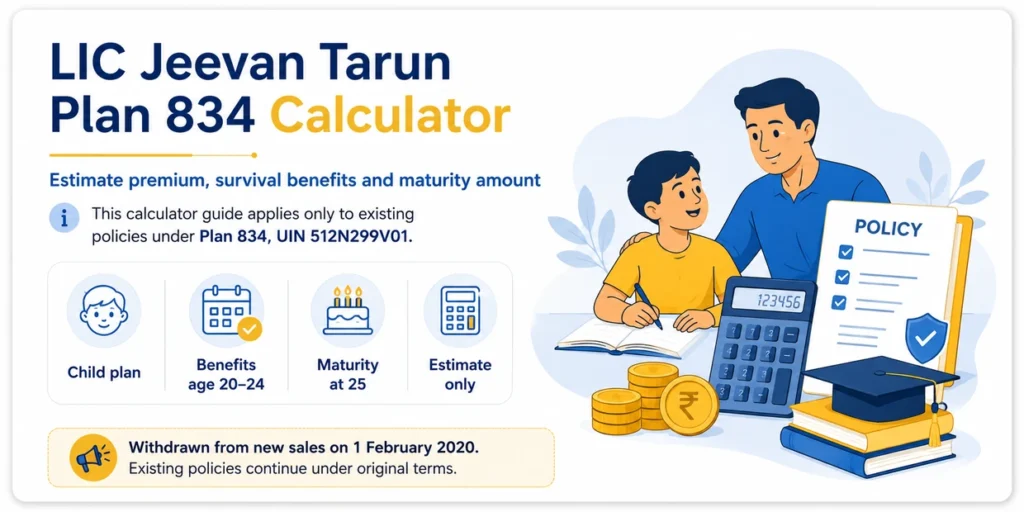
LIC Jeevan Tarun Plan 834 is a child insurance and savings plan that provides benefits during the child’s early adult years. Depending on the option selected when the policy was purchased, it may pay yearly survival benefits from age 20 to 24 and a final maturity benefit at age 25.
The LIC Jeevan Tarun Plan 834 Calculator helps existing policyholders estimate the premium, policy term, survival benefits and guaranteed maturity amount. It can also help in understanding paid-up and surrender value calculations.
In this guide we will read complete details about LIC Jeevan Tarun Plan 834 with UIN 512N299V01. LIC withdrew this version from new sales on 1 February 2020. Existing policies continue according to their original terms. It should not be confused with Plan 934 or the current Plan 734.
LIC Jeevan Tarun Plan 834 at a Glance
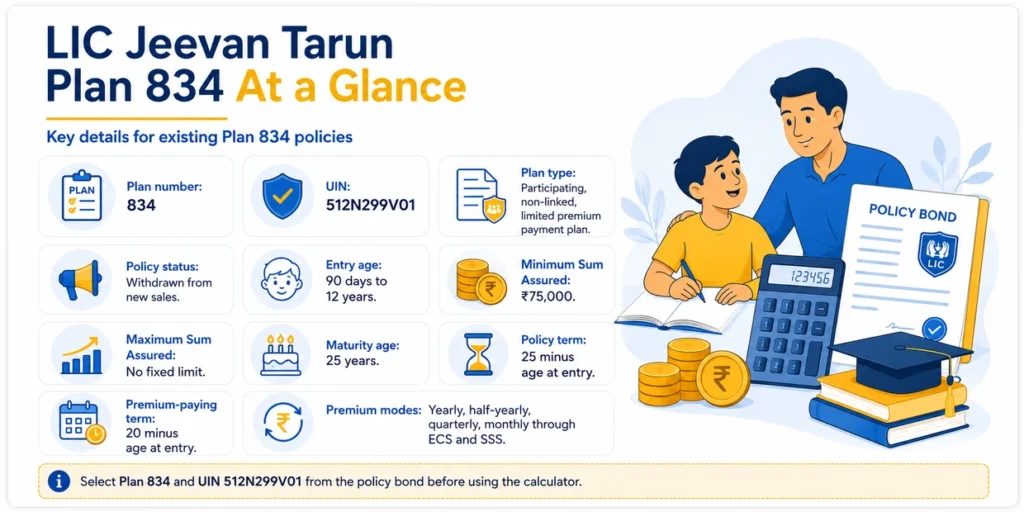
| Policy feature | Plan detail |
|---|---|
| Plan name | LIC Jeevan Tarun |
| Plan number | 834 |
| UIN | 512N299V01 |
| Plan type | Participating, non-linked, limited premium payment plan |
| Policy status | Withdrawn from new sales |
| Entry age | 90 days to 12 years |
| Minimum Sum Assured | ₹75,000 |
| Maximum Sum Assured | No fixed limit |
| Maturity age | 25 years |
| Policy term | 25 minus age at entry |
| Premium-paying term | 20 minus age at entry |
| Premium modes | Yearly, half-yearly, quarterly, monthly through ECS and SSS |
The Sum Assured must be in multiples of ₹5,000 from ₹75,000 to ₹1 lakh. Above ₹1 lakh, it must be in multiples of ₹10,000.
What Does the LIC Jeevan Tarun Plan 834 Calculator Show?
The calculatorshows the policy’s premium and benefit details together. After entering the child’s entry age, Sum Assured, selected benefit option and premium mode, it can show:
- Policy term and premium-paying term
- Estimated premium before tax
- Yearly survival benefits from age 20 to 24
- Guaranteed maturity component at age 25
- Total estimated base premium during the payment term
- Illustrative maturity amount after adding a bonus estimate
The calculator should show guaranteed benefits separately from bonuses. Simple Reversionary Bonus and Final Additional Bonus are not fixed in advance.
A surrender value estimate needs additional information, including the current policy year, premiums actually paid, vested bonus and survival benefits already received. The final surrender amount must be confirmed with LIC.
Also Check:
- LIC Jeevan Tarun Calculator All in One
- LIC Jeevan Tarun Plan 734 Calculator
- LIC Jeevan Tarun Plan 934 Calculator
How to Use the Jeevan Tarun Plan 834 Calculator
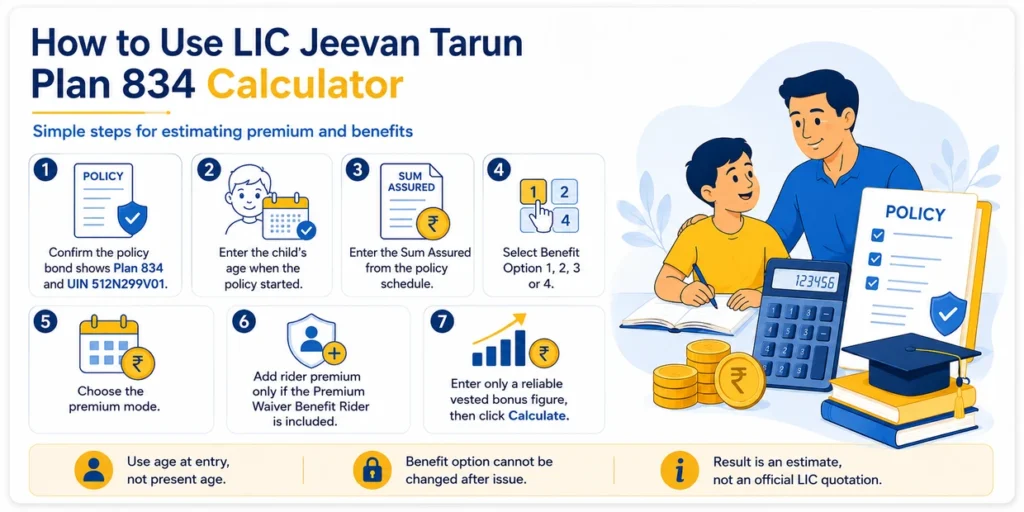
Keep the policy bond or premium receipt nearby before starting. Confirm that the bond shows Plan 834 and UIN 512N299V01.
- Enter the child’s age when the policy started, not the present age.
- Enter the Sum Assured shown in the policy schedule.
- Select the original Benefit Option 1, 2, 3 or 4.
- Choose the premium mode shown in the policy records.
- Enter rider premium only if the Premium Waiver Benefit Rider is included in the policy.
- Add only a reliable vested bonus figure from LIC records. Leave an optional future bonus field at zero if no figure is available.
- Select Calculate to view the estimated premium and benefit schedule.
The selected benefit option cannot be changed after the policy has been issued.
Benefit Options Under Plan 834
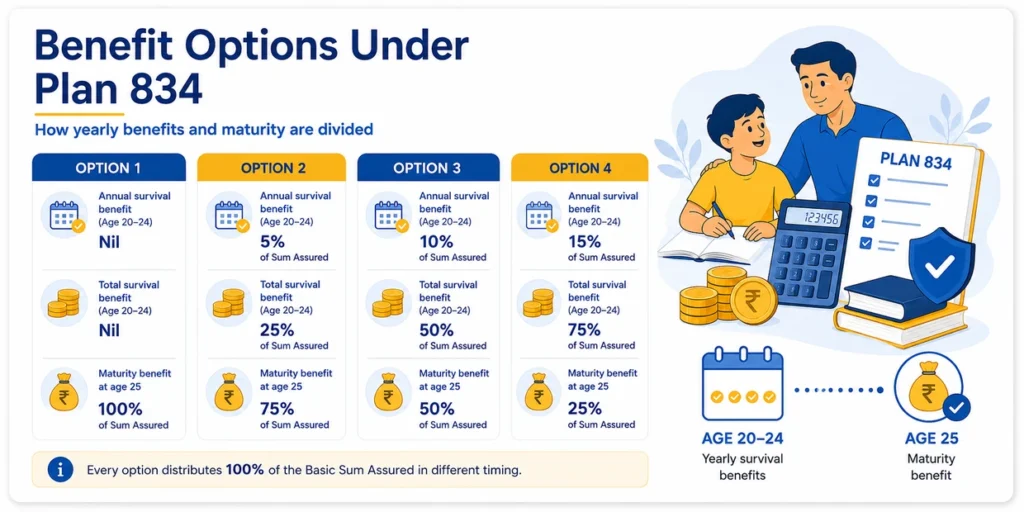
Each option divides the Basic Sum Assured differently between survival benefits and maturity.
| Option | Annual survival benefit from age 20 to 24 | Total survival benefit | Maturity benefit at age 25 |
| Option 1 | Nil | Nil | 100% of Sum Assured |
| Option 2 | 5% of Sum Assured | 25% of Sum Assured | 75% of Sum Assured |
| Option 3 | 10% of Sum Assured | 50% of Sum Assured | 50% of Sum Assured |
| Option 4 | 15% of Sum Assured | 75% of Sum Assured | 25% of Sum Assured |
Option 1 keeps the entire Basic Sum Assured for maturity. Option 4 provides the highest yearly payment but leaves the smallest portion for maturity. When all scheduled survival and maturity benefits are added, every option distributes 100% of the Basic Sum Assured.
Formulas Used in this Jeevan Tarun Plan 834 Calculator
Policy term and premium-paying term
Policy Term = 25 − Age at Entry

Premium-Paying Term = 20 − Age at Entry
If the child enters at age 4:
Policy Term = 25 − 4 = 21 years

Premium-Paying Term = 20 − 4 = 16 years
Premiums stop after 16 years, but the policy continues until the child reaches age 25.
Guaranteed maturity amount
Guaranteed Maturity Amount =
Basic Sum Assured × Maturity Percentage of Selected Option
The final maturity claim may be:
Guaranteed Maturity Amount
+ Vested Simple Reversionary Bonus
+ Final Additional Bonus, if declared and payable
Only the applicable percentage of the Basic Sum Assured is guaranteed for an eligible in-force policy. Bonus amounts are not guaranteed.
Premium calculation
LIC’s brochure provides sample tabular premium rates for selected entry ages. These rates are quoted for every ₹1,000 of Basic Sum Assured.
Tabular Annual Premium =
(Basic Sum Assured ÷ 1,000) × Applicable Premium Rate
Estimated Annual Premium Before Tax =
Tabular Annual Premium
− Mode Rebate
− High Sum Assured Rebate
+ Rider Premium, if selectedApplicable taxes are charged separately.
Sample Premium Rates
The official brochure provides these sample tabular premium rates for a standard life. The rates are per ₹1,000 of Basic Sum Assured and exclude tax.
| Entry age | Option 1 | Option 2 | Option 3 | Option 4 |
| 0 years | ₹44.80 | ₹45.80 | ₹46.80 | ₹47.80 |
| 4 years | ₹55.95 | ₹57.50 | ₹59.00 | ₹60.55 |
| 8 years | ₹75.65 | ₹78.00 | ₹80.40 | ₹82.75 |
| 12 years | ₹112.70 | ₹116.65 | ₹120.60 | ₹124.60 |
These are sample rates, not a complete age-wise premium table. An estimate for another entry age may not match the exact premium written in the policy schedule.
Premium-mode rebate
| Premium mode | Rebate |
| Yearly | 2% of tabular premium |
| Half-yearly | 1% of tabular premium |
| Quarterly | Nil |
| Monthly through ECS | Nil |
| SSS | Nil |
High Sum Assured rebate
| Basic Sum Assured | Rebate on premium |
| ₹75,000 to ₹1,90,000 | Nil |
| ₹2,00,000 to ₹4,90,000 | ₹2 per ₹1,000 of Sum Assured |
| ₹5,00,000 and above | ₹3 per ₹1,000 of Sum Assured |
Real Calculation Example
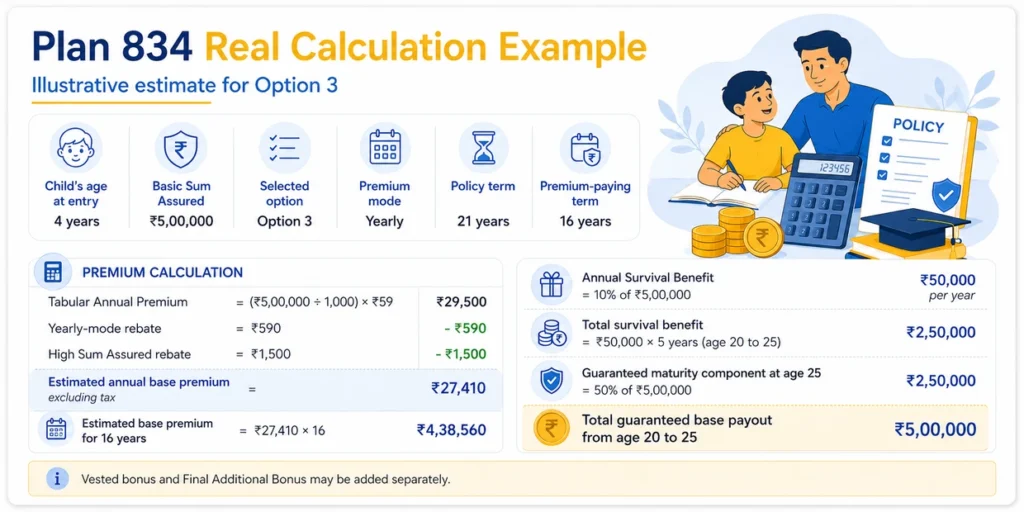
In this calculation, we will fill in the following details:
| Detail | Value |
| Child’s age at entry | 4 years |
| Basic Sum Assured | ₹5,00,000 |
| Selected option | Option 3 |
| Premium mode | Yearly |
| Policy term | 21 years |
| Premium-paying term | 16 years |
For age 4 and Option 3, the sample tabular rate is ₹59 per ₹1,000 of Sum Assured.
Tabular Annual Premium
= (₹5,00,000 ÷ 1,000) × ₹59
= 500 × ₹59
= ₹29,500
Yearly-mode rebate:
2% of ₹29,500 = ₹590High Sum Assured rebate:
₹3 × 500 = ₹1,500Estimated annual base premium:
₹29,500 − ₹590 − ₹1,500
= ₹27,410 excluding tax
Estimated base premium for 16 years:
₹27,410 × 16 = ₹4,38,560This total excludes tax, rider premium and any extra premium.
Benefits in this example
Option 3 pays 10% of the Basic Sum Assured each year from age 20 to 24.
Annual Survival Benefit
= 10% of ₹5,00,000
= ₹50,000
The child receives ₹50,000 each year for five years. The total survival benefit is ₹2,50,000.
At age 25, the guaranteed maturity component is:
50% of ₹5,00,000 = ₹2,50,000The total guaranteed base payout from age 20 to 25 is therefore ₹5,00,000. Vested bonus and Final Additional Bonus, if any, may be added to the maturity claim.
Death Benefit and Risk Commencement Plan 834 Calculator
The death benefit depends on whether death occurs before or after risk cover begins.
Before risk commencement
LIC refunds the premiums paid without interest. Tax, extra premium and rider premium are excluded from the refund.
After risk commencement
For an in-force policy, the Sum Assured on Death is the higher of:
10 × Annualised Premium

or

125% of Basic Sum Assured
The death benefit cannot be less than 105% of the eligible premiums paid up to the date of death. Vested Simple Reversionary Bonus and Final Additional Bonus, if any, are added according to the policy terms.
For a child below age 8 at entry, risk starts on the earlier of:
- One day before completing two years from policy commencement; or
- One day before the policy anniversary on or immediately after the child completes age 8.
For a child aged 8 or above at entry, risk begins immediately. The policy automatically transfers to the child on the policy anniversary on or immediately after age 18. This is known as vesting.
Paid-Up Value
If premiums stop after the minimum required period, the policy may continue with reduced paid-up benefits.
| Premium-paying term | Minimum premiums required |
| Less than 10 years | Two full years’ premiums |
| 10 years or more | Three full years’ premiums |
Death Paid-Up Sum Assured =
(Premiums Paid ÷ Total Premiums Payable)
× Original Sum Assured on Death
Maturity Paid-Up Sum Assured =
[(Premiums Paid ÷ Total Premiums Payable)
× (Maturity Sum Assured + Total Survival Benefits)]
− Survival Benefits Already PaidNo future survival benefits are paid separately after the policy becomes paid-up. Vested bonuses remain attached, but the policy does not participate in future profits. The rider also stops and does not acquire paid-up value.
Surrender Value and Policy Loan in Plan 834
Surrender closes the policy before maturity. It is different from making the policy paid-up.
| Premium-paying term | Surrender eligibility |
| Less than 10 years | After two consecutive full years’ premiums |
| 10 years or more | After three consecutive full years’ premiums |
The Guaranteed Surrender Value is broadly calculated as:
Guaranteed Surrender Value =
(Eligible Premiums Paid × Applicable GSV Factor)
− Survival Benefits Already Paid
+ Surrender Value of Vested Bonus
LIC may instead pay a Special Surrender Value if it is higher.
Final Surrender Value =
Higher of Guaranteed Surrender Value or Special Surrender Value
The applicable factors depend on the policy term and the year of surrender. Therefore, an online calculator can provide only an estimate. LIC must confirm the final amount.
A policy loan may be available after the policy acquires surrender value. The amount, interest rate and conditions are decided by LIC.
Grace Period and Revival
Yearly, half-yearly and quarterly premiums have a grace period of one month, but not less than 30 days. Monthly premiums receive a grace period of 15 days.
If the premium remains unpaid after the grace period, the policy lapses. Plan 834 allows revival within two consecutive years from the first unpaid premium date. Revival requires payment of outstanding premiums with interest and proof of continued insurability, subject to LIC’s approval.
Premium Waiver Benefit Rider
The policy may include LIC’s Premium Waiver Benefit Rider with UIN 512B204V02 on the proposer’s life. It requires an additional premium. The policy schedule should be checked to confirm whether the rider was selected and what benefits apply.
Tax Rule
Applicable tax is charged separately on the premium and does not increase the policy benefits. Tax, extra premium and rider premium are excluded from calculations where the policy terms refer to eligible premiums.
The tax treatment of premiums and policy proceeds depends on the Income Tax rules and individual policy conditions. A qualified tax professional should be consulted for personal advice.
Frequently Asked Questions
Is LIC Jeevan Tarun Plan 834 still available?
No. LIC withdrew Plan 834 from new sales on 1 February 2020. Existing policies continue under their original terms.
Can the benefit option be changed?
No. The option selected when the policy was purchased cannot be changed later.
Which option provides the highest maturity benefit?
Option 1 provides 100% of the Basic Sum Assured at maturity. It does not provide survival benefits from age 20 to 24.
Which option provides the highest yearly payment?
Option 4 pays 15% of the Basic Sum Assured every year for five years. Its maturity component is 25% of the Basic Sum Assured.
Is the bonus guaranteed?
No. Simple Reversionary Bonus and Final Additional Bonus depend on LIC’s declarations and the policy terms.
Can the calculator show the exact surrender value?
Not always. The result depends on the applicable surrender factors, actual premiums paid, policy year, vested bonus and benefits already received.
Can a lapsed Plan 834 policy be revived?
It may be revived within two consecutive years from the first unpaid premium date, subject to LIC’s conditions and approval.
Conclusion
LIC Jeevan Tarun Plan 834 distributes the Basic Sum Assured between payments from age 20 to 24 and a maturity payment at age 25. The exact payment pattern depends on the option selected when the policy was purchased.
The calculator makes it easier to estimate the premium period, survival benefits, guaranteed maturity amount and possible paid-up or surrender value. Its results are for planning only. The policy bond and LIC’s official records remain the final source for policy benefits and claim amounts.