LIC Jeevan Saathi Calculator Plans 89, 197, 888, And 889
Calculation Result
Benefit Details
Year-wise Schedule
LIC has offered different joint-life insurance plans for married couples. These plans cover both spouses under one policy, but their benefits are not the same. Some plans provide bonuses, one builds a market-linked fund, and the latest plans provide guaranteed additions.
The LIC Jeevan Sathi Calculator brings these plans into one place. It covers Jeevan Saathi Plan 89, Jeevan Saathi Plus Plan 197, New Jeevan Sathi Single Premium Plan 888 and New Jeevan Sathi Limited Premium Plan 889.
After selecting a plan, the calculator shows only the fields needed for that plan. It can estimate maturity benefit, bonuses, fund value, guaranteed additions, total premiums and the benefits payable on the first, second or simultaneous death.
What Is the LIC Jeevan Sathi Calculator?
The LIC Jeevan Sathi Calculator is a joint-life policy calculator made for policies covering a husband and wife. One spouse is called the Primary Life Assured, and the other is called the Secondary Life Assured.
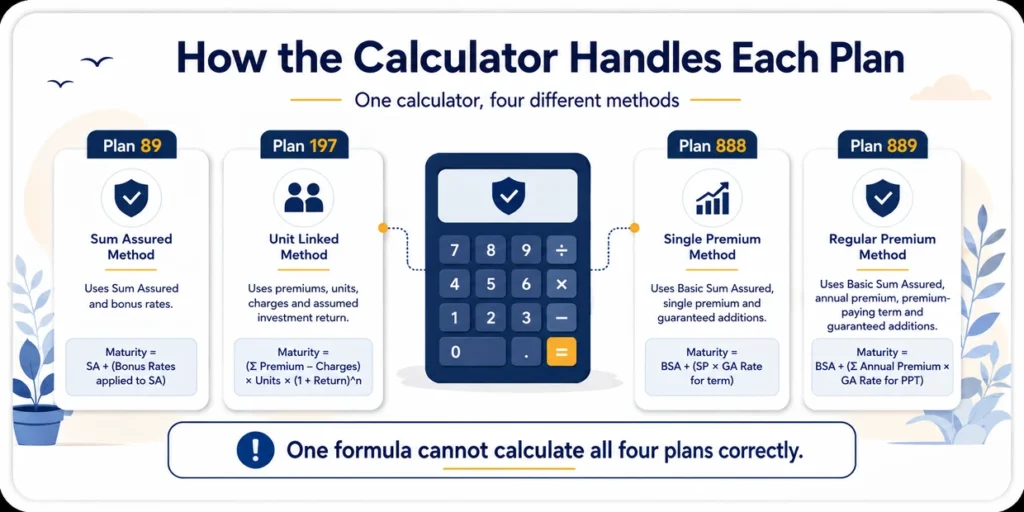
The calculator changes its calculation method according to the selected plan:
- Plan 89 uses the Sum Assured and entered bonus rates.
- Plan 197 uses premiums, units, charges and an assumed investment return.
- Plan 888 uses the Basic Sum Assured, single premium and guaranteed additions.
- Plan 889 uses the Basic Sum Assured, annual premium, premium-paying term and guaranteed additions.
This plan-wise method is important because a single formula cannot calculate all four policies correctly.
What Are LIC Jeevan Sathi Plans?
LIC Jeevan Sathi plans are joint-life insurance policies made for married couples. Both spouses receive life cover under one contract. Depending on the plan, the policy may pay a benefit after the first death, continue cover for the surviving spouse and pay another benefit after the second death.
Some plans also provide a maturity benefit if at least one spouse survives until the end of the policy term.
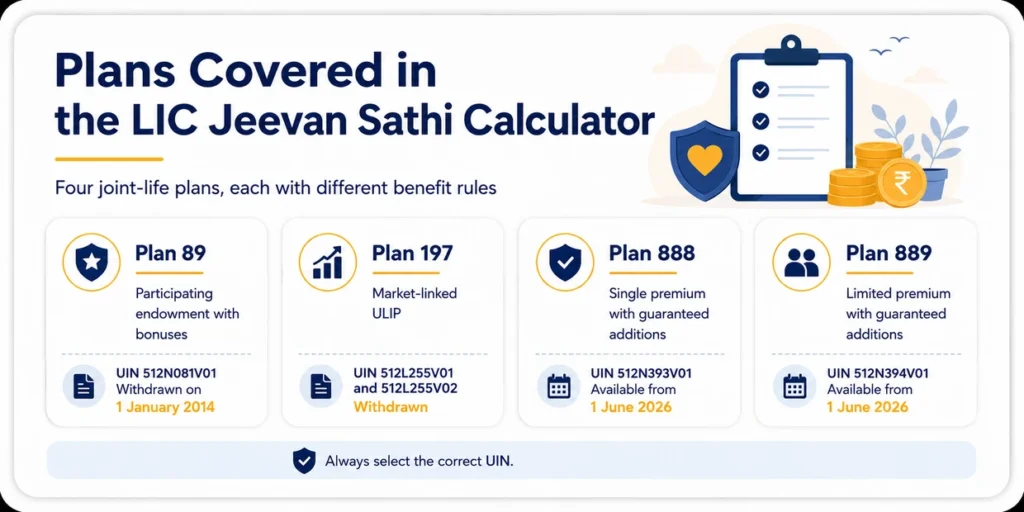
The calculator covers the following plans:
| Plan | UIN | Status | Main Benefit Type |
|---|---|---|---|
| Jeevan Saathi Plan 89 | 512N081V01 | Withdrawn on 1 January 2014 | Participating endowment with bonuses |
| Jeevan Saathi Plus Plan 197 | 512L255V01 and 512L255V02 | Withdrawn | Market-linked ULIP |
| New Jeevan Sathi Single Premium Plan 888 | 512N393V01 | Available from 1 June 2026 | Single premium with guaranteed additions |
| New Jeevan Sathi Limited Premium Plan 889 | 512N394V01 | Available from 1 June 2026 | Limited premium with guaranteed additions |
The exact UIN should always be selected because rules and charges may change between policy versions.
Quick Comparison of Plans 89, 197, 888 and 889
Jeevan Saathi Plan 89
Plan 89 is a participating endowment policy. Premiums were payable during the term or until the first death, whichever happened earlier. It could earn Simple Reversionary Bonus and may also receive a Final Additional Bonus.
On the first death during the term, one Sum Assured was payable. If the surviving spouse also died during the remaining term, another Sum Assured with applicable bonuses was payable. If one or both spouses survived until maturity, the Sum Assured with applicable bonuses was paid.
Jeevan Saathi Plus Plan 197
Plan 197 is a market-linked ULIP. Premiums were invested in the selected fund after applicable charges. The available funds included Bond, Secured, Balanced and Growth funds.
Its maturity value depends on the policyholder’s fund value. The result is not guaranteed because unit prices change with market performance. The calculator can project a possible value, but it cannot predict the actual future NAV.
New Jeevan Sathi Single Premium Plan 888
Plan 888 is a non-linked, non-participating joint-life endowment plan. It requires one premium payment and provides guaranteed additions of ₹70 per ₹1,000 of Basic Sum Assured at the end of every policy year.
It offers two death-benefit options. The selected option changes the Sum Assured on Death and cannot be changed later.
New Jeevan Sathi Limited Premium Plan 889
Plan 889 is also non-linked and non-participating, but premiums are paid for a limited period. It provides guaranteed additions based on the Total Tabular Annual Premium paid.
If the first death happens while the policy is in force, the Sum Assured on Death is paid and the policy continues for the surviving spouse. Future base premiums from the policy anniversary after the first death are waived. Rider premiums on the surviving life are not automatically waived.
Highlights of the LIC Jeevan Sathi Calculator
- Covers Plans 89, 197, 888 and 889.
- Supports both UIN versions of Plan 197.
- Uses separate calculations for each plan.
- Estimates first-death, second-death and simultaneous-death benefits.
- Calculates bonuses for Plan 89.
- Projects market-linked fund value for Plan 197.
- Calculates guaranteed additions for Plans 888 and 889.
- Shows maturity benefit and total premiums.
- Applies plan-specific age, term and Sum Assured checks.
- Provides a year-wise benefit schedule.
- Separates guaranteed amounts from estimated amounts.
- Works on mobile, tablet and desktop screens.
Details Required for Each Plan
Details for Plan 89
Enter the ages of both spouses, policy term, completed policy year, Sum Assured, annual basic premium, Simple Reversionary Bonus rate and Final Additional Bonus.
Use the actual vested bonus shown in the policy record whenever it is available. A future bonus entered in the calculator is only an assumption.
Details for Plan 197
Select UIN V01 or V02 first. Then enter the premium type, payment mode, both ages, policy term, premium, life cover for both spouses, fund type and assumed annual return.
Top-up premiums and partial withdrawals should be entered only when they apply to the policy. The projected value also depends on the charges included in the selected UIN version.
Details for Plan 888
Enter both ages, policy term, Basic Sum Assured, Tabular Single Premium and Death Benefit Option I or II.
The Tabular Single Premium should be taken from an LIC quotation. It is the base premium before rebates, loadings, underwriting extra, rider premium and tax.
Details for Plan 889
Enter both ages, policy term, premium-paying term, payment mode, Basic Sum Assured, Total Tabular Annual Premium and Death Benefit Option I or II.
Select eligible incentives only when they apply to the policy. The official LIC quotation should be used for the tabular premium.
How to Use the LIC Jeevan Sathi Calculator
- Select the plan number.
- For Plan 197, select the correct UIN version.
- Enter the ages of both spouses.
- Enter the policy term and premium-paying term where required.
- Enter the Sum Assured and premium details.
- Add the bonus rate, investment return or incentive details required by the selected plan.
- Choose the death-benefit option for Plan 888 or 889.
- Select the calculation year if a year-wise benefit is required.
- Press Calculate to view the results.
- Use Reset to clear the entered details and start a new calculation.
Check every input before using the result. A different age, term, UIN or death option can change the benefits.
Formula Used for Each Plan
Formula for Jeevan Sathi Plan 89
The bonus is generally declared for every ₹1,000 of Sum Assured.
Estimated Simple Reversionary Bonus =
(Sum Assured ÷ 1,000) × Bonus Rate × Completed Policy Years
Estimated Maturity Benefit =
Sum Assured + Vested Bonus + Final Additional BonusOn the first death during the term:
First-Death Benefit = Sum AssuredIf the surviving spouse dies during the remaining term:
Second-Death Benefit =
Sum Assured + Applicable Bonuses
Future bonuses are not guaranteed until LIC declares them.
Formula for Jeevan Sathi Plus Plan 197
Plan 197 does not have a fixed maturity formula like a traditional endowment plan.
Fund Value = Number of Units × Applicable NAVFor a projection, the calculator applies the entered return after allowing for the charges included in the selected plan version.
Projected Closing Fund Value =
Opening Fund Value
+ Premium Allocated to Units
+ Assumed Investment Growth
− Applicable Charges
− Partial Withdrawals
Possible charges include premium allocation, mortality, policy administration and fund management charges. The exact result depends on the policy UIN and actual NAV movement.
Formula for New Jeevan Sathi Plan 888
Guaranteed additions are based on the Basic Sum Assured.
Guaranteed Addition per Year =
(Basic Sum Assured ÷ 1,000) × ₹70
Maturity Benefit =
Basic Sum Assured + Accrued Guaranteed AdditionsThe Sum Assured on Death is calculated as follows:
Option I = Higher of:
1.25 × Tabular Single Premium
OR
Basic Sum Assured
Option II =
10 × Tabular Single PremiumFormula for New Jeevan Sathi Plan 889
The basic guaranteed-addition rate is 7% of the Total Tabular Annual Premium paid. Eligible incentives can increase this rate.
Guaranteed Addition for a Premium =
Total Tabular Annual Premium × Applicable Addition Rate
Maturity Benefit =
Basic Sum Assured + Total Accrued Guaranteed AdditionsThe Sum Assured on Death is:
Option I = Higher of:
7 × Tabular Annual Premium
OR
Basic Sum Assured
Option II = Higher of:
10.5 × Tabular Annual Premium
OR
Basic Sum AssuredThe applicable death benefit must also satisfy the policy’s minimum requirement of 105% of total premiums paid up to the date of death.
How Joint-Life Death Benefits Work
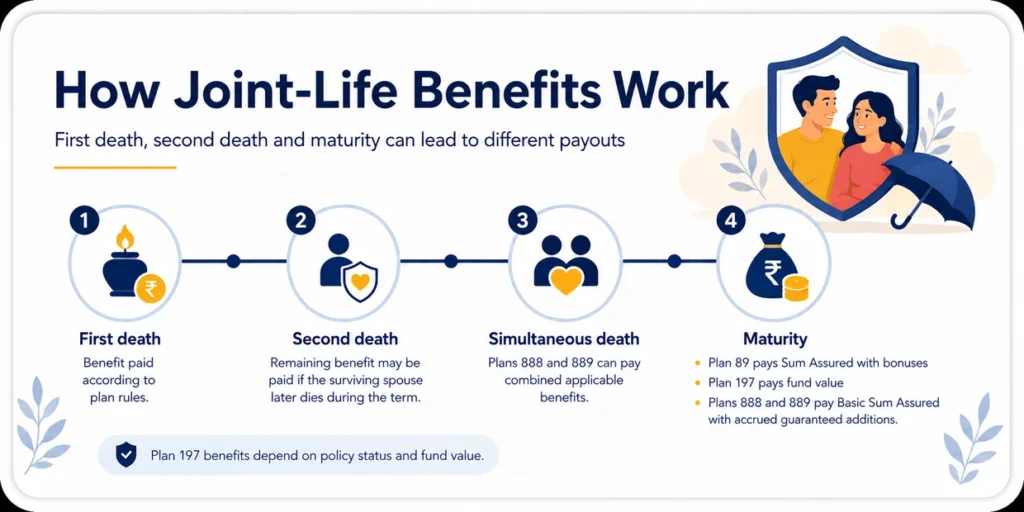
First death
The first-death benefit is paid when one insured spouse dies during the policy term. The policy may continue for the surviving spouse according to the selected plan rules.
Under Plans 888 and 889, the Sum Assured on Death is paid after the first death, and the policy continues.
Second death
The second-death benefit is paid if the surviving spouse also dies during the policy term. Under Plans 888 and 889, it includes the Sum Assured on Death and accrued guaranteed additions. The policy then ends.
Simultaneous death
If both insured spouses die in the same event during the term, Plans 888 and 889 pay the total of the applicable first-death and second-death benefits. The policy then ends.
Death benefits under Plan 197 depend on the exact policy status, which spouse dies first, the selected cover and the available fund value. The calculator should therefore apply the rules of the selected UIN instead of using the benefit formula of another plan.
Maturity Benefit Under Each Plan
Plan 89 pays the Sum Assured with applicable bonuses if one or both spouses survive until maturity.
Plan 197 pays the policyholder’s fund value. This amount is not guaranteed.
Plans 888 and 889 pay the Basic Sum Assured with accrued guaranteed additions if at least one life assured survives until maturity and the policy conditions are met.
Guaranteed Additions Under Plans 888 and 889
Plan 888 provides ₹70 for every ₹1,000 of Basic Sum Assured at the end of each policy year. For example, a Basic Sum Assured of ₹10,00,000 earns:
₹10,00,000 ÷ ₹1,000 × ₹70
= ₹70,000 per policy year
Plan 889 calculates additions differently. Each paid premium earns additions according to the applicable rate. A premium paid early can earn additions for more policy years than a premium paid later. This is why total additions at maturity cannot be calculated by simply multiplying one year’s addition by the premium-paying term.
Real Calculation Example for Plan 889
Consider the official LIC illustration with these details:
| Particular | Selected Value |
| Primary life age | 35 years |
| Secondary life age | 35 years |
| Policy term | 25 years |
| Premium-paying term | 15 years |
| Basic Sum Assured | ₹10,00,000 |
| Tabular Annual Premium | ₹83,650 |
| Payment mode | Yearly |
| Death Benefit Option | Option I |
| Sales channel | Offline |
Under Option I:
7 × ₹83,650 = ₹5,85,550

Basic Sum Assured = ₹10,00,000
The higher amount is ₹10,00,000. Therefore, the Sum Assured on Death at the start of the policy is ₹10,00,000.
For a Basic Sum Assured of ₹10,00,000 and a 25-year term, the high Sum Assured incentive is 0.80%. The total guaranteed-addition rate becomes:
Basic Rate                 = 7.00%
High Sum Assured Incentive = 0.80%
Total Rate                 = 7.80%
First-Year Guaranteed Addition =
₹83,650 × 7.80%
= ₹6,524.70LIC’s illustration rounds this to ₹6,525. At the end of 25 years, the official illustration shows total guaranteed additions of ₹17,61,669.
Basic Sum Assured          = ₹10,00,000
Guaranteed Additions       = ₹17,61,669
Estimated Maturity Benefit = ₹27,61,669
Total basic premiums paid over 15 years are:
₹83,650 × 15 = ₹12,54,750At the end of policy year 10, the official illustration shows accrued guaranteed additions of ₹3,58,859. If the second death happens at that time, the estimated benefit is:
Sum Assured on Death = ₹10,00,000
Guaranteed Additions = ₹3,58,859
Second-Death Benefit = ₹13,58,859
This is an official illustration for the stated details. A different age, term, premium, Sum Assured, option or sales channel will produce a different result.
Surrender, Paid-Up Value and Policy Loan
Plan 89 could normally acquire a surrender value after the required premiums had been paid. Its guaranteed surrender value was based on eligible basic premiums, while LIC could pay a higher Special Surrender Value.
Under Plan 197, surrender value depends on the policyholder’s fund value and the rules of the selected UIN. For the revised version, the amount became payable after the third policy anniversary. An exact historical result requires the correct NAV and policy records.
Plan 888 can be surrendered during the policy term. LIC pays the higher applicable value under the Guaranteed Surrender Value and Special Surrender Value rules. A policy loan is available after three months from issue or after the free-look period, whichever is later. The maximum loan percentage depends on the policy year.
Plan 889 can acquire surrender and paid-up benefits according to the premiums paid and policy conditions. A loan is available after the first policy year when at least one full year’s premium has been paid. The official brochure allows up to 75% of surrender value for an in-force policy and 50% for a paid-up policy.
Surrender and paid-up calculations need official factors. The calculator should clearly mark them as estimates unless all applicable LIC factors are included.
Understanding the Calculator Results
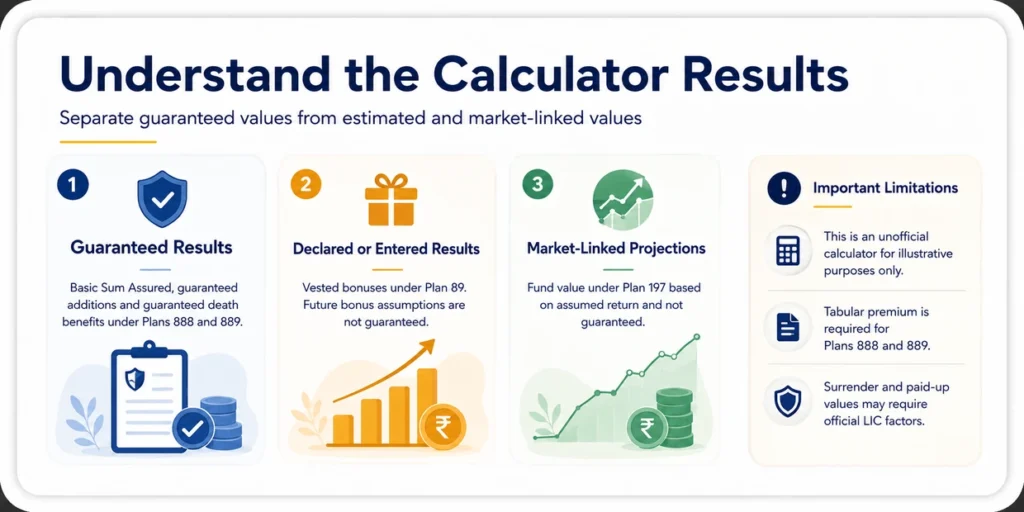
The result section should separate amounts into three groups:
Guaranteed results: Basic Sum Assured, guaranteed additions and guaranteed death benefits under Plans 888 and 889, subject to policy status and entered details.
Declared or entered results: Vested bonuses under Plan 89. A bonus already declared becomes part of the policy benefit, while a future assumed bonus is not guaranteed.
Market-linked projections: Fund value under Plan 197. This is based on an assumed return and cannot show the actual future value.
The year-wise schedule helps show how premiums, bonuses, additions and fund value may change during the policy term.
Important Calculator Limitations
The calculator does not generate an official LIC premium. Plans 888 and 889 require the correct tabular premium from an LIC quotation.
Plan 89 results depend on the entered bonus rate. Future bonus rates may be different.
Plan 197 results depend on NAV movement, policy charges, mortality costs, fund choice, top-ups and withdrawals. The projected fund value is not guaranteed.
Surrender value, Special Surrender Value and paid-up value may require official factors that are not fixed for every policy year. Confirm these amounts with LIC before making a decision.
Tax Rule
Tax treatment depends on the policy, premium, issue date, benefit type and tax rules applicable in the relevant financial year. Tax paid with a premium is not normally included in the calculation of policy benefits.
Because tax laws can change, tax eligibility should be checked under the current rules or with a qualified tax professional.
Frequently Asked Questions
Which plans are included in the LIC Jeevan Sathi Calculator?
The calculator covers Jeevan Sathi Plan 89, Jeevan Sathi Plus Plan 197 with UIN V01 and V02, New Jeevan Sathi Single Premium Plan 888 and New Jeevan Sathi Limited Premium Plan 889.
Can one policy cover both husband and wife?
Yes. These are joint-life plans made to cover two married spouses under one policy. One spouse is the Primary Life Assured, and the other is the Secondary Life Assured.
What happens after the first spouse dies?
The first-death benefit is paid according to the selected plan. Under Plans 888 and 889, the policy continues for the surviving spouse. Under Plan 889, future base premiums are waived from the policy anniversary after the first death, subject to the policy conditions.
Are Plan 89 bonuses and Plan 197 fund value guaranteed?
Future Plan 89 bonuses are not guaranteed until LIC declares them. Plan 197 fund value is market-linked and can rise or fall with NAV performance.
Does the calculator provide an official LIC premium or claim amount?
No. It provides an estimate using the entered details. The LIC quotation, policy schedule, benefit illustration and claim decision remain final.
Conclusion
The LIC Jeevan Sathi Calculator makes four different joint-life plans easier to understand. It can estimate bonuses for Plan 89, project fund value for Plan 197 and calculate guaranteed additions for Plans 888 and 889.
It also explains how benefits may be paid after the first, second or simultaneous death. However, each plan follows different rules. The correct plan number, UIN, premium, ages, term and policy status must be entered before using the result.
Use the calculator for understanding and comparing benefits, but confirm premium, surrender and claim amounts from LIC before taking any financial decision.