LIC New Jeevan Sathi Limited Premium Plan 889 Calculator
Plan No. 889 – Limited Premium
Calculate Premium & Benefits
Premium & Benefits Estimate
Indicative ResultPolicy Details
- Basic Sum Assured₹0
- Death Benefit Option—
- Policy Term—
- Premium Paying Term—
- Premium Reference Age—
Benefit Summary
- Death Cover at Inception₹0
- Annual Guaranteed Addition₹0
- High BSA Incentive0%
- Online Sale Incentive0%
- Existing LIC Incentive0%
Premium is an estimated planning value. Actual official premium may differ due to both ages, underwriting, health conditions, rider selection, occupation, GST and LIC approval.
LIC New Jeevan Sathi Plan 889 Calculator helps a married couple understand the premium and benefits of this joint-life policy. It can estimate the premium, Guaranteed Additions, maturity amount and death benefits after the policy details are entered.
The official name of this product is LIC’s New Jeevan Sathi – Limited Premium. Its plan number is 889 and UIN is 512N394V01. The plan became available for purchase on 1 June 2026.
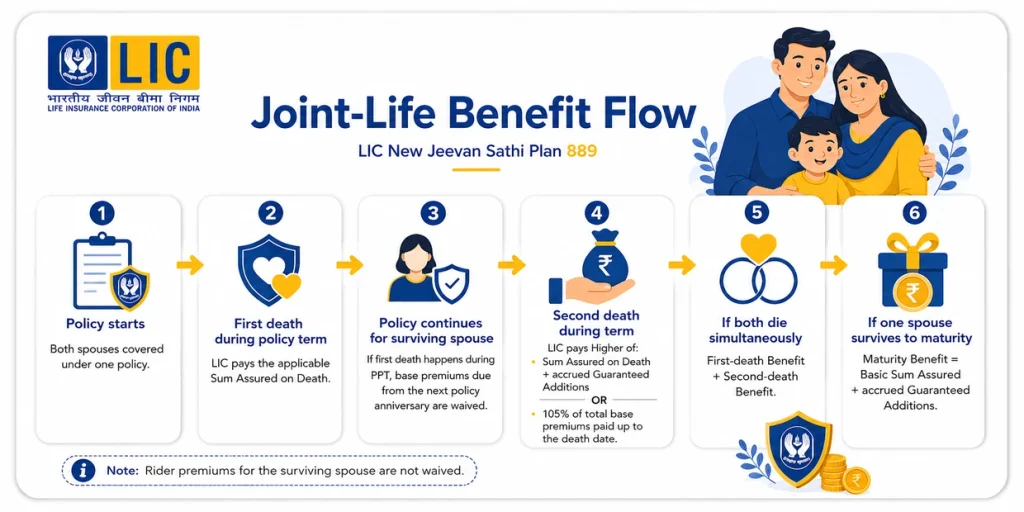
In this plan both spouses are covered under one policy. Premiums are paid for a limited number of years, but the cover continues for the full policy term. If the first death happens while the policy is in force, LIC pays the applicable death benefit and the policy continues for the surviving spouse. Base-policy premiums due from the policy anniversary following the first death are waived.
This is a non-linked and non-participating plan. Its benefits are not linked to the share market, and it does not earn LIC bonuses. Guaranteed Additions are calculated according to the policy rules.
What Is the LIC New Jeevan Sathi Plan 889 Calculator?
This calculator cover Plan 889 calculations into one place. It checks the ages of both spouses, allowed policy term, premium-paying term and death benefit option. It can also apply the Guaranteed Addition incentives available for a higher Basic Sum Assured, eligible online purchase and eligible LIC relationship.
In calculator give result we can see:
- Estimated yearly and modal premium
- Total estimated base premium
- Applicable Guaranteed Addition rate
- Year-wise Guaranteed Additions
- Estimated maturity benefit
- First-death and second-death benefits
- Premium waiver after the first death
- Paid-up, surrender and policy-loan estimates
Also Check:
- New Jeevan Sathi Plan 197 Calculator
- New Jeevan Sathi Plan 888 Calculator
- Jeevan Saathi Plan 89 Maturity Calculator
- LIC Jeevan Sathi Calculator
What Is LIC New Jeevan Sathi Plan 889?
Plan 889 is a joint-life limited-premium endowment plan for a married individual and spouse. The buyer is called the Primary Life Assured, and the spouse is called the Secondary Life Assured. The Primary Life Assured is the policyholder at the start. If this person dies first, the surviving spouse becomes the policyholder.
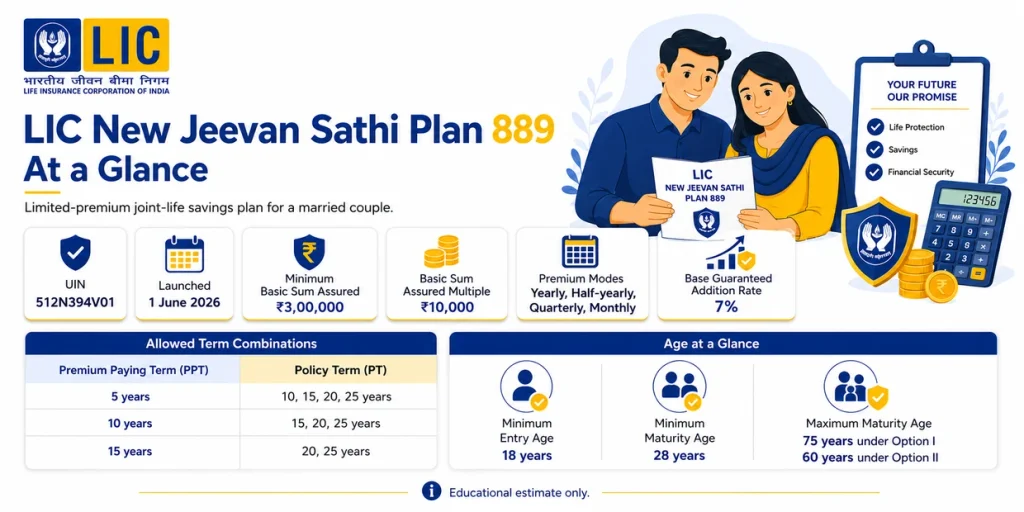
| Feature | Details |
|---|---|
| Official name | LIC’s New Jeevan Sathi – Limited Premium |
| Plan number | 889 |
| UIN | 512N394V01 |
| Plan type | Non-par, non-linked, individual savings plan |
| Lives covered | Married couple under one policy |
| Policy term | 10, 15, 20 or 25 years |
| Premium-paying term | 5, 10 or 15 years |
| Minimum Basic Sum Assured | ₹3,00,000 |
| Basic Sum Assured multiple | ₹10,000 |
| Base Guaranteed Addition rate | 7% |
| Premium modes | Yearly, half-yearly, quarterly and monthly |
Highlights of the LIC New Jeevan Sathi Plan 889 Calculator
- Supports Option I and Option II.
- Checks the age limits of both spouses.
- Allows only valid policy and premium-paying term combinations.
- Converts yearly premium into other payment modes.
- Applies eligible Guaranteed Addition incentives.
- Calculates maturity and joint-life death benefits.
- Shows how Guaranteed Additions grow each year.
- Estimates paid-up, surrender and loan values separately.
Eligibility Conditions
Both spouses must meet the age rules for the selected option. The minimum entry age is 18 years completed. The minimum maturity age is 28 years completed.
| Premium-paying term | Policy term | Option I maximum entry age | Option II maximum entry age |
| 5 years | 10 years | 45 years | 40 years |
| 5 years | 15 years | 45 years | 40 years |
| 5 years | 20 years | 45 years | 40 years |
| 5 years | 25 years | 45 years | 35 years |
| 10 years | 15 years | 50 years | 40 years |
| 10 years | 20 years | 50 years | 40 years |
| 10 years | 25 years | 50 years | 35 years |
| 15 years | 20 years | 50 years | 40 years |
| 15 years | 25 years | 50 years | 35 years |
The maximum maturity age is 75 years nearer birthday under Option I and 60 years nearer birthday under Option II. LIC does not state a fixed maximum Basic Sum Assured, but the accepted amount depends on its underwriting rules.
Policy Term and Premium-Paying Term
Only these combinations are allowed:
| Premium-paying term | Available policy terms |
| 5 years | 10, 15, 20 or 25 years |
| 10 years | 15, 20 or 25 years |
| 15 years | 20 or 25 years |
For example, with a 25-year policy term and 15-year premium-paying term, scheduled premiums are paid for 15 years. The policy benefits continue until the end of year 25, provided the policy remains in force.
Option I and Option II
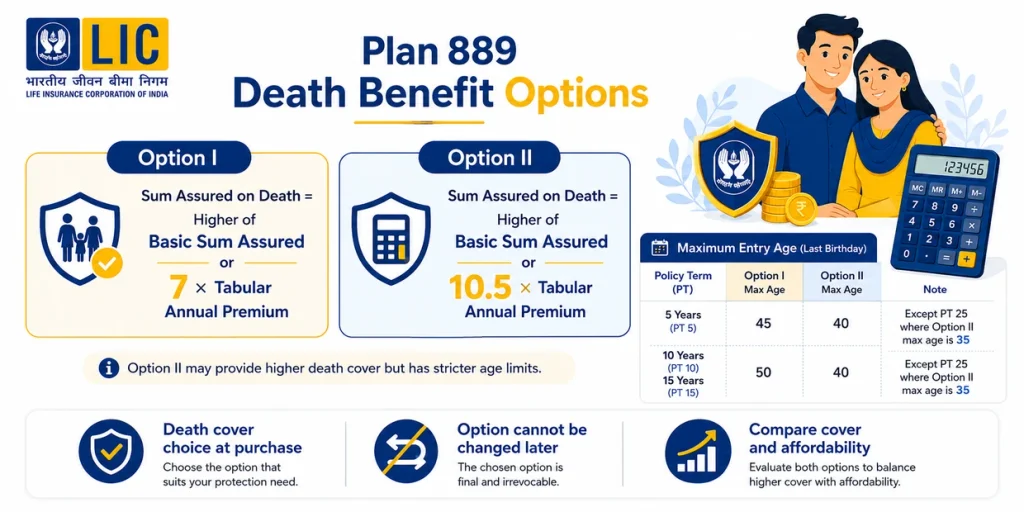
The death benefit option is selected when the policy is purchased and cannot be changed later.
| Option | Sum Assured on Death |
| Option I | Higher of Basic Sum Assured or 7 times Tabular Annual Premium |
| Option II | Higher of Basic Sum Assured or 10.5 times Tabular Annual Premium |
Tabular Annual Premium is the yearly premium calculated from the Basic Sum Assured, selected option and ages of both spouses before rebates, loading, underwriting extra, rider premiums and tax.
Option II may provide a higher death cover, but it has stricter age limits. The premium, cover and affordability should be compared before selecting an option.
How to Use the LIC New Jeevan Sathi Plan 889 Calculator
- Enter the age nearer birthday of both spouses.
- Select Option I or Option II.
- Select an allowed policy term and premium-paying term.
- Enter a Basic Sum Assured of at least ₹3,00,000 in multiples of ₹10,000.
- Select yearly, half-yearly, quarterly or monthly premium mode.
- Choose online or offline purchase.
- Select an LIC relationship incentive only when the official conditions are met.
- Press the calculate button and check the premium, death cover, Guaranteed Additions and maturity value.
The calculator should display an error when an age, amount or term combination is not allowed.
Formulas Used in the LIC New Jeevan Sathi Plan 889 Calculator
Premium for Different Payment Modes
Modal Premium = Yearly Premium × Premium Conversion Factor| Premium mode | Conversion factor |
| Yearly | 1.0000 |
| Half-yearly | 0.5090 |
| Quarterly | 0.2568 |
| Monthly | 0.0861 |
For example, if the yearly premium is ₹80,000, the half-yearly premium is approximately ₹40,720 before tax, riders or underwriting extra.
Death Benefit
Option I Sum Assured on Death =
Higher of Basic Sum Assured or
7 × Tabular Annual Premium
Option II Sum Assured on Death =
Higher of Basic Sum Assured or
10.5 × Tabular Annual PremiumFirst-Death Benefit = Sum Assured on DeathSecond-Death Benefit = Higher of:
Sum Assured on Death + Accrued Guaranteed Additions
or
105% of Total Base Premiums Paid up to the death dateSimultaneous-Death Benefit =
First-Death Benefit + Second-Death BenefitGuaranteed Additions
The basic Guaranteed Addition rate is 7%. Eligible incentives are added to this rate.
Applicable GA Rate =
7% + High Sum Assured Incentive
+ Online Incentive, if eligible
+ LIC Relationship Incentive, if eligible
For an in-force policy, every paid yearly premium increases the premium base used for the Guaranteed Addition calculation.
Guaranteed Addition for a Policy Year =
Applicable GA Rate × Cumulative Tabular Annual Premium
For a fully paid policy with yearly premiums, total Guaranteed Additions at maturity can be estimated as:
Total Guaranteed Additions =
GA Rate × Tabular Annual Premium ×
[PPT × (PPT + 1) ÷ 2
+ PPT × (Policy Term − PPT)]
This formula assumes every scheduled premium is paid and the policy remains in force.
Maturity Benefit =
Basic Sum Assured + Accrued Guaranteed Additions
Paid-Up Value
If at least one full-year premium has been paid and later premiums are missed, the policy can continue with reduced benefits.
Death Paid-Up Sum Assured =
Sum Assured on Death ×
Completed Premium-Paying Period ÷ Original PPT
Maturity Paid-Up Sum Assured =
Basic Sum Assured ×
Completed Premium-Paying Period ÷ Original PPTGuaranteed Additions for a paid-up policy require a separate reduced-rate calculation. Therefore, the calculator should label this result as an estimate.
Surrender Value and Loan
GSV on Premiums =
Eligible Total Premiums Paid × Applicable GSV Factor
GSV-Based Surrender Value =
GSV on Premiums
+ Accrued Guaranteed Additions × Applicable GA GSV FactorLIC pays the higher of this GSV-based amount or Special Surrender Value.
Maximum Policy Loan =
Applicable Surrender Value × Loan Percentage
The maximum percentage is 75% for an in-force policy and 50% for a paid-up policy.
How Guaranteed Addition Incentives Work
High Basic Sum Assured Incentive
| Basic Sum Assured | 10 years | 15 years | 20 years | 25 years |
| ₹3 lakh to below ₹5 lakh | 0.00% | 0.00% | 0.00% | 0.00% |
| ₹5 lakh to below ₹10 lakh | 0.15% | 0.15% | 0.20% | 0.40% |
| ₹10 lakh to below ₹15 lakh | 0.30% | 0.30% | 0.45% | 0.80% |
| ₹15 lakh and above | 0.35% | 0.35% | 0.55% | 1.00% |
Online and LIC Relationship Incentives
An online proposal completed without an agent or intermediary can receive an additional GA rate of 0.75% for a 5-year PPT, 0.95% for a 10-year PPT or 1.25% for a 15-year PPT.
An eligible existing policyholder or eligible nominee or beneficiary of a deceased LIC policyholder can receive an additional rate of 0.05% for a 5-year PPT and 0.10% for a 10-year or 15-year PPT. The official eligibility conditions must be met.
First Death, Second Death and Premium Waiver
On the first death during the policy term, LIC pays the Sum Assured on Death to the surviving spouse, provided the policy is in force and all due premiums have been paid. The policy then continues for the surviving spouse.
If the first death happens during the premium-paying term, base premiums due from the policy anniversary following the death are waived. Rider premiums for the surviving spouse are not waived and must be paid according to the rider conditions.
On the second death during the term, LIC pays the Sum Assured on Death plus accrued Guaranteed Additions, subject to the minimum death-benefit rule. The policy ends after payment. If both spouses die simultaneously, the applicable first-death and second-death benefits are added and paid to the beneficiaries.
Real Calculation Example
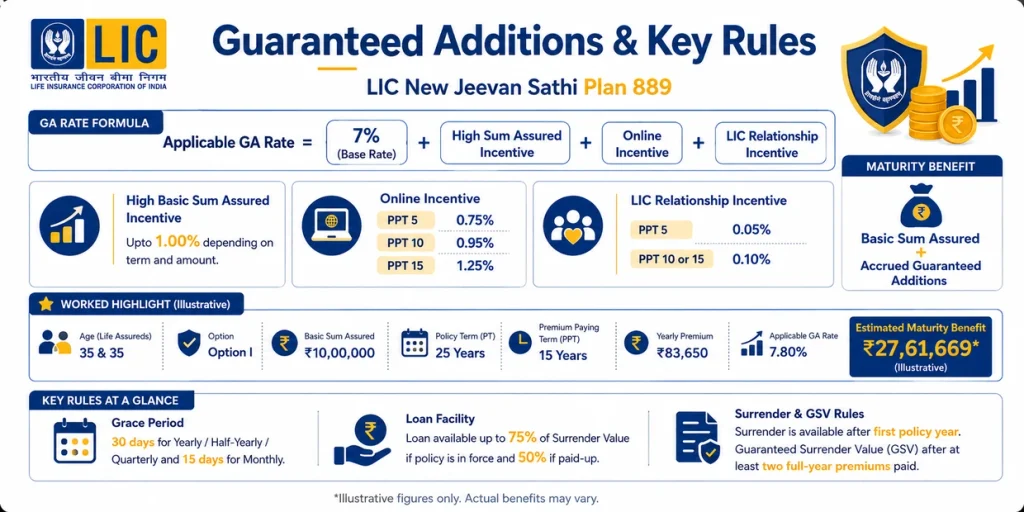
| Policy detail | Selected value |
| Ages of both spouses | 35 years |
| Death Benefit Option | Option I |
| Basic Sum Assured | ₹10,00,000 |
| Policy term | 25 years |
| Premium-paying term | 15 years |
| Purchase channel | Offline |
| Yearly premium | ₹83,650 |
For a ₹10 lakh Basic Sum Assured and 25-year term, the high Sum Assured incentive is 0.80%.
Applicable GA Rate = 7.00% + 0.80% = 7.80%Total base premiums paid over 15 years are:
₹83,650 × 15 = ₹12,54,750Estimated total Guaranteed Additions are:
₹83,650 × 7.80% ×
[15 × 16 ÷ 2 + 15 × (25 − 15)]

= ₹17,61,669
The maturity benefit is:
Basic Sum Assured             ₹10,00,000
Guaranteed Additions          ₹17,61,669
Maturity Benefit              ₹27,61,669
The initial Sum Assured on Death under Option I is ₹10,00,000 because seven times the Tabular Annual Premium is lower than the Basic Sum Assured. LIC’s illustration shows a first-death benefit of ₹10,00,000.
At the end of policy year 10, accrued Guaranteed Additions are approximately ₹3,58,859. A second death at that time would produce an estimated benefit of ₹13,58,859, subject to policy conditions and the 105% minimum rule.
Grace Period, Paid-Up Policy and Revival
The grace period is 30 days for yearly, half-yearly and quarterly premiums, and 15 days for monthly premiums. The policy remains in force during this period.
If the premium is not paid within the grace period, the policy lapses. When at least one full-year premium has already been paid, it can continue with reduced paid-up benefits after completion of the first policy year.
A lapsed or paid-up policy may be revived while both spouses are alive, within five consecutive years from the first unpaid premium and before the policy term ends. Arrears and interest must be paid, and LIC may ask for proof of continued insurability for both spouses.
Surrender Value and Policy Loan
The policy can be surrendered after completion of the first policy year if at least one full-year premium has been paid. Special Surrender Value can then become available. Guaranteed Surrender Value is acquired after at least two full-year premiums have been paid.
LIC pays the higher of the GSV-based amount or Special Surrender Value. The Special Surrender Value is reviewed by LIC, so an unofficial calculator cannot confirm it. Rider premiums do not receive surrender value.
A policy loan is available after completion of the first policy year when at least one full-year premium has been paid. LIC can allow up to 75% of surrender value for an in-force policy and 50% for a paid-up policy. The final loan amount and interest rate are decided when the loan is approved.
Optional Riders
The following riders are available subject to their conditions and payment of an extra premium:
- LIC’s Accident Benefit Rider
- LIC’s New Term Assurance Rider
- LIC’s Critical Illness Health Rider
The Accident Benefit Rider may be added during the premium-paying term when at least five years of the base-plan and rider terms remain. The other two riders are available only when the policy starts. Rider benefits should not be included in the base maturity calculation.
Death and Maturity Benefits in Instalments
All or part of the death or maturity benefit can be taken in instalments over 5, 10 or 15 years. The minimum instalment is ₹5,000 monthly, ₹15,000 quarterly, ₹25,000 half-yearly or ₹50,000 yearly.
The maturity settlement option must be selected at least three months before maturity. If the amount is too small for the chosen minimum instalment, LIC pays it as a lump sum.
Who May Consider to Buy This Plan?
The plan may suit a married couple who wants one joint-life policy, prefers fixed benefits and can pay premiums for a limited period. The premium waiver after the first death can also help the surviving spouse when the policy is in force.
It may not suit someone looking for market-linked returns, easy withdrawals or the highest possible life cover at a low cost. Pure term insurance usually provides more cover for the premium when protection is the main goal.
Frequently Asked Questions
1. What is LIC New Jeevan Sathi Plan 889?
It is a joint-life limited-premium endowment plan for a married individual and spouse. It provides death cover, Guaranteed Additions and a maturity benefit under one policy.
2. How is the maturity benefit calculated?
For an in-force policy, maturity benefit is the Basic Sum Assured plus accrued Guaranteed Additions when at least one spouse survives to maturity.
3. What happens after the first death?
LIC pays the Sum Assured on Death and the policy continues for the surviving spouse. When the policy is in force, future base premiums are waived from the policy anniversary following the first death.
4. Can Plan 889 become a paid-up policy?
Yes. If at least one full-year premium has been paid and later premiums are missed, the policy can continue with reduced paid-up benefits after completion of the first policy year.
5. Is the calculator result official?
No. It provides an estimate for understanding the policy. LIC’s quotation, underwriting decision, benefit illustration and policy schedule determine the final premium and benefits.
Tax Rule
LIC’s current official illustration shows GST as exempt. Tax rules can change, so any tax applicable on the payment date will be charged according to the prevailing law. A tax adviser should be consulted for personal income-tax questions.
Conclusion
LIC New Jeevan Sathi Plan 889 Calculator explains how the ages of both spouses, death benefit option, Basic Sum Assured, policy term and premium-paying term affect the estimated premium and benefits. It also shows how Guaranteed Additions build during and after the premium-paying term.
The most useful results are the premium, Sum Assured on Death, Guaranteed Additions, maturity benefit and premium waiver. Paid-up, surrender and loan figures should be treated as estimates and checked against LIC’s official documents before making a decision.