LIC Jeevan Saathi Plus Plan 197 Calculator
Unit Linked Insurance Plan for Couples
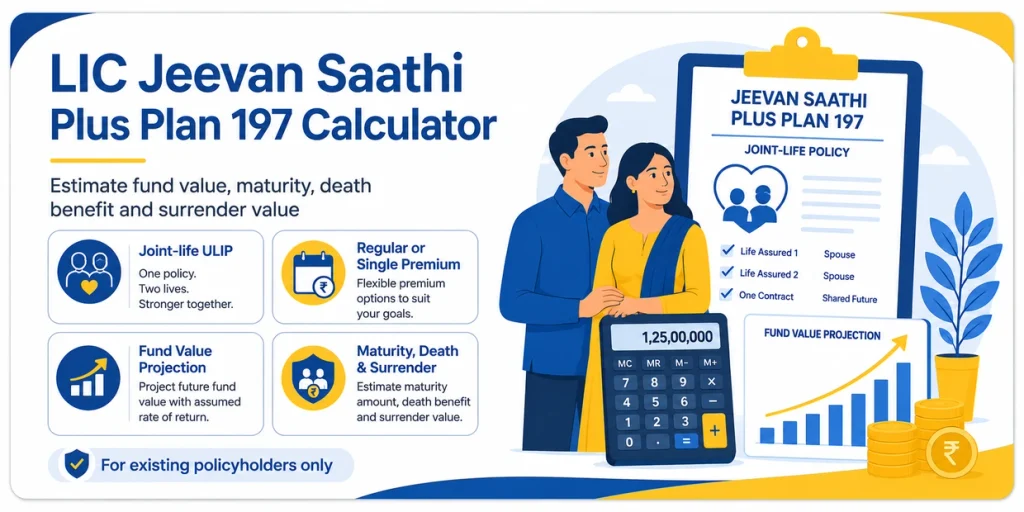
LIC Jeevan Saathi Plus Plan 197 is an old joint-life ULIP for married couples. The plan has been withdrawn, so it is not available for new purchase. However, existing policyholders may still need to check the estimated fund value, maturity benefit, surrender value or death benefit.
The LIC Jeevan Saathi Plus Plan 197 Calculator makes these calculations easier. It uses the policy details entered by the user and shows an estimate based on the selected UIN, premium, fund, charges and assumed return.
What Is the LIC Jeevan Saathi Plus Plan 197 Calculator?
This calculator is made for existing holders of LIC Jeevan Saathi Plus Plan 197. The policy covers two people under one contract:
- Principal Life Assured
- Spouse Life Assured
Part of the premium is invested in a selected fund after policy charges are deducted. The value of this investment changes with the NAV. Therefore, the maturity value is not fixed in advance.
The calculator can estimate:
- Total premiums paid;
- Amount invested after allocation charges;
- Projected fund and maturity value;
- Benefits under different death situations;
- Surrender value; and
- Effect of top-ups or partial withdrawals.
Also Check:
- New Jeevan Sathi Plan 889 Calculator
- New Jeevan Sathi Plan 888 Calculator
- Jeevan Saathi Plan 89 Maturity Calculator
- LIC Jeevan Sathi Calculator
Calculator Highlights
- Supports regular-premium and single-premium policies.
- Covers both lives insured under the policy.
- Uses charges according to the selected UIN version.
- Includes Bond, Secured, Balanced and Growth funds.
- Shows maturity, death and surrender estimates separately.
- Provides a year-wise fund projection.
- Clearly separates estimated values from official LIC values.
Select the Correct UIN Version
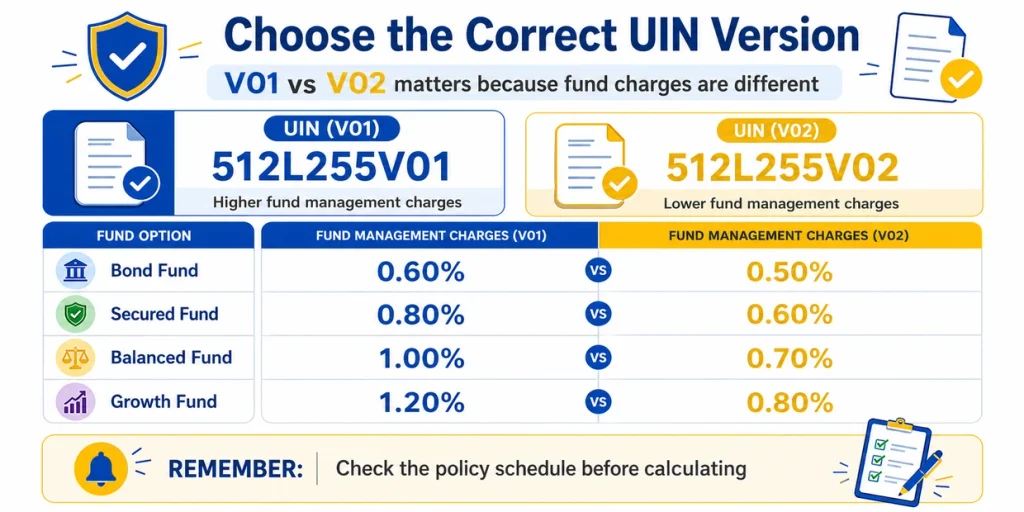
Plan 197 was issued under two UIN versions:
- 512L255V01
- 512L255V02
The UIN on the policy schedule. It must be selected correctly because the Fund Management Charges are different.
| Fund | V01 charge per year | V02 charge per year |
|---|---|---|
| Bond Fund | 0.60% | 0.50% |
| Secured Fund | 0.80% | 0.60% |
| Balanced Fund | 1.00% | 0.70% |
| Growth Fund | 1.20% | 0.80% |
Details Required for Calculation
Keep the policy schedule or latest statement ready. Enter:
- UIN version;
- Regular or single premium;
- Premium amount and payment mode;
- Policy term;
- Ages of both lives;
- Sum Assured for each life;
- Selected fund;
- Expected gross annual return before Fund Management Charge;
- Top-up premiums, if any; and
- Partial withdrawals, if any.
For a current-value estimate, the latest number of units and NAV will give a more useful result than an assumed return.
How to Use the Calculator
- Select the UIN shown on the policy schedule.
- Choose regular premium or single premium.
- Enter the policy term, premium and payment mode.
- Enter the ages and Sum Assured amounts for both lives.
- Select the policy fund.
- Enter the expected gross return for a projection.
- Add top-ups and withdrawals only if they apply to the policy.
- Press Calculate to see the results.
Check the result summary first. The year-wise table can then be used to understand how premiums and charges may affect the fund over time.
Formula Used in the Calculator
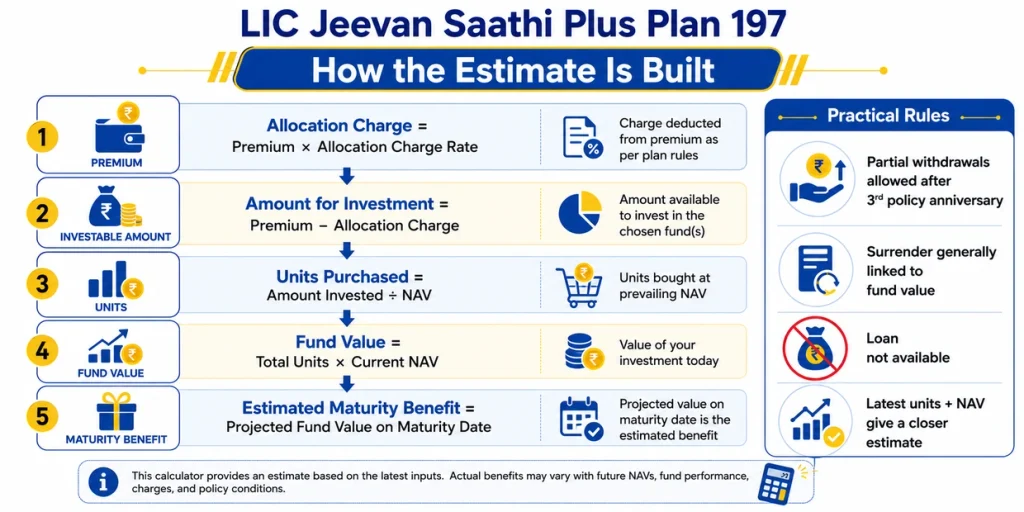
The calculator uses these basic formulas:
Allocation Charge = Premium x Allocation Charge Rate

Amount Available for Investment = Premium - Allocation Charge

Units Purchased = Amount Invested / Applicable NAV

Fund Value = Total Units x Current NAV

Estimated Maturity Benefit = Projected Fund Value on Maturity Date
Mortality, policy administration, premium-waiver and other applicable charges are normally collected by cancelling units. A simple monthly mortality-charge formula is:
Monthly Mortality Charge =
Sum at Risk x Mortality Rate / 1,000 / 12
For the Principal Life Assured, the Sum at Risk also considers unpaid future premiums. For the spouse, it is generally based on the Spouse Sum Assured. The actual mortality rate depends on age and LIC’s policy records.
Calculation Example
Assume a V02 regular-premium policy has an annual premium of Rs. 60,000. The first-year allocation charge for this premium band is 29%.
First-year allocation charge:
Rs. 60,000 x 29% = Rs. 17,400

Amount available before other charges:
Rs. 60,000 - Rs. 17,400 = Rs. 42,600
If the Balanced Fund is selected under V02, its Fund Management Charge is 0.70% per year. Mortality and policy administration charges are also deducted. The remaining amount buys units at the applicable NAV.
This example explains premium allocation only. An exact maturity value cannot be calculated from the premium alone because future NAV, returns, charges and policy transactions are not known.
Understanding the Calculator Results
Maturity Benefit
If either or both insured lives survive until maturity, the policyholder’s fund value is paid:
Maturity Benefit = Policyholder's Fund Value on the Maturity DateThe amount is not guaranteed because it depends on units, NAV and charges.
Death Benefit
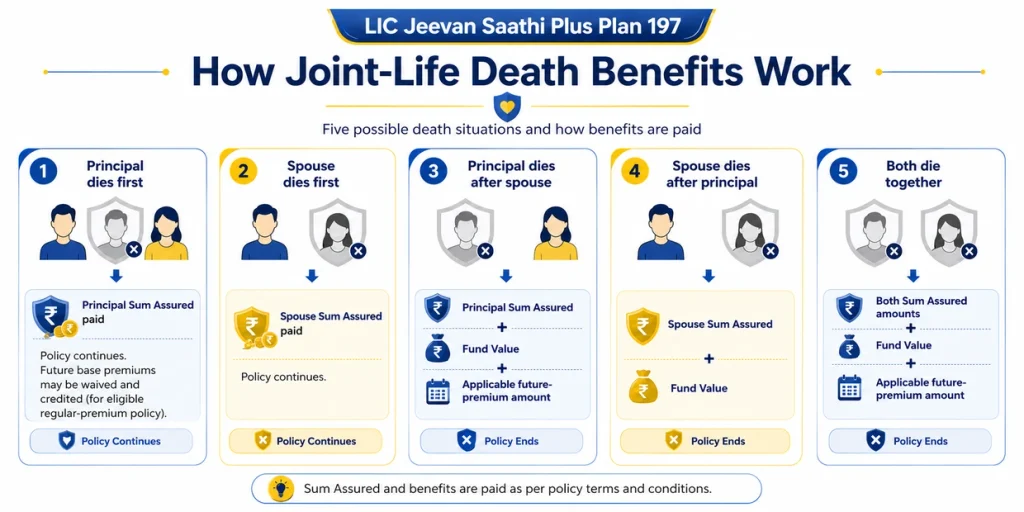
The benefit depends on which insured person dies first.
| Situation | Main benefit pattern |
| Principal Life Assured dies while spouse is alive | Principal Sum Assured is paid and the policy continues. Under an eligible regular-premium policy, future base premiums are waived and credited according to policy conditions. |
| Spouse dies while principal life is alive | Spouse Sum Assured is paid and the policy continues. |
| Principal life dies after the spouse | Principal Sum Assured, fund value and applicable future-premium amount are paid. The policy ends. |
| Spouse dies after the principal life | Spouse Sum Assured and fund value are paid. The policy ends. |
| Both die at the same time | Both Sum Assured amounts, fund value and applicable future-premium amount are paid. The policy ends. |
The final claim is decided by LIC after checking the policy status and claim documents.
Surrender Value and Partial Withdrawals
The surrender value is generally based on the policyholder’s fund value. If surrender is requested before the third policy anniversary, payment is made only after the required three-year period under the policy conditions. The V02 policy document does not list a surrender charge.
Partial withdrawals are allowed after the third policy anniversary, subject to the required minimum balance and other conditions. A withdrawal reduces the remaining units and future fund value.
Charges Included in the Estimate
The calculator may use:
- Premium allocation charge;
- Fund Management Charge;
- Mortality charge for both lives;
- Premium-waiver benefit charge for an eligible regular-premium policy;
- Policy administration charge;
- Top-up allocation charge; and
- Tax on charges, such as service tax or GST, as applicable for the relevant period.
Charges vary by policy year, age, premium type and UIN. The official policy schedule should be used wherever an actual figure is available.
Important Calculator Limitations
The result is only an estimate. It may differ from LIC’s amount because the calculator may not have the exact daily NAV, units, mortality rates, premium dates, switches, missed premiums, revivals, top-ups or withdrawals.
For a final maturity, surrender or death-claim amount, check the latest LIC statement or contact an LIC branch.
Frequently Asked Questions
Is LIC Jeevan Saathi Plus Plan 197 still available?
No. It is a withdrawn plan and cannot be purchased as a new policy.
Which UIN should be selected?
Select 512L255V01 or 512L255V02 exactly as printed on the policy schedule. The charges are not the same for both versions.
Is the maturity amount guaranteed?
No. The maturity benefit is the policyholder’s fund value, which depends on units, NAV, market performance and charges.
Can the calculator show the exact surrender value?
It can provide an estimate. The latest units and NAV are needed for a closer result, while LIC records decide the final payable value.
Is a loan available under Plan 197?
No. A policy loan is not available under LIC Jeevan Saathi Plus Plan 197.
Conclusion
The LIC Jeevan Saathi Plus Plan 197 Calculator helps existing policyholders understand an old joint-life ULIP without working through every charge manually. Selecting the correct UIN is important because V01 and V02 use different Fund Management Charges.
The calculator can provide a useful estimate of fund value, maturity, surrender and death benefits. Final amounts must still be checked from the policy statement and official LIC records.