LIC Amulya Jeevan Calculator Plans Plans 823, 190 and 177
Compare premium and protection details for Plans 823, 190 and 177
Enter Policy Details
Optional Underwriting Addition
Only brochure-supported specimen age and term combinations are used. Missing rates are not estimated or interpolated.
Calculation Result
| Selected Plan | – |
|---|---|
| Age / Term | – |
| Sum Assured | – |
| Premium Mode | – |
| Rate per ₹1,000 | – |
| Base Tabular Premium | – |
| Mode Loading | – |
| Large Cover Rebate | – |
| Underwriting Addition | – |
| Tax | – |
| Premium per Instalment | – |
| Annual Premium Outgo | – |
| Total Estimated Outgo | – |
Policy Benefits
| Death Benefit | – |
|---|---|
| Maturity Benefit | Nil |
| Paid-up Value | Nil |
| Surrender Value | Nil |
| Loan Facility | Not available |
| Cover-ending Age | – |
| Estimated End Date | Not selected |
Important Notes
LIC Amulya Jeevan is a term insurance policy made for people who needed a high amount of life cover. LIC issued three versions of this policy, commonly known as Amulya Jeevan Plan 177, Amulya Jeevan-I Plan 190 and Amulya Jeevan-II Plan 823. All three have been withdrawn and cannot be purchased now.
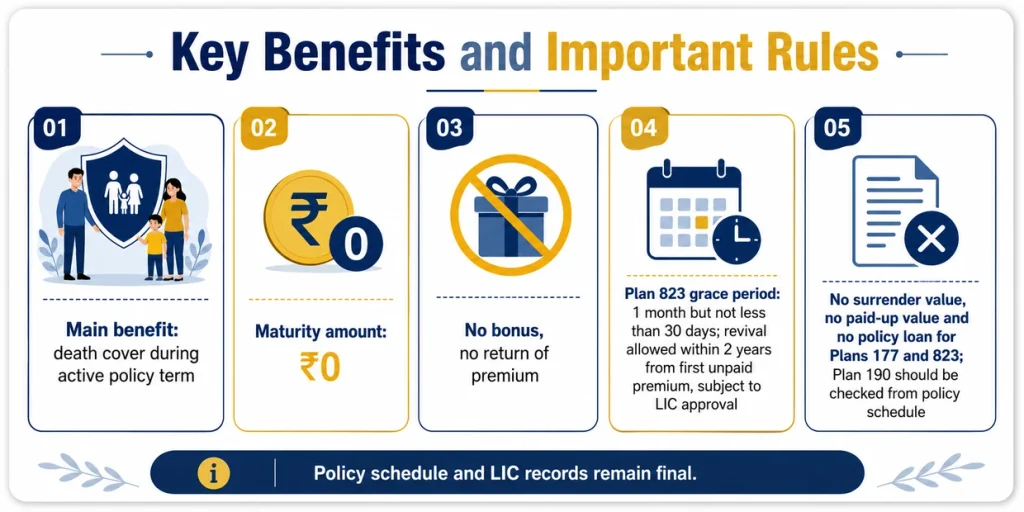
These plans were made for protection, not savings. If the insured person died while an active policy was running and the claim was accepted, LIC paid the applicable death benefit. If the insured person survived the full policy term, no maturity amount was paid and the premiums were not returned.
Table of Contents
What Is the LIC Amulya Jeevan Calculator?
The LIC Amulya Jeevan Calculator is an online tool for checking old Plans 177, 190 and 823. After a plan is selected, it uses the entered age, policy term, Sum Assured, payment frequency and available premium rate to estimate the basic premium. It can also show the total basic premiums paid, remaining payments, policy end date, death cover and maturity value of ₹0.
The calculator is useful for understanding an existing policy or checking an old premium illustration. It cannot be used to buy a new Amulya Jeevan policy. Its result is only an estimate because the issued policy schedule and LIC records remain final.
Plans Included in the Calculator
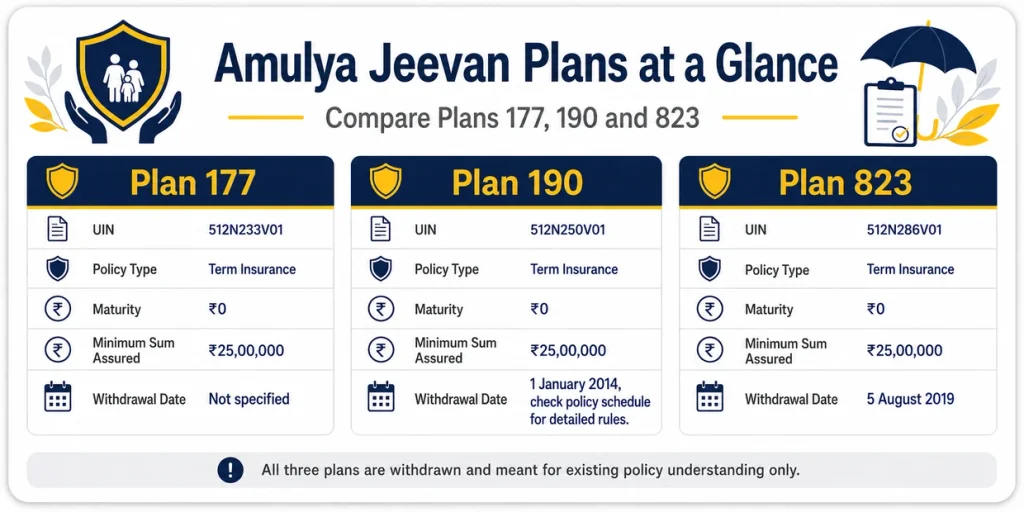
| Policy version | Common plan number | UIN | Confirmed withdrawal date |
|---|---|---|---|
| LIC Amulya Jeevan | 177* | 512N233V01 | Not specified in the available LIC brochure |
| LIC Amulya Jeevan-I | 190 | 512N250V01 | 1 January 2014 |
| LIC Amulya Jeevan-II | 823 | 512N286V01 | 5 August 2019 |
*The original Amulya Jeevan is commonly identified as Plan 177. However, the available LIC brochure and the current withdrawn-plan list show its name and UIN without displaying a plan number. The number printed in the issued policy schedule should be treated as final.
Amulya Jeevan Plans Comparison
| Comparison | Amulya Jeevan | Plan 190 | Plan 823 |
| Policy type | Term insurance | Term insurance | Term insurance |
| Main benefit | Death cover | Death cover | Death cover |
| Maturity amount | ₹0 | ₹0 | ₹0 |
| Bonus | No | No | No |
| Premium choices | Yearly, half-yearly or single premium | Check policy schedule | Yearly or half-yearly |
| Minimum Sum Assured | ₹25,00,000 | Check policy schedule | ₹25,00,000 |
| New purchase available | No | No | No |
The three versions served the same main purpose, but their premium rates, age limits, policy terms and other rules were not always the same. The plan number and UIN should be checked before any calculation is made.
How to Use the LIC Amulya Jeevan Calculator
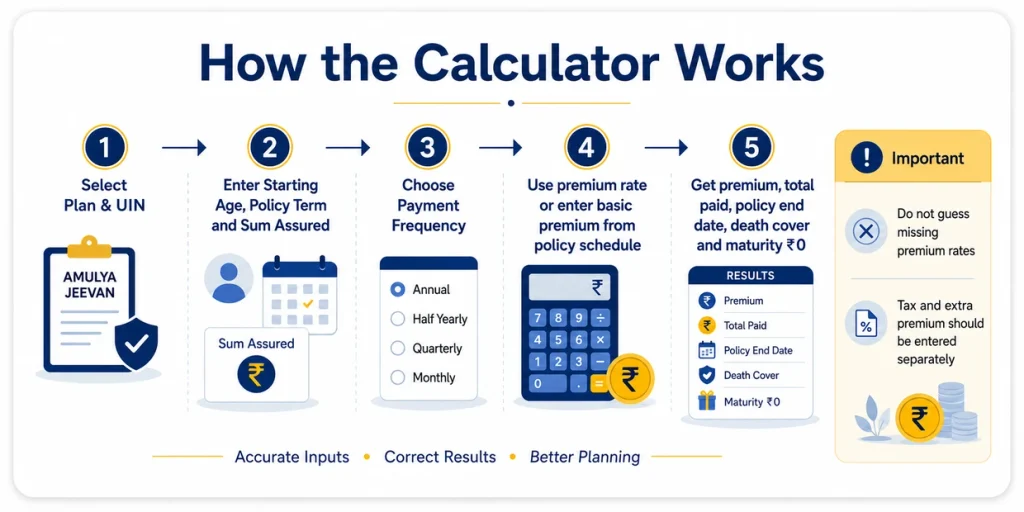
First, select the plan shown in the policy schedule and check that its UIN matches. Then enter the age when the policy started, policy term and Sum Assured. Select the payment frequency available under that version. A single-premium option should be used only when it appears in the issued policy.
The calculator can use a premium rate only when the selected age and term are available in its supported rate table. If a rate is unavailable, the calculator should not guess a value between two rates. In that case, the basic premium shown in the policy schedule should be entered directly.
Tax and any extra premium charged by LIC can be entered separately when these amounts are known. The policy start date can also be added to estimate the end date. After pressing Calculate, the result should show the premium for each payment, estimated yearly cost, total basic premiums, death cover and maturity value. Reset clears all entered details.
Formula Used in the Calculator
Basic Premium
LIC’s sample premium rates are normally shown for every ₹1,000 of Sum Assured.
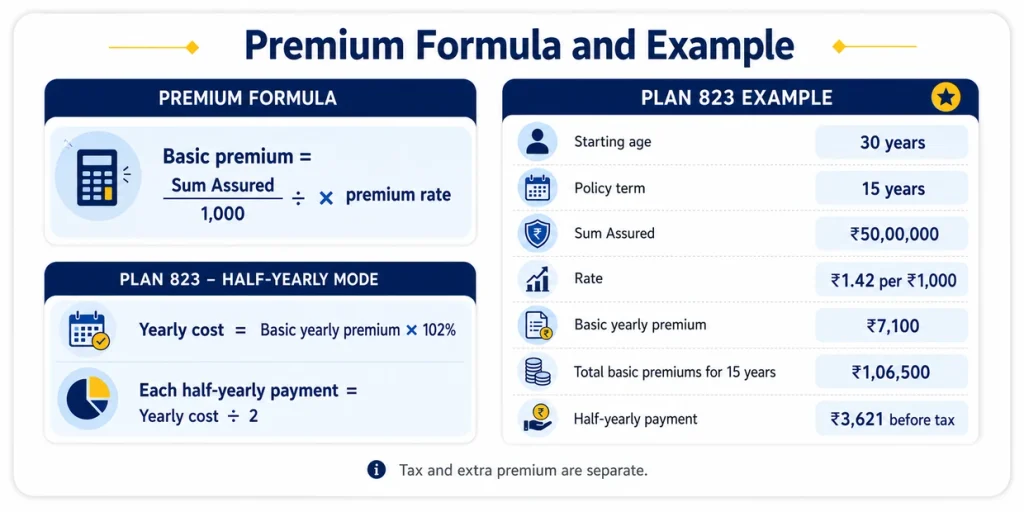
Basic premium = Sum Assured ÷ 1,000 × applicable premium rateThe correct rate depends on the selected policy version, starting age, policy term and payment frequency.
Half-Yearly Premium for Plan 823
Plan 823 charged an additional 2% of the basic yearly premium when payments were made every six months.
Yearly cost in half-yearly mode = Basic yearly premium × 102%

Each half-yearly payment = Yearly cost ÷ 2
This rule should not be applied automatically to Plans 177 or 190 unless their policy documents support it.
Total Basic Premiums Paid
Total basic premiums paid =
Basic premium for each payment × number of payments made
Tax and extra charges should be kept separate from the basic premium.
Remaining Premium Payments
Remaining payments = Total scheduled payments − payments already madeEstimated Policy End Date
Estimated policy end date = Policy start date + policy termThe date printed in the policy schedule remains final.
Death and Maturity Benefits
For a policy that provides the selected Sum Assured as its normal death benefit:
Estimated normal death benefit = Sum Assured

Normal maturity benefit = ₹0
The death-cover estimate applies only when the policy is active and the claim meets its conditions.
Real Calculation Example
Consider an Amulya Jeevan-II Plan 823 policy with the following details:
| Policy detail | Example value |
| Starting age | 30 years |
| Policy term | 15 years |
| Sum Assured | ₹50,00,000 |
| Payment frequency | Yearly |
| Published sample rate | ₹1.42 per ₹1,000 |
First, divide the Sum Assured into units of ₹1,000:
₹50,00,000 ÷ ₹1,000 = 5,000 unitsNow apply the published rate:
Basic yearly premium = 5,000 × ₹1.42
                     = ₹7,100 before tax
If the same basic premium was paid for all 15 years:
Total basic premiums = ₹7,100 × 15
                     = ₹1,06,500
The normal death cover during an active policy term would be ₹50,00,000, subject to the policy conditions and LIC accepting the claim. If the insured person survived the full 15-year term, the maturity amount would be ₹0.
For half-yearly payment under Plan 823:
Yearly cost = ₹7,100 × 102% = ₹7,242

Each half-yearly payment = ₹7,242 ÷ 2
                         = ₹3,621 before tax
The total premiums are the cost of life cover. They are not returned when the policy ends. This example does not include tax or any extra premium charged because of health, occupation or another risk.
What Was LIC Amulya Jeevan?
LIC Amulya Jeevan was designed to provide a high amount of life cover at a premium based on age, policy term, Sum Assured and payment frequency. It did not build a savings fund, earn bonuses or provide money-back payments.
The original Amulya Jeevan under UIN 512N233V01 allowed yearly, half-yearly and single-premium payments. Its policy term ranged from 5 to 25 years, and its minimum Sum Assured was ₹25,00,000.
Plan 190 was the next version under UIN 512N250V01. The currently available LIC page confirms its identity and withdrawal date but does not provide a policy document. Its detailed rules should therefore be checked from the issued policy schedule.
Plan 823 was the later version. It allowed yearly or half-yearly payments, a policy term of 5 to 35 years and a minimum Sum Assured of ₹25,00,000. The maximum Sum Assured was not fixed, but LIC’s approval depended on the applicant’s income, health, occupation and existing insurance.
Death and Maturity Benefits
The main benefit was the death cover. If the insured person died during an active policy term, the applicable Sum Assured could be paid after LIC checked the policy status, premium record, claim documents and policy conditions.
No normal payment was made when the insured person survived until the end of the term. Amulya Jeevan did not provide a bonus, Guaranteed Addition, survival payment or return of premium.
A calculator can show the expected cover, but it cannot approve a claim. An unpaid premium, lapsed policy or special claim condition can affect the amount payable.
Premium Payment and Total Premiums Paid
The payment choices depend on the selected policy version. Plan 823 accepted yearly and half-yearly payments. The original policy also offered a single-premium option. Plan 190 payment details should be taken from its schedule.
The calculator should show the basic premium separately from tax and extra charges. This makes it easier to compare the result with the policy receipt. A total premium figure should not be described as an investment or maturity value because the money paid for insurance protection during the covered years.
Missed Premium, Policy Lapse and Revival
A grace period is a short extra period allowed after a premium due date. Under Plan 823, yearly and half-yearly premiums had a grace period of one month, but not less than 30 days. If death happened during this period, the policy could remain valid, but unpaid premiums could be deducted from an accepted claim.
If a required premium remained unpaid after the grace period, the policy could lapse and the full death cover should not be assumed. Plan 823 allowed an application for revival within two continuous years from the first unpaid premium and before the policy ended. LIC could ask for unpaid premiums with interest and updated health information. Cover returned only after LIC approved the revival.
The grace and revival rules for Plans 177 and 190 should be checked from their own policy documents.
Surrender Value, Paid-Up Value and Loan
Plan 823 did not provide a surrender value, reduced paid-up benefit or policy loan. The original Amulya Jeevan brochure also states that it did not provide these benefits.
The same result should not be copied automatically to Plan 190 without checking its issued policy. No surrender, paid-up or loan value should be shown unless the exact policy document supports it.
Tax Rule
Tax benefits depend on the policy details and the tax law that applies. The calculator does not decide whether a premium deduction or claim exemption is available. Current tax rules should be checked before making a tax claim.
Important Points for Existing Policyholders
The plan number, UIN, Sum Assured, policy term, payment frequency and current status should be checked from the policy schedule and premium receipts. The policy may be active, within the grace period, lapsed, revived or already completed.
Special rules can apply to some death claims, including death by suicide within the period stated in the policy. These rules differ between versions and may also apply after revival. The calculator should not show the full Sum Assured automatically in such cases.
LIC’s premium and policy records are the final source for an old policy. The calculator provides historical estimates and does not replace an LIC quotation or claim decision.
Frequently Asked Questions
Is LIC Amulya Jeevan still available for purchase?
No. All three versions have been withdrawn. Existing policies can continue according to their original conditions, but a new Amulya Jeevan policy cannot be purchased.
Does LIC Amulya Jeevan provide a maturity benefit?
No. The normal maturity benefit is ₹0 when the insured person survives the full policy term.
Are the premiums returned when the policy ends?
No. Amulya Jeevan is not a return-of-premium plan. The premiums pay for life cover during the policy term.
What happens if an Amulya Jeevan policy lapses?
Full death cover should not be assumed after the policy lapses. Revival may be possible under the rules of the selected version, but cover returns only after LIC approves it.
Can the calculator show an exact premium for every age and term?
No. An exact estimate is possible only when the required premium rate is available. If it is missing, the basic premium printed in the policy schedule should be used instead of guessing a rate.
Conclusion
The LIC Amulya Jeevan Calculator helps existing policyholders understand old Plans 177, 190 and 823. It can estimate the basic premium, total premiums paid, remaining payments, policy dates, death cover and maturity value of ₹0.
The correct policy version must be identified before calculating any amount because the three plans do not have exactly the same rules. The policy schedule and LIC records remain final for premiums, policy status and claim benefits.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.