LIC New Bima Kiran Plan 150 Calculator
Optional Policy Details
Premium Details
| Premium Calculation | |
|---|---|
| Tabular rate / ₹1,000 SA | - |
| Base annual tabular premium | - |
| High Sum Assured rebate | - |
| Additional rebate above ₹5 lakh | - |
| Mode rebate | - |
| Estimated modal premium | - |
| Estimated annual outgo | - |
| Total premiums over full term | - |
Benefit Details
| Policy Benefits | |
|---|---|
| Premium return at maturity | - |
| Declared Loyalty Addition used | - |
| Estimated maturity total | - |
| Death benefit | - |
| Extended cover percentage | - |
| Extended cover for 10 years | - |
| In-built accident benefit | Up to ₹5,00,000 |
Surrender & Other Details
| Surrender Estimate | |
|---|---|
| Premiums paid | - |
| Notional paid-up value | - |
| Guaranteed Surrender Value | - |
| Special Surrender Value | Not calculated - LIC factor required |
| Policy loan | Not available |
LIC New Bima Kiran is a premium-back term assurance plan from Life Insurance Corporation of India. It provided life insurance during the policy term and returned eligible premiums when the Life Assured survived until maturity. The plan also offered reduced life cover for another 10 years after maturity.
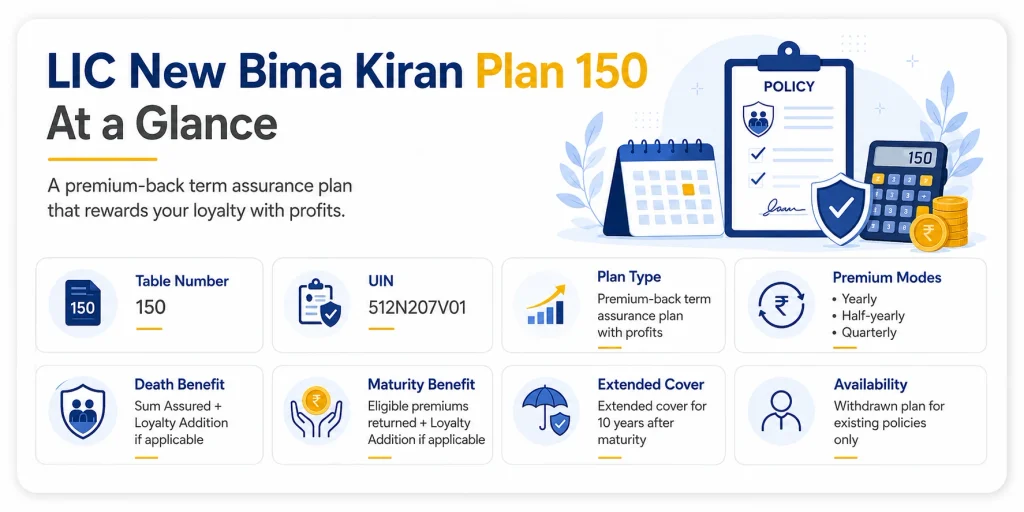
The plan contains Table No. 150 and UIN 512N207V01. It has been withdrawn and cannot be purchased now. However, old policyholders may still need to understand the premium return, death benefit, Loyalty Addition, extended cover or surrender value. The LIC New Bima Kiran Plan 150 Calculator makes calculations easy; compare all benefits in one place.
What Is the LIC New Bima Kiran Plan 150 Calculator?
The calculator is designed specifically for New Bima Kiran Plan 150. It uses the Life Assured’s age at entry, Basic Sum Assured, policy term, premium mode and premium details to estimate the main policy values.
It can show the estimated premium, total premiums payable, maturity premium return, death benefit, Loyalty Addition, extended life cover and Guaranteed Surrender Value.
New Bima Kiran was different from a normal endowment plan. The full Basic Sum Assured was mainly the life cover during the policy term. At maturity, the plan returned eligible premiums rather than paying the Basic Sum Assured as the maturity amount.
If the calculator contains a complete and authenticated Plan 150 premium table, it can estimate the original premium from age, term and Sum Assured. Otherwise, the premium printed on the policy schedule should be entered directly.
LIC New Bima Kiran Plan 150 Overview
| Particular | Plan details |
|---|---|
| Plan name | LIC New Bima Kiran |
| Table number | 150 |
| UIN | 512N207V01 |
| Plan type | Premium-back term assurance plan with profits |
| Premium payment | Throughout the policy term |
| Premium modes | Yearly, half-yearly and quarterly |
| Death benefit | Sum Assured plus Loyalty Addition, if applicable |
| Maturity benefit | Eligible premiums returned plus Loyalty Addition, if applicable |
| Extended cover | Reduced life cover for 10 years after maturity |
| Surrender | Available after the policy remained in force for at least three years |
| Current availability | Withdrawn; not open for new purchase |
These are historical plan details for understanding existing policies. They should not be treated as current LIC purchase conditions.
What Was LIC New Bima Kiran?
New Bima Kiran combined term insurance with a return-of-premium feature. If the Life Assured died during the policy term, the death benefit became payable. If the Life Assured completed the policy term, LIC returned the eligible premiums paid and added Loyalty Addition when applicable.
The policy also had a special extended-cover feature. After maturity, a percentage of the original Sum Assured continued as life cover for another 10 years without further premiums. The extended period did not include the accident benefit.
Because the plan participated in LIC’s profits, an eligible policy could receive Loyalty Addition. This amount was not fixed or guaranteed in advance.
Also Check:
Calculator Highlights
The calculator checks the selected policy term and premium mode before showing the result. It keeps the Sum Assured, maturity premium return and Loyalty Addition separate so that the maturity amount is not confused with the life cover.
It also applies the correct extended-cover percentage according to the original policy term. For surrender calculations, it excludes the complete first-year basic premium as required by the Guaranteed Surrender Value formula.
Loyalty Addition is not calculated as a rate per ₹1,000 Sum Assured. Plan 150 used declared percentages of eligible premiums paid. Therefore, the calculator should accept a confirmed Loyalty Addition percentage or confirmed rupee amount rather than assume one fixed rate for every policy.
How to Use New Bima Kiran Plan 150 Calculator?
Enter the age at entry, Basic Sum Assured, policy term and premium mode. If the calculator has the complete historical premium table, it can estimate the premium. For an existing policy, entering the premium shown on the policy schedule gives a more reliable result.
For maturity calculations, enter the total eligible premiums actually paid. For quarterly or half-yearly policies, enter the instalment premium and the total number of instalments paid correctly.
If LIC has confirmed a Loyalty Addition percentage or amount, enter it in the optional field. Leave the field blank when it is unknown. For a surrender estimate, enter the total basic premiums paid and the complete first-year basic premium.
After entering the details, click Calculate. The calculator should display the main result first and show the premium, benefit and surrender calculations in separate sections. Use Reset to clear all fields.
Formulas Used in New Bima Kiran Calculator
Premium Calculation
Historical Plan 150 premium tables provided rates per ₹1,000 of Basic Sum Assured. When the correct rate is available, the starting formula is:
Tabular Premium =
(Basic Sum Assured ÷ 1,000) × Applicable Premium Rate
Any valid Sum Assured rebate or premium-mode adjustment should be applied only when it is supported by the original LIC table used by the calculator. Extra premium charged because of health, occupation or another risk should be shown separately.
Total Premiums Paid
The safest formula for all premium modes is:
Total Premiums Paid =
Instalment Premium × Total Instalments Paid| Premium mode | Instalments in one year |
| Yearly | 1 |
| Half-yearly | 2 |
| Quarterly | 4 |
For example, a half-yearly policy that continued for 20 years normally has 40 premium instalments. The calculator should not treat 20 policy years as 20 half-yearly instalments.
Maturity Benefit
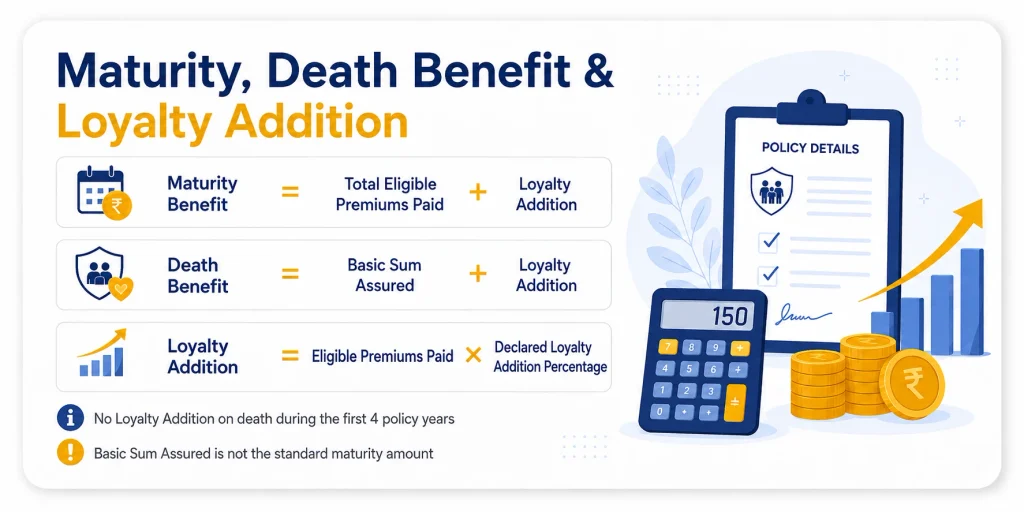
When the Life Assured survived the policy term, the maturity benefit was:
Maturity Benefit =
Total Eligible Premiums Paid
+ Loyalty Addition, if applicable
The premium return included accident-benefit premium but excluded other extra premiums. It did not include the Basic Sum Assured.
For an old policy, the actual premium-payment record should be used instead of multiplying a rounded annual estimate by the policy term.
Loyalty Addition
New Bima Kiran participated in LIC’s profits. Loyalty Addition could be paid with an eligible death or maturity claim, but it depended on LIC’s declaration, policy term and completed duration.
Plan 150’s Loyalty Addition was declared as a percentage of eligible premiums paid. It was not calculated per ₹1,000 of Basic Sum Assured.
Loyalty Addition =
Eligible Premiums Paid × Declared Loyalty Addition Percentage
No Loyalty Addition was payable when death occurred during the first four policy years.
An assumed percentage may be used to explain the formula, but the result must be marked as an illustration. The actual percentage for a claim should be checked from LIC’s applicable declaration and policy records.
Death Benefit
If the Life Assured died during the policy term, the basic calculation was:
Death Benefit =
Basic Sum Assured
+ Loyalty Addition, if applicable
The Sum Assured was payable as a lump sum. Loyalty Addition could be included only when the policy qualified for it under LIC’s declared terms.
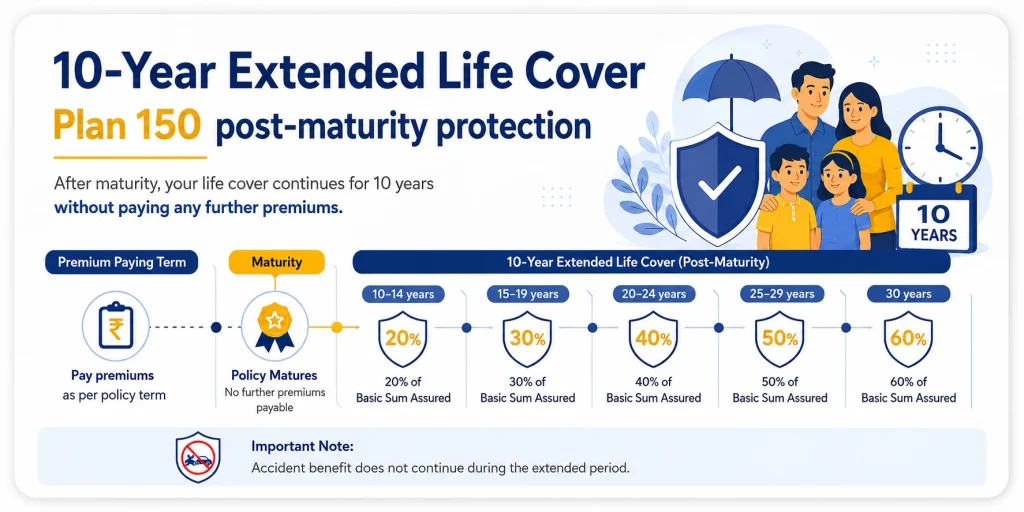
Extended Life Cover
When the Life Assured survived the original policy term, reduced death cover continued for another 10 years. No further premium was required for this extended period.
| Original policy term | Extended death cover |
| 10–14 years | 20% of Basic Sum Assured |
| 15–19 years | 30% of Basic Sum Assured |
| 20–24 years | 40% of Basic Sum Assured |
| 25–29 years | 50% of Basic Sum Assured |
| 30 years | 60% of Basic Sum Assured |
The formula is:
Extended Cover =
Basic Sum Assured × Applicable Percentage
The extended cover applied for 10 years after maturity and did not include the accident benefit.
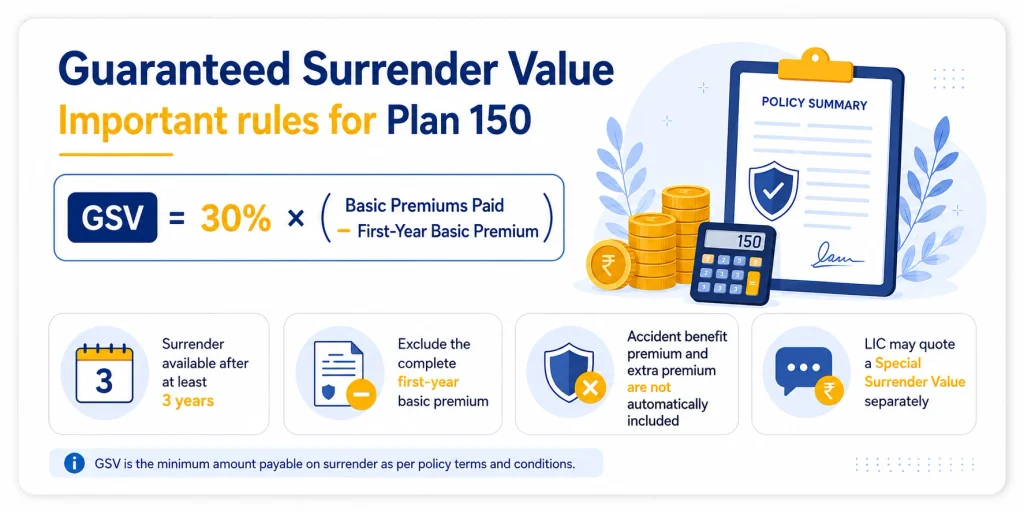
Guaranteed Surrender Value
The policy could be surrendered after it had remained in force for at least three years. The Guaranteed Surrender Value was:
Guaranteed Surrender Value =
30% × (Basic Premiums Paid − First-Year Basic Premium)
The complete first-year basic premium must be excluded. For a quarterly policy, this means all four basic premium instalments for the first policy year, not only one instalment.
The premium base used for GSV is different from the maturity premium return. Accident-benefit premium and extra premium should not automatically be included in the GSV calculation.
LIC could pay a Special Surrender Value that was usually higher than the Guaranteed Surrender Value. However, it depended on LIC’s applicable factors, the policy duration and the number of premiums paid. It should not be calculated without the required factors.
Accident Benefit
New Bima Kiran included accident cover for accidental death and total and permanent disability caused by an accident. The maximum accident cover was ₹5,00,000, subject to the policy conditions.
The premium paid for this accident benefit formed part of the eligible premium return at maturity. However, the accident benefit did not continue during the additional 10-year extended-cover period.
The exact accident claim amount depends on the cover shown in the policy schedule and LIC’s claim conditions.
Calculation Example
| Policy detail | Value |
| Age at entry | 35 years |
| Basic Sum Assured | ₹1,00,000 |
| Policy term | 25 years |
| Premium-paying term | 25 years |
| Premium mode | Yearly |
| Yearly premium | ₹1,542 |
The total premium over 25 years was:
₹1,542 × 25 = ₹38,550Therefore, the guaranteed premium return at maturity was ₹38,550 before any applicable Loyalty Addition.
The death benefit during the policy term was ₹1,00,000 before Loyalty Addition. Because the policy term was 25 years, the extended-cover percentage was 50%:
Extended Cover =
₹1,00,000 × 50%
= ₹50,000
This ₹50,000 life cover continued for 10 years after maturity, subject to the policy conditions and without accident benefit.
LIC Official Illustration Explained
LIC’s historical illustration showed guaranteed and projected amounts separately:
| Maturity component | Scenario 1 | Scenario 2 |
| Guaranteed premium return | ₹38,550 | ₹38,550 |
| Projected variable benefit | ₹0 | ₹46,000 |
| Illustrated maturity amount | ₹38,550 | ₹84,550 |
The ₹46,000 amount was a projected variable benefit based on LIC’s historical 10% assumed investment-return scenario. It was not guaranteed and should not be described as the actual Loyalty Addition of a real policy.
The official illustration helps explain the plan, but an existing policy’s actual Loyalty Addition must be checked from LIC records.
Tax Benefits and Tax Rules
Premiums may have qualified for a tax deduction under the rules and limits applicable when they were paid. Tax treatment of maturity, surrender and death payments depends on the policy details and the law applicable when the benefit is received.
No payment should be described as automatically tax-free without checking the policy and applicable tax rules. Taxes and extra premiums should not be included in calculator formulas unless the policy conditions specifically allow them.
Important Points to Remember
- Plan 150 has been withdrawn and cannot be purchased now.
- Maturity returned eligible premiums; it did not pay the Basic Sum Assured.
- Loyalty Addition was based on eligible premiums paid, not the Sum Assured.
- No Loyalty Addition was payable on death during the first four policy years.
- Accident cover did not continue during the 10-year extended period.
- LIC’s official maturity, surrender and claim amounts should be treated as final.
Frequently Asked Questions
Is LIC New Bima Kiran Plan 150 still available?
No. New Bima Kiran Plan 150 is a withdrawn policy and is not open for new purchase. The calculator is intended for understanding old policies and historical benefits.
What amount was returned at maturity?
LIC returned the total eligible premiums paid, including accident-benefit premium but excluding other extra premiums. Loyalty Addition was also payable when the policy qualified for it.
How was the death benefit calculated?
The death benefit was the Basic Sum Assured plus Loyalty Addition, if applicable. No Loyalty Addition was payable when death occurred during the first four policy years.
How did the 10-year extended cover work?
After maturity, 20% to 60% of the original Basic Sum Assured continued as life cover for another 10 years. The percentage depended on the original policy term. Accident cover was not available during this extended period.
How was the Guaranteed Surrender Value calculated?
After the policy had remained in force for at least three years, GSV was 30% of the basic premiums paid after excluding the complete first-year basic premium. LIC could quote a different Special Surrender Value using its applicable factors.
Conclusion
The LIC New Bima Kiran Plan 150 Calculator can help explain an old policy’s premium return, death benefit, Loyalty Addition, extended cover and surrender value. It also makes clear that the Basic Sum Assured was mainly the life cover and was not the standard maturity payment.
The most reliable calculation uses the actual policy schedule and premium records. Historical premium tables can provide an estimate, but LIC’s declared Loyalty Addition, surrender quotation and claim decision determine the final amount payable.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.