LIC Jeevan Amar Plan 855 Calculator
Premium, death benefit and cover projection calculator
UIN: 512N332V01Enter Policy Details
Minimum ₹25 lakh. Above ₹40 lakh, enter multiples of ₹10 lakh.
For Regular/Limited Premium, enter annual premium before GST. For Single Premium, enter one-time premium before GST.
Available only under Regular and Limited Premium modes.
Rider cover is payable only for accidental death, during the premium paying term or up to age 70, whichever occurs earlier.
Premium & Coverage Illustration
Death Benefit Calculation
Death Cover Projection
| Policy Year | Base Cover | Cover Status |
|---|
LIC Jeevan Amar Plan 855 was a pure term insurance plan. Its main purpose was to provide financial support to the family if the life assured died during the policy term. It was not a savings or investment plan.
The most important point is simple: Plan 855 does not pay a maturity benefit if the life assured survives the full policy term. The premium was paid for life cover, not to build savings.
LIC launched Plan 855 on 5 August 2019 and withdrew it on 22 November 2022. It is not available for a new purchase. The calculator and this article are useful for checking an existing policy or understanding its old benefit rules.
Table of Contents
What is Jeevan Amar Plan 855 Calculator?
The calculator helps explain the premium payment and life-cover structure of an existing Plan 855 policy. It may show:
- Premium payment amount
- Premium Paying Term
- Total planned premium payments
- Age when the policy ends
- Level or Increasing Absolute Cover
- Death-benefit comparison
- Possible Accident Benefit Rider amount
- Maturity benefit of ₹0
For an existing policy, enter the same details shown in the policy schedule. The LIC policy record remains final for the premium, Sum Assured, selected cover option, rider and policy status.
Important calculator limit: The calculator can use the base premium printed in an existing policy, premium receipt or official LIC record. Automatic premium calculation should be used only for exact brochure samples stored in the tool. A few brochure examples cannot be used to calculate every age, term or Sum Assured combination.
Also Check:
- LIC Jeevan Amar Premium Calculator
- LIC Jeevan Amar Plan 955 Calculator
- LIC Term Plan Calculator
- LIC Saral Jeevan Bima Plan 859 Calculator
Does Plan 855 Have a Maturity Benefit?
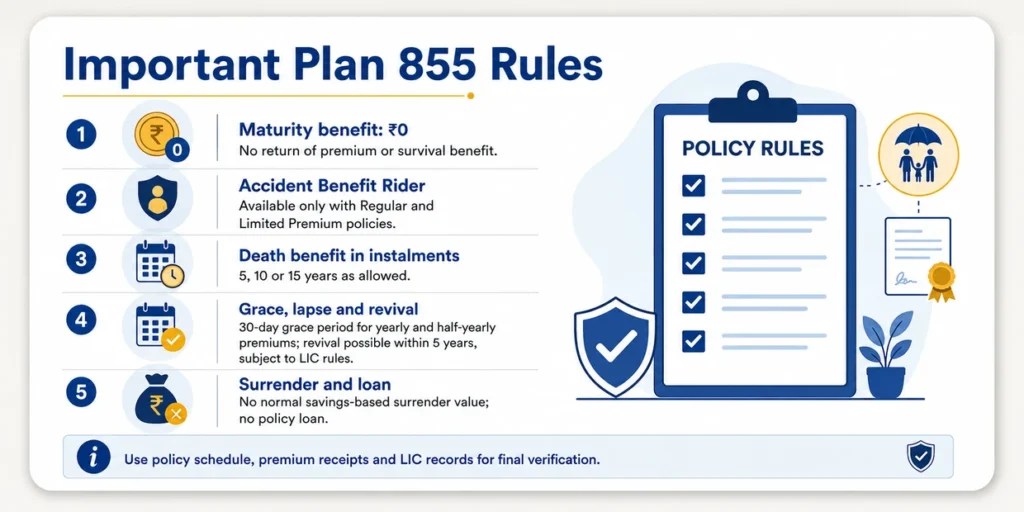
No. LIC Jeevan Amar Plan 855 does not pay any amount only because the life assured survives until the end of the term.
| Item | Result |
|---|---|
| Age when policy ends | Age at entry + policy term |
| Maturity benefit | ₹0 |
| Return of premium | Not available |
| Survival benefit | Not available |
| Bonus or Loyalty Addition | Not available |
The end date is still important because the life cover stops on that date. It should not be treated as a maturity payout date.
What Was LIC Jeevan Amar Plan 855?
LIC Jeevan Amar Plan 855, UIN 512N332V01, was an offline pure term insurance plan. It provided death cover during the policy term and offered two cover options:
- Option I: Level Sum Assured
- Option II: Increasing Sum Assured
The plan also offered Regular, Limited and Single Premium choices. Premium rates depended on factors such as entry age, gender, smoking status, policy term, Premium Paying Term, Sum Assured and cover option.
Non-smoker rates were subject to the plan conditions and a urinary cotinine test. If the required conditions were not met, smoker rates applied. Female lives had separate rates.
LIC Jeevan Amar Plan 855 Quick Facts
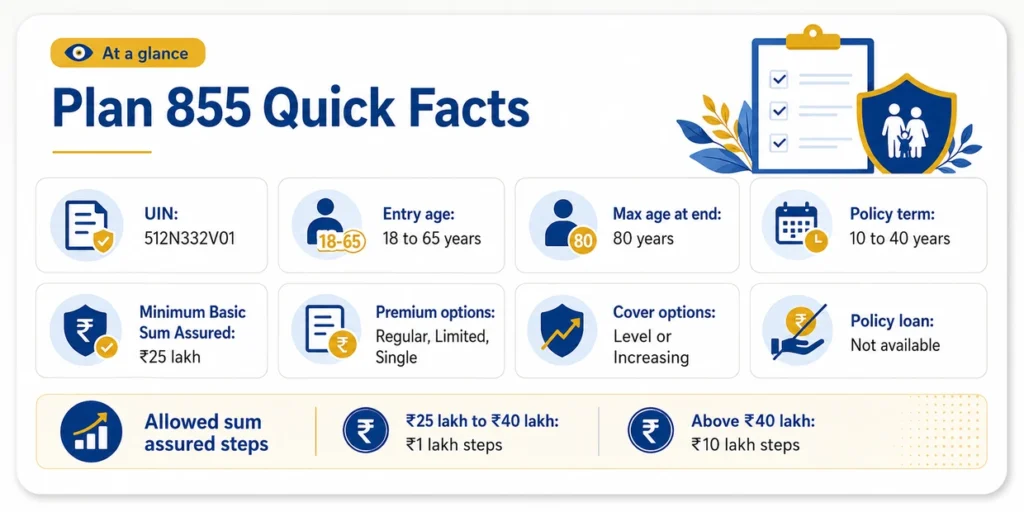
| Feature | Plan details |
| Plan number | 855 |
| UIN | 512N332V01 |
| Plan type | Non-linked, non-participating pure term insurance |
| Launch date | 5 August 2019 |
| Withdrawal date | 22 November 2022 |
| Entry age | 18 to 65 years |
| Maximum age when cover ends | 80 years |
| Policy term | 10 to 40 years |
| Minimum Basic Sum Assured | ₹25 lakh |
| Maximum Basic Sum Assured | No fixed limit, subject to underwriting |
| Cover options | Level or Increasing Sum Assured |
| Premium options | Regular, Limited or Single Premium |
| Maturity benefit | Not payable |
| Policy loan | Not available |
Basic Sum Assured had to be selected in the following steps:
| Basic Sum Assured | Allowed step |
| ₹25 lakh to ₹40 lakh | ₹1 lakh |
| Above ₹40 lakh | ₹10 lakh |
The actual maximum cover was subject to LIC’s underwriting decision.
Eligibility Conditions
The age and term combination had to keep the age at the end of the policy within 80 years.
Age When Policy Ends = Age at Entry + Policy TermFor example, a person who entered at age 45 could select a maximum term of 35 years:
45 + 35 = 80 yearsA 40-year term would end at age 85 and would not meet the plan condition.
Premium Payment Options
| Premium option | How it worked |
| Regular Premium | Premiums were paid for the full policy term |
| Limited Premium: Term − 5 | Premiums were paid for policy term minus five years |
| Limited Premium: Term − 10 | Premiums were paid for policy term minus ten years |
| Single Premium | One premium was paid at the beginning |
The Term − 5 option was available for policy terms from 10 to 40 years. The Term − 10 option was available for policy terms from 15 to 40 years.
Regular and Limited Premium policies allowed yearly or half-yearly payments. Monthly and quarterly modes were not available for paying policy premiums.
The historical brochure listed a minimum premium of ₹3,000 for Regular and Limited Premium policies and ₹30,000 for Single Premium policies. These amounts excluded applicable government taxes.
Level and Increasing Sum Assured
Option I: Level Sum Assured
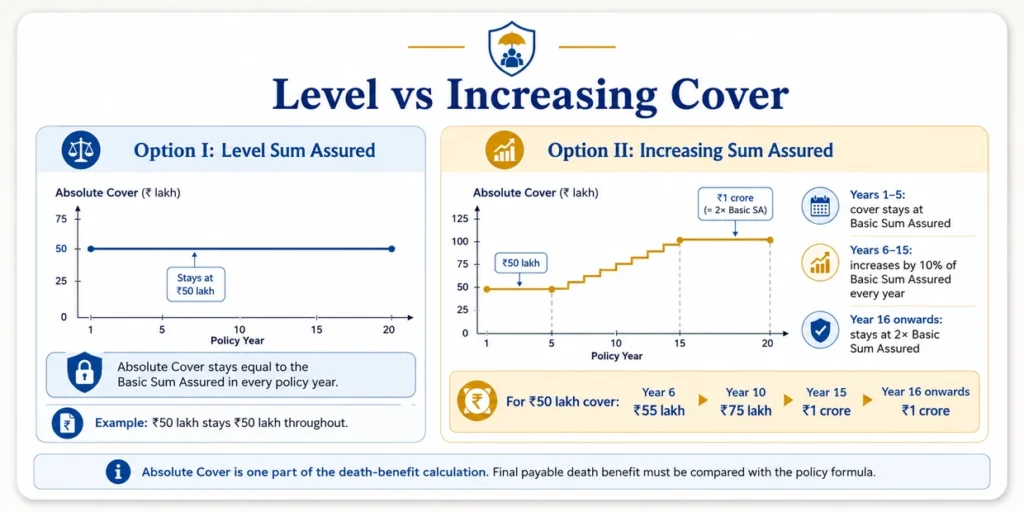
Under this option, the Absolute Amount Assured to Be Paid on Death remained equal to the Basic Sum Assured throughout the policy term.
For a ₹50 lakh Basic Sum Assured policy:
Absolute Cover = ₹50 lakh in every policy yearOption II: Increasing Sum Assured
Under this option, the Absolute Cover remained equal to the Basic Sum Assured for the first five policy years. It then increased by 10% of the Basic Sum Assured each year from the sixth to the fifteenth policy year. From the sixteenth year, it remained at twice the Basic Sum Assured.
For a ₹50 lakh Basic Sum Assured:
| Policy year | Absolute Cover |
| Years 1–5 | ₹50 lakh |
| Year 6 | ₹55 lakh |
| Year 7 | ₹60 lakh |
| Year 10 | ₹75 lakh |
| Year 15 | ₹1 crore |
| Year 16 onwards | ₹1 crore |
This table shows the Absolute Cover, not automatically the final death benefit. The final amount is found only after applying the full death-benefit formula.
The selected cover option could not be changed later.
Death-Benefit Formula
For an in-force Regular or Limited Premium policy, the Sum Assured on Death was the highest of:
7 × Annualised Premium
OR
105% of Total Eligible Premiums Paid up to Death
OR
Absolute Amount Assured to Be Paid on Death
For a Single Premium policy, it was the higher of:
125% of Single Premium
OR
Absolute Amount Assured to Be Paid on Death
Annualised Premium excluded taxes, rider premium, underwriting extra and loading for the payment mode. Total Eligible Premiums Paid excluded taxes, rider premium and underwriting extra.
The calculator should compare every applicable amount and show the highest one. It should not assume that the Absolute Cover will always be highest.
How to Use the LIC Jeevan Amar Plan 855 Calculator
1. Enter age at entry
Enter the age when the policy started, not the present age. Use the age printed in the policy schedule.
2. Enter Basic Sum Assured
Enter the original cover shown in the policy bond, such as ₹50,00,000.
3. Select the policy term
Choose the original term. The calculator will use the entry age and term to show the age when the policy ends.
4. Choose the premium payment option
Select Regular, Limited or Single Premium. For Limited Premium, choose Term − 5 or Term − 10 as shown in the policy.
5. Select the cover option
Choose Level Sum Assured or Increasing Sum Assured. This changes the year-wise Absolute Cover.
6. Enter gender and smoking category
Use the category accepted by LIC when the policy was issued. For an existing policy, the premium printed in the policy record is more reliable than a newly generated estimate.
7. Add rider details only when applicable
Enter the Accident Benefit Rider only if it is shown in the policy schedule or rider endorsement.
8. Calculate the result
Check the premium details, payment period, age when the policy ends, Absolute Cover schedule, death-benefit comparison and possible rider amount.
Official Premium Calculation Example
LIC’s historical brochure gave the following sample:
| Input | Selected value |
| Entry age | 30 years |
| Gender | Male |
| Smoking category | Non-smoker |
| Policy term | 20 years |
| Basic Sum Assured | ₹50 lakh |
| Cover option | Level Sum Assured |
| Premium option | Regular yearly premium |
| Annual premium | ₹5,940 before tax |
Premium calculation
Total Planned Base Premium
= ₹5,940 × 20
= ₹1,18,800
The policy would end at age 50:
30 + 20 = 50 yearsThe maturity benefit would be ₹0.
Death-benefit example
Assume death occurred in the twelfth policy year after all 12 annual premiums had been paid.
7 × Annualised Premium
= ₹5,940 × 7
= ₹41,580
105% of Total Eligible Premiums Paid
= ₹5,940 × 12 × 105%
= ₹74,844| Death-benefit test | Amount |
| 7 × Annualised Premium | ₹41,580 |
| 105% of premiums paid | ₹74,844 |
| Absolute Cover | ₹50,00,000 |
The highest amount is ₹50 lakh. Therefore, the base-plan death benefit in this example would be ₹50 lakh, provided the policy was in force and LIC accepted the claim under the policy rules.
Historical LIC Sample Premium Table
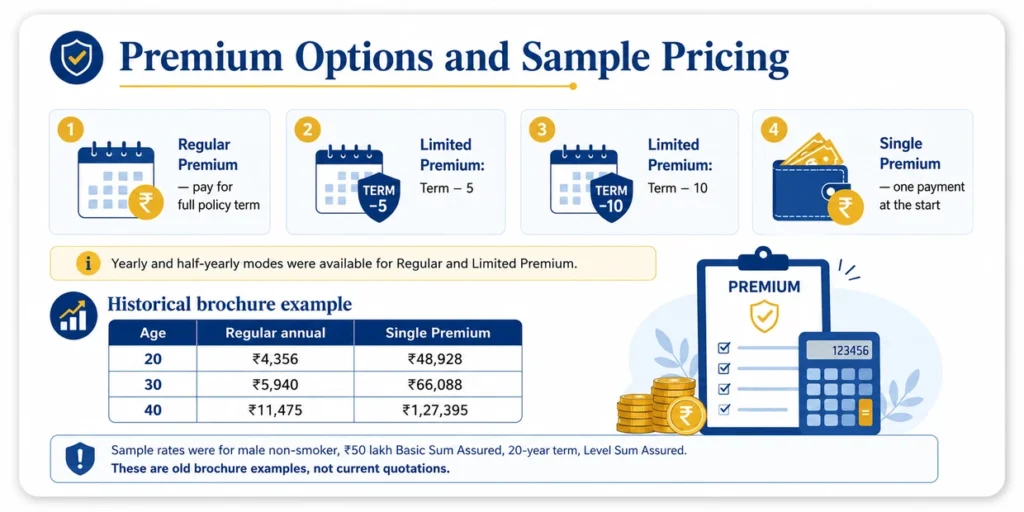
These are old brochure examples, not current quotations. They apply only to a standard non-smoker male, ₹50 lakh Basic Sum Assured, 20-year policy term and the selected payment option. The figures exclude the tax applicable at that time.
Level Sum Assured
| Age | Regular annual | Limited: Term − 5 | Limited: Term − 10 | Single Premium |
| 20 | ₹4,356 | ₹5,104 | ₹6,556 | ₹48,928 |
| 30 | ₹5,940 | ₹6,952 | ₹8,932 | ₹66,088 |
| 40 | ₹11,475 | ₹13,545 | ₹17,595 | ₹1,27,395 |
Increasing Sum Assured
| Age | Regular annual | Limited: Term − 5 | Limited: Term − 10 | Single Premium |
| 20 | ₹5,715 | ₹6,660 | ₹8,595 | ₹63,720 |
| 30 | ₹8,415 | ₹9,900 | ₹12,870 | ₹94,095 |
| 40 | ₹17,664 | ₹20,838 | ₹27,232 | ₹1,95,868 |
These samples show that premium normally increased with age. Increasing Sum Assured and shorter premium payment periods also had higher premiums in these examples.
For an existing policy payment, use the premium and tax treatment shown in the latest LIC premium notice. Do not assume that the tax used when the brochure was published still applies.
High Sum Assured Rebate and Modal Loading
LIC applied a High Sum Assured rebate to the tabular annual or single premium.
Level Sum Assured rebate
| Entry age | ₹50 lakh to below ₹1 crore | ₹1 crore and above |
| Up to 30 years | 12% | 20% |
| 31–50 years | 10% | 15% |
| 51 years and above | 5% | 7% |
Increasing Sum Assured rebate
| Entry age | ₹50 lakh to below ₹1 crore | ₹1 crore and above |
| Up to 30 years | 10% | 18% |
| 31–50 years | 8% | 13% |
| 51 years and above | 4% | 6% |
No High Sum Assured rebate applied below ₹50 lakh. Yearly premium mode had no modal loading, while half-yearly mode carried a loading equal to 2% of the tabular annual premium.
These figures are useful for understanding the old pricing structure. The issued policy premium remains final for an existing policy.
LIC Accident Benefit Rider
The LIC Accident Benefit Rider was available with Regular and Limited Premium policies. It was not available with the Single Premium option.
Rider cover was available during the Premium Paying Term or until the policy anniversary nearest age 70, whichever came first. The outstanding Premium Paying Term had to be at least five years when the rider was selected.
The rider premium could not exceed the base-plan premium. The Accident Benefit Rider Sum Assured could not exceed the Basic Sum Assured on Death under the policy.
The calculator may show the rider Sum Assured as a separate possible amount when the rider was active in the selected year. Actual rider payment depends on LIC accepting the accidental-death claim under the rider terms and exclusions.
Death Benefit in Instalments
The life assured could choose to receive all or part of the death benefit in instalments over 5, 10 or 15 years instead of one lump sum.
| Payment mode | Minimum instalment |
| Monthly | ₹5,000 |
| Quarterly | ₹15,000 |
| Half-yearly | ₹25,000 |
| Yearly | ₹50,000 |
This choice had to be made by the life assured while the policy was active. The nominee could not change it later. If the claim amount was too small to meet the minimum instalment requirement, LIC paid it as a lump sum.
Grace Period, Lapse and Revival
Regular and Limited Premium policies had a 30-day grace period for yearly and half-yearly premiums. The policy remained in force during this period according to its terms.
If the premium was not paid by the end of the grace period, the policy lapsed and cover stopped. A lapsed policy could be considered for revival within five consecutive years from the first unpaid premium date, during the lifetime of the life assured and before the policy end date.
Revival required unpaid premiums, interest and updated health or other information requested by LIC. LIC could accept the revival at original or changed terms, or decline it.
Surrender Refund and Policy Loan
Plan 855 did not provide a normal savings-based surrender value.
- Regular Premium: Nothing was refunded on surrender.
- Single Premium: An applicable refund could be paid during the policy term.
- Limited Premium with a payment term below 10 years: A refund could apply after at least two full consecutive years of premiums.
- Limited Premium with a payment term of 10 years or more: A refund could apply after at least three full consecutive years of premiums.
The payable refund depended on the policy formula and remaining term. No policy loan was available. The rider also did not acquire a surrender value.
Claim Documents and Policy Records
For a death claim, LIC may ask for the claim form, original policy document, death certificate, NEFT details, proof of title and other documents based on the case. Medical or hospital records may also be required.
The policy document asked for death intimation with the death certificate within 90 days. LIC could consider a genuine delayed claim when the delay was beyond the claimant’s control.
Keep these records safely:
- Policy bond and rider endorsement
- Premium receipts
- Nominee details
- Bank and NEFT details
- Identity and address documents
- Medical and hospital records, where relevant
Tax Rule
Tax treatment depends on the law, policy details and reason for payment. Historical brochure premiums excluded GST. For an existing policy, use the tax treatment shown in the latest LIC premium notice.
Do not assume that a tax rate used in an old example applies to every later payment.
Frequently Asked Questions
Is LIC Jeevan Amar Plan 855 still available?
No. LIC withdrew Plan 855 on 22 November 2022. Existing policies continue under their original terms, subject to policy status and premium payment.
What is the maturity amount under Plan 855?
The maturity amount is ₹0. The plan does not return premiums or pay a survival benefit when the life assured completes the term.
Is the calculator an official LIC premium quotation?
No. It is an educational calculator. For an existing policy, use the premium printed in the LIC policy record or premium notice.
What is the difference between Level and Increasing Sum Assured?
Under Level Sum Assured, the Absolute Cover remains equal to the Basic Sum Assured. Under Increasing Sum Assured, it stays level for five years and then rises by 10% of the Basic Sum Assured each year until it reaches double cover in the fifteenth policy year.
Is a policy loan available under Plan 855?
No. LIC Jeevan Amar Plan 855 did not provide a policy loan.
Conclusion
The LIC Jeevan Amar Plan 855 Calculator helps explain an existing policy’s premium payment, Premium Paying Term, age when cover ends, Absolute Cover and possible death benefit. It also makes clear that the plan does not provide a maturity amount.
For the most useful result, match every input with the policy schedule. Check the original Basic Sum Assured, cover option, premium type, premium amount, rider details and policy status. Calculator results are estimates; LIC’s policy records and claim decision remain final.