LIC Jeevan Saral Plan 165 Calculator
Check premium schedule, maturity amount, death benefit and surrender estimate
Calculation Summary
Policy Year 10Premium Overview
Protection and Policy Values
Important calculation note
Death benefit is based on 250 times the monthly premium plus premiums paid after the first policy year and applicable Loyalty Addition. Guaranteed Surrender Value is shown after three completed policy years as 30% of eligible premiums paid after excluding the first-year premium. The final surrender amount may differ because LIC compares Guaranteed Surrender Value with Special Surrender Value.
LIC Jeevan Saral Plan 165 is a life insurance and savings policy offered by Life Insurance Corporation of India. The plan provided life cover, maturity benefits, and surrender options. Now this plan is withdrawn and no longer available for new purchase.
LIC Jeevan Saral was issued under Plan No. 165 with UIN 512N222V01 and was withdrawn from sale on 1 January 2014.
The LIC Jeevan Saral Plan 165 Maturity Calculator helps estimate policy values in a simpler way. For existing policyholders, calculating the expected maturity amount before always be confusing because Jeevan Saral does not have a fixed maturity return for everyone. The result mainly depends on the Maturity Sum Assured (MSA) shown on the policy bond and any applicable Loyalty Addition declared by LIC.
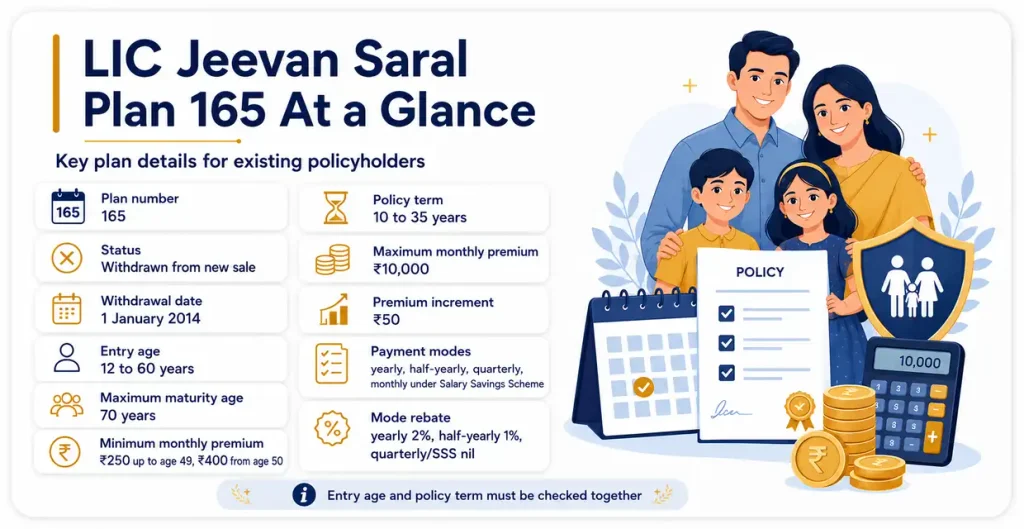
LIC Jeevan Saral Plan 165 Quick Overview
| Particular | Details |
|---|---|
| Plan name | LIC Jeevan Saral |
| Plan number | 165 |
| UIN | 512N222V01 |
| Current status | Withdrawn from the new sale |
| Withdrawal date | 1 January 2014 |
| Minimum entry age | 12 years completed |
| Maximum entry age | 60 years nearest birthday |
| Maximum maturity age | 70 years |
| Policy term | 10 to 35 years |
| Minimum monthly premium up to age 49 | ₹250 |
| Minimum monthly premium from age 50 | ₹400 |
| Maximum monthly premium | ₹10,000 |
| Premium increment | ₹50 |
| Payment modes | Yearly, half-yearly, quarterly, and monthly under the Salary Savings Scheme |
Entry age and policy term must be checked together
Key Features of LIC Jeevan Saral Plan 165
LIC Jeevan Saral Plan 165 offers combined life cover with savings and flexible policy benefits. The main features included:
- Policy term from 10 to 35 years
- Maturity Sum Assured based on age, term, and monthly premium
- Higher death cover is linked to a monthly premium
- Yearly, half-yearly, quarterly, and Salary Savings Scheme payment modes
- Surrender value after the required minimum period
- Paid-up benefit if premiums are stopped after eligibility
- Loan and partial surrender facility
- Loyalty Addition, when declared by LIC
Benefits of LIC Jeevan Saral Plan 165
The main benefits of Jeevan Saral Plan 165 are:
- Maturity Benefit: Maturity Sum Assured plus applicable Loyalty Addition.
- Death Benefit: 250 × monthly premium, plus eligible premiums paid after the first year and applicable Loyalty Addition.
- Surrender Benefit: LIC considers the Guaranteed Surrender Value and the Special Surrender Value.
- Paid-Up Benefit: Reduced benefits may continue if premiums are stopped after the policy acquires paid-up value.
- Loan Facility: A policy loan may be available subject to LIC conditions.
- Partial Surrender: Available from the fourth policy year, subject to policy rules.
What Is the LIC Jeevan Saral Plan 165 Maturity Calculator?
The LIC Jeevan Saral Plan 165 Maturity Calculator is an online tool that helps estimate important benefits of an existing Jeevan Saral policy, including the Maturity Sum Assured, estimated maturity value, death benefit, Guaranteed Surrender Value, paid-up maturity value and premium payment details. For a more accurate maturity estimate, it is best to use the Maturity Sum Assured shown on the original policy bond, because this amount is specific to the policy and is different from the Death Sum Assured. The calculator provides an estimate only, and the actual amount payable by LIC may vary depending on premium records, policy status, policy dates, riders, loans, surrender conditions and applicable Loyalty Addition.
LIC Jeevan Saral Calculator Highlights
The calculator is designed to follow the actual benefit structure of Jeevan Saral Plan 165.
Key features include:
- Uses Maturity Sum Assured for maturity calculation
- Keeps guaranteed and non-guaranteed benefits separate
- Calculates Jeevan Saral death benefit using its specific formula
- Estimates Guaranteed Surrender Value
- Supports paid-up maturity calculations
- Uses entry age, policy term and monthly premium details
- Allows Loyalty Addition to be entered separately when known
- Helps existing policyholders understand an old withdrawn policy
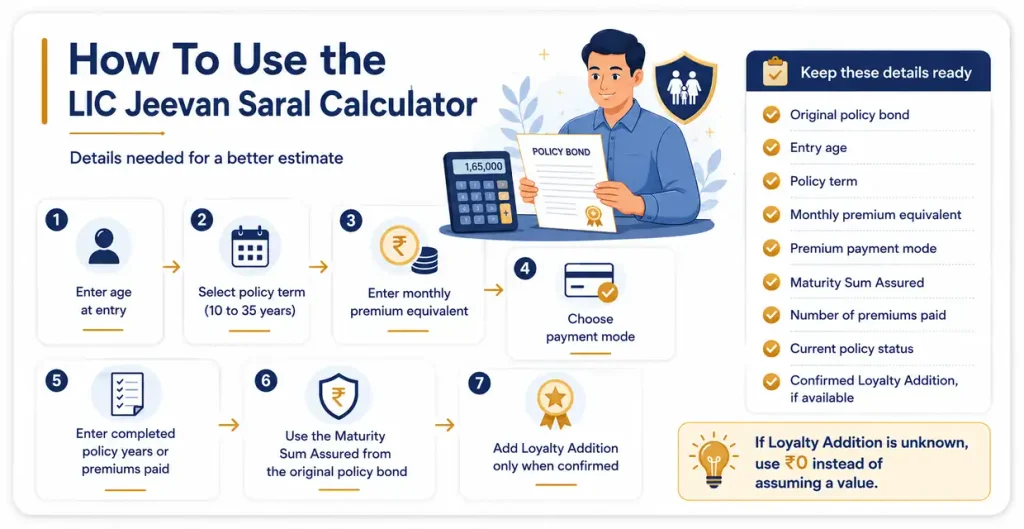
How to Use the LIC Jeevan Saral Plan 165 Maturity Calculator?
Using the calculator is easier when the policy bond and premium details are available.
Enter Age at Entry: Enter the age at which the policy was originally purchased.
This is the entry age, not the current age.
Select the Policy Term: Select the policy term mentioned on the policy bond.
LIC Jeevan Saral offered policy terms from 10 years to 35 years, subject to the maximum maturity-age condition.
Enter Monthly Premium: Enter the monthly premium equivalent for the basic policy.
For example, if the monthly premium is ₹500, enter ₹500.
Do not include rider premium or extra premium unless the calculator specifically asks for them separately.
Select Premium Payment Mode:
The plan offered:
- Yearly
- Half-yearly
- Quarterly
- Monthly under Salary Savings Scheme
The plan provided a 2% rebate for yearly mode and 1% rebate for half-yearly mode. No mode rebate was stated for quarterly or Salary Savings Scheme payments.
Enter Completed Policy Years: For surrender or death-benefit calculations, enter the number of completed policy years correctly.
A completed policy year generally means the required premiums for that period have been paid.
Enter Maturity Sum Assured: For maturity calculations, use the Maturity Sum Assured printed on the policy bond whenever available.
This provides a more reliable result than trying to estimate MSA from general examples.
Enter Loyalty Addition Only When Known: Loyalty Addition is not guaranteed.
Enter it only when the applicable amount is known from LIC records, policy servicing information or another reliable policy document.
If the amount is unknown, keep it at zero rather than using an assumed bonus rate.
What is the maturity sum assured in LIC Jeevan Saral?
Maturity Sum Assured, commonly called MSA, is the guaranteed maturity component of Jeevan Saral when the policy continues according to its terms.
It is not calculated simply by multiplying monthly premium by the number of years.
The Maturity Sum Assured mainly depends on:
- Age at entry
- Policy term
- Monthly premium
If the policy becomes paid-up because premiums are stopped, the full original Maturity Sum Assured may not remain payable. A reduced Maturity Sum Assured is then calculated according to the paid-up rules.
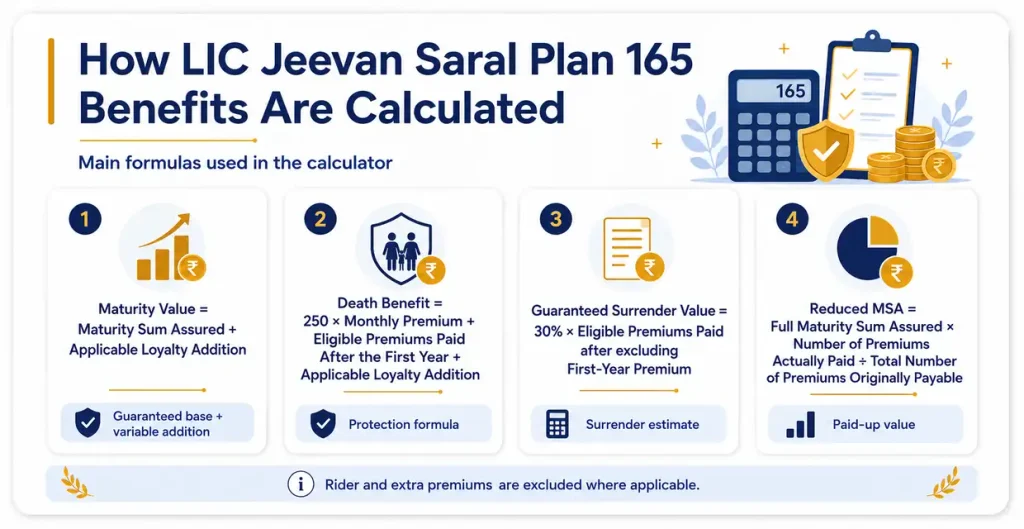
Formula Used in the LIC Jeevan Saral Calculator
Jeevan Saral has different formulas for maturity, death benefit, surrender value and paid-up value.
Maturity Formula
Maturity Value =
Maturity Sum Assured + Applicable Loyalty Addition
The Maturity Sum Assured is the guaranteed component.
Loyalty Addition is variable and is payable only when applicable under LIC’s rules.
Death Benefit Formula
Death Benefit =
250 × Monthly Premium
+ Eligible Premiums Paid After the First Year
+ Applicable Loyalty Addition
Rider premiums and extra premiums are not included in the return-of-premium portion of the death-benefit calculation.
Guaranteed Surrender Value Formula
Guaranteed Surrender Value =
30% × Eligible Premiums Paid
after excluding First-Year Premium
Extra premium and rider premiums are also excluded.
Paid-Up Maturity Sum Assured Formula
Reduced MSA =
Full Maturity Sum Assured
× Number of Premiums Actually Paid
÷ Total Number of Premiums Originally Payable
This calculation is relevant when the policy has acquired paid-up value after premiums are discontinued.
Sample Maturity Sum Assured Values
LIC’s Jeevan Saral brochure provided specimen Maturity Sum Assured values for every ₹100 of monthly premium at selected ages and terms.
| Age at Entry | 10 Years | 15 Years | 20 Years | 25 Years |
|---|---|---|---|---|
| 20 years | ₹11,156 | ₹19,628 | ₹28,039 | ₹36,839 |
| 30 years | ₹11,053 | ₹19,300 | ₹27,345 | ₹35,492 |
| 40 years | ₹10,431 | ₹17,839 | ₹24,598 | ₹30,854 |
| 50 years | ₹8,442 | ₹13,444 | ₹16,164 | Not available |
For example, suppose the entry age is 30 years, policy term is 15 years and monthly premium is ₹400.
The specimen MSA for ₹100 monthly premium is ₹19,300.
Estimated MSA =
₹19,300 × ₹400 ÷ ₹100

= ₹77,200
This method should only be used where the exact age-and-term value is available.
For an existing policy, the Maturity Sum Assured printed on the policy bond should be preferred.
LIC Jeevan Saral Plan 165 Maturity Calculation Example
Consider a Jeevan Saral policy with the following details:
| Policy Detail | Value |
|---|---|
| Age at entry | 35 years |
| Policy term | 30 years |
| Payment mode | Monthly under the Salary Savings Scheme |
| Monthly premium | ₹400 |
| Total scheduled premium over 30 years | ₹1,44,000 |
| Maturity Sum Assured | ₹1,62,416 |
The guaranteed maturity component is therefore:
Maturity Sum Assured = ₹1,62,416
If an applicable Loyalty Addition is declared, it is added separately.
Final Maturity Value =
₹1,62,416 + Applicable Loyalty Addition
If no Loyalty Addition applies, the calculation should not artificially add an assumed bonus.
This is why the calculator should display guaranteed Maturity Sum Assured and variable Loyalty Addition separately.
LIC Jeevan Saral Plan 165 Death Benefit Calculation
The death benefit under Jeevan Saral is different from its maturity benefit.
For an in-force policy, the basic calculation is:
Death Benefit =
250 × Monthly Premium
+ Eligible Premiums Paid After First Year
+ Applicable Loyalty Addition
Suppose the monthly premium is ₹400.
Base Death Cover
250 × ₹400 = ₹1,00,000
Assume 10 complete policy years of premiums have been paid.
Premiums paid in 10 years = ₹48,000
First-year premium = ₹4,800

Eligible premiums after first year =
₹48,000 − ₹4,800

= ₹43,200
The death benefit before Loyalty Addition becomes:
₹1,00,000 + ₹43,200
= ₹1,43,200
Any applicable Loyalty Addition can then be added separately.
Extra premium, Accident Benefit Rider premium and Term Assurance Rider premium should not be included in the returned-premium portion of the calculation.
LIC Jeevan Saral Plan 165 Surrender Value
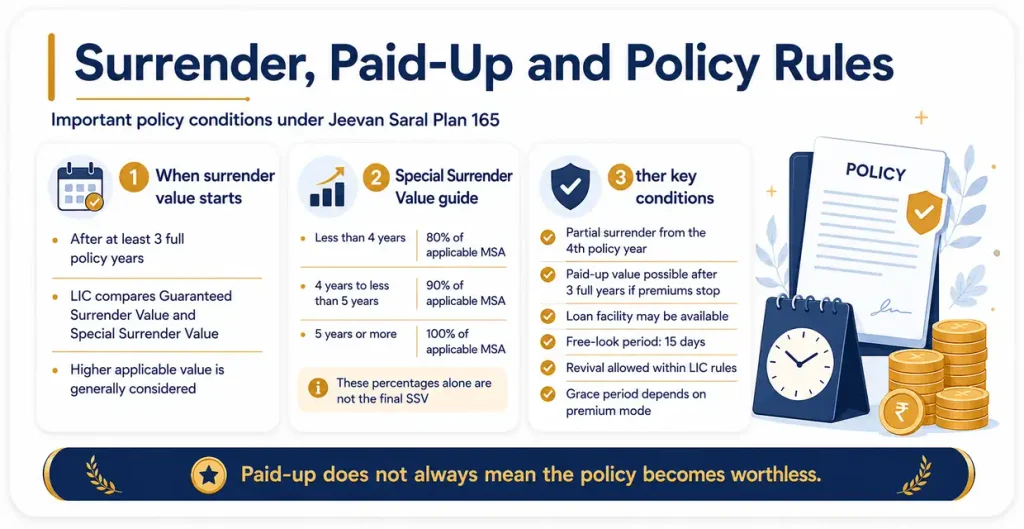
A Jeevan Saral policy can acquire surrender value after the required minimum premium-paying period is completed.
After at least three full policy years, LIC determines surrender value by comparing:
- Guaranteed Surrender Value
- Special Surrender Value
The applicable surrender amount is generally based on the higher value under the policy conditions.
Guaranteed Surrender Value
The basic formula is:
GSV =
30% × (Eligible Premiums Paid − First-Year Premium)
The following are excluded:
- First-year premium
- Extra premium
- Accident Benefit Rider premium
- Term Assurance Rider premium
Guaranteed Surrender Value Example
Suppose the monthly premium is ₹400 and three complete years of premiums have been paid.
Total premiums paid =
₹400 × 12 × 3

= ₹14,400
First-year premium:
₹400 × 12 = ₹4,800
Eligible amount:
₹14,400 − ₹4,800 = ₹9,600
Guaranteed Surrender Value:
30% × ₹9,600 = ₹2,880
Therefore:
GSV = ₹2,880
This is only the Guaranteed Surrender Value. The actual surrender amount may be higher if the calculated Special Surrender Value is greater.
Special Surrender Value
Special Surrender Value uses the Maturity Sum Assured applicable to the premium-paying period.
The following percentage of applicable MSA is considered according to the premium-paying duration:
| Premiums Paid | MSA Portion Used for SSV Calculation |
|---|---|
| Less than 4 years | 80% |
| 4 years to less than 5 years | 90% |
| 5 years or more | 100% |
These percentages should not be treated as the final Special Surrender Value by themselves.
The applicable amount may need to be discounted or accumulated according to the surrender date and LIC’s applicable interest basis. Eligible Loyalty Addition may also affect the final value.
Therefore, a calculator can provide an estimate, but the exact Special Surrender Value should be confirmed with LIC.
Paid-Up Value After Stopping Premiums
If at least three full years of premiums have been paid and later premiums are stopped, the policy may acquire paid-up value.
The policy does not automatically become worthless.
The reduced Maturity Sum Assured can be calculated as:
Reduced MSA =
Full Maturity Sum Assured
× Number of Premiums Actually Paid
÷ Total Number of Premiums Originally Payable
For example, suppose:
Full MSA = ₹2,00,000
Premiums originally payable = 240
Premiums actually paid = 120
Then:
Reduced MSA =
₹2,00,000 × 120 ÷ 240

= ₹1,00,000
Under paid-up status, the amount payable at death or maturity depends on the applicable policy conditions and surrender value rules.
This is why surrendering immediately and keeping the policy paid up can produce different results.
Loyalty Addition in LIC Jeevan Saral Plan 165
Loyalty Addition is an important part of Jeevan Saral, but it is not a guaranteed annual bonus.
It is a variable benefit declared by LIC according to the plan’s valuation experience and applicable conditions.
Loyalty Addition may be relevant for:
- Maturity
- Death claim
- Surrender
However, the amount should not be assumed from unrelated historical rates.
For calculator purposes, the safest method is:
- Use ₹0 when the applicable Loyalty Addition is unknown.
- Enter the confirmed amount when it is available from LIC records or policy servicing information.
This keeps the calculator from showing an inflated maturity estimate.
Tax Benefits in LIC Jeevan Saral Plan 165
Premiums paid for Jeevan Saral may qualify for deduction under Section 80C, subject to the applicable tax conditions and overall limit.
The maturity amount may qualify for exemption under Section 10(10D) if the policy satisfies the required premium-to-sum-assured conditions.
Death benefits are generally treated more favourably under Section 10(10D).
Because Jeevan Saral policies were issued in different years, the exact tax treatment can depend on the policy commencement date, premium and sum assured.
Important LIC Jeevan Saral Policy Conditions
Existing Jeevan Saral policies may also include servicing features such as auto cover, partial surrender, policy loan and revival.
| Feature | Key Point |
|---|---|
| Auto cover | Available subject to policy conditions after the required in-force period |
| Partial surrender | Available from the fourth policy year, subject to conditions |
| Loan facility | Available after the policy acquires the required value |
| Free-look period | 15 days under the original plan conditions |
| Revival | Available within the permitted revival period, subject to LIC rules |
| Grace period | Applicable according to the premium payment mode |
| Yearly mode rebate | 2% |
| Half-yearly mode rebate | 1% |
| Quarterly/SSS mode rebate | Nil |
Historical loan or revival interest rates mentioned in old policy documents should not automatically be treated as current rates because servicing terms may change.
Riders Benefit Under LIC Jeevan Saral
LIC Jeevan Saral offered optional riders such as the Accidental Death and Disability Benefit Rider and Term Assurance Rider for an additional premium.
These rider premiums should be kept separate from the basic policy premium when calculating the maturity amount, the returned-premium part of the death benefit or the Guaranteed Surrender Value.
Details Needed for Right Calculation
For a more accurate Jeevan Saral calculation, keep the following details ready:
- Original policy bond
- Entry age
- Policy term
- Monthly premium equivalent
- Premium payment mode
- Maturity Sum Assured
- Number of premiums paid
- Completed policy years
- Current policy status
- Confirmed Loyalty Addition, if available
The Maturity Sum Assured shown on the original policy bond is especially important because it reduces the need to estimate the maturity value from specimen tables.
Frequently Asked Questions
Is LIC Jeevan Saral Plan 165 still available for purchase?
No. LIC Jeevan Saral Plan 165 is a withdrawn plan and is no longer available for new purchase. Existing policyholders can continue to deal with their policies according to applicable LIC servicing rules.
How LIC Jeevan Saral maturity amount calculated?
The basic maturity formula is:
Maturity Value =
Maturity Sum Assured + Applicable Loyalty Addition
The Maturity Sum Assured is the guaranteed base component, while Loyalty Addition is variable.
Other Related Calculator:
What is the difference between Death Sum Assured and Maturity Sum Assured?
Death Sum Assured relates to the protection payable on death according to policy conditions.
Maturity Sum Assured is the guaranteed maturity component used when calculating the amount payable on survival until maturity.
They are different values.
Can LIC Jeevan Saral be surrendered after three years?
A policy can acquire surrender value after at least three full policy years, subject to the policy conditions. LIC compares the applicable Guaranteed Surrender Value and Special Surrender Value when determining the surrender benefit.
What happens if Jeevan Saral premiums are stopped?
If at least three full years of required premiums have been paid, the policy may become paid-up. The original Maturity Sum Assured can then be reduced according to the proportion of premiums actually paid compared with the total premiums originally payable.
Is Loyalty Addition guaranteed in LIC Jeevan Saral?
No. Loyalty Addition is not guaranteed. It depends on LIC’s declaration and the conditions applicable to the policy. It should therefore be kept separate from the guaranteed Maturity Sum Assured when estimating maturity value.
Conclusion
The LIC Jeevan Saral Plan 165 Maturity Calculator helps simplify a policy whose maturity, death, surrender and paid-up benefits follow different rules. For maturity calculations, the most important figure is the Maturity Sum Assured printed on the policy bond.
The basic maturity calculation is Maturity Sum Assured plus any applicable Loyalty Addition. Surrender and paid-up calculations are more detailed and depend on premiums paid, policy duration, and policy status. The calculator can provide a useful estimate, while the final amount payable should be confirmed with LIC using the actual policy records.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.