Jeevan Shiromani Premium Plan 847 Calculator
Premium & Benefit Estimate
First Policy Year Premium
Tax: 0%| Payment Mode | Premium | Tax | Total |
|---|
Renewal Year Premium
Tax: 0%| Payment Mode | Premium | Tax | Total |
|---|
Plan Benefit Snapshot
Guaranteed Addition & Payout Timeline
Policy Schedule| Policy Year | Guaranteed Addition | Survival Benefit | Event / Remark |
|---|
LIC Jeevan Shiromani Plan 847 is a limited-premium money-back life insurance plan for policies with a high Basic Sum Assured. It provides two survival benefits before maturity and pays the remaining part of the Basic Sum Assured at the end of the policy term. Guaranteed Additions also build during eligible premium-paying years.
The LIC Jeevan Shiromani Plan 847 Calculator helps existing policyholders estimate their premium, survival benefits, Guaranteed Additions, maturity amount, basic death cover and inbuilt Critical Illness Benefit.
In this guide, we will get complete details of LIC Jeevan Shiromani Plan 847 with UIN 512N315V01. LIC lists this version under withdrawn plans, so it is not available for a new purchase. Existing policies continue according to their original terms. Plan 847 should not be confused with the later Plan 947.
Also Check:
What Does the Calculator Show in Result?
After the policy details are entered, the calculator can show:
- Premium Paying Term
- Estimated annual and payment-mode premium
- Total scheduled base premium
- First and second survival benefits
- Basic maturity portion
- Accrued Guaranteed Additions
- Optional Loyalty Addition estimate
- Estimated maturity amount
- Basic Sum Assured on Death comparison
- Inbuilt Critical Illness Benefit
LIC Jeevan Shiromani Plan 847 Quick Overview
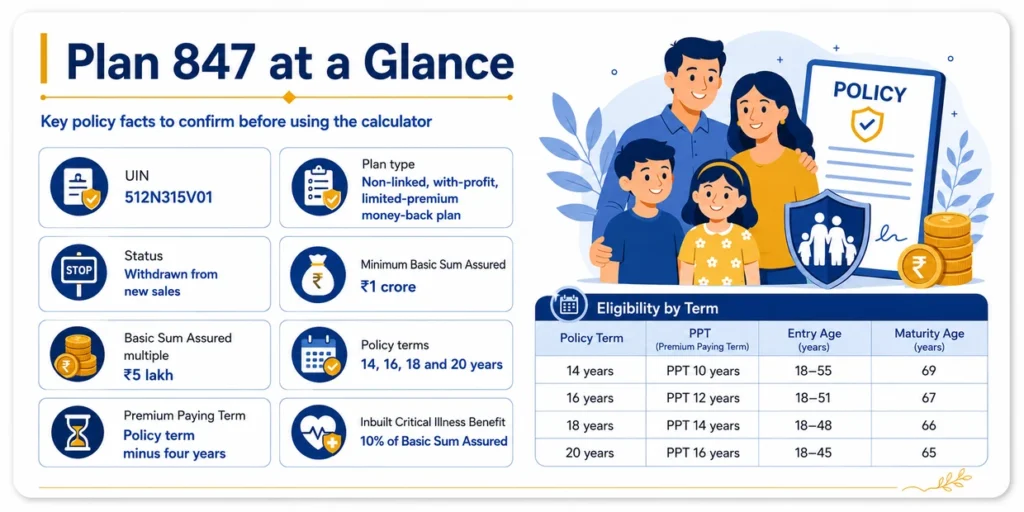
| Feature | Details |
|---|---|
| Plan name | LIC Jeevan Shiromani |
| Plan number | 847 |
| UIN | 512N315V01 |
| Plan type | Non-linked, with-profit, limited-premium money-back plan |
| Status | Withdrawn from new sales |
| Launch date | Not specified on LIC’s withdrawn-plan page |
| Withdrawal date | Not specified on LIC’s withdrawn-plan page |
| Minimum Basic Sum Assured | ₹1 crore |
| Maximum Basic Sum Assured | No fixed limit, subject to underwriting |
| Basic Sum Assured multiple | ₹5 lakh |
| Policy terms | 14, 16, 18 and 20 years |
| Premium Paying Term | Policy term minus four years |
| Inbuilt Critical Illness Benefit | 10% of Basic Sum Assured |
Jeevan Shiromani Plan 847 Eligibility and Policy Terms
| Policy term | Premium Paying Term | Minimum entry age | Maximum entry age | Maximum maturity age |
| 14 years | 10 years | 18 years | 55 years | 69 years |
| 16 years | 12 years | 18 years | 51 years | 67 years |
| 18 years | 14 years | 18 years | 48 years | 66 years |
| 20 years | 16 years | 18 years | 45 years | 65 years |
The calculator must use the age at policy commencement, not the current age. Entry age was considered on a nearer-birthday basis. The calculation should stop when the entered age is not allowed for the selected term.
The Premium Paying Term is always four years shorter than the policy term:
Premium Paying Term = Policy Term − 4 yearsFor example, a 14-year policy requires premiums for 10 years, while a 20-year policy requires premiums for 16 years.
How to Use the Jeevan Shiromani Plan 847 Calculator?
Keep the original policy schedule or premium receipt nearby before starting.
- Enter the age at policy commencement shown in the policy records.
- Select the policy term: 14, 16, 18 or 20 years.
- Enter the Basic Sum Assured. It must be at least ₹1 crore and in multiples of ₹5 lakh.
- Choose yearly, half-yearly, quarterly or monthly premium mode.
- Enter rider premium only when the rider appears in the policy schedule.
- Keep tax separate from the base premium.
- Enter Loyalty Addition only when testing an assumption or using a confirmed figure. Otherwise, leave it at zero.
- Select Calculate to view the estimated premium and benefit schedule.
The calculator should display guaranteed amounts separately from Loyalty Addition because Loyalty Addition is not guaranteed.
Premium Calculation
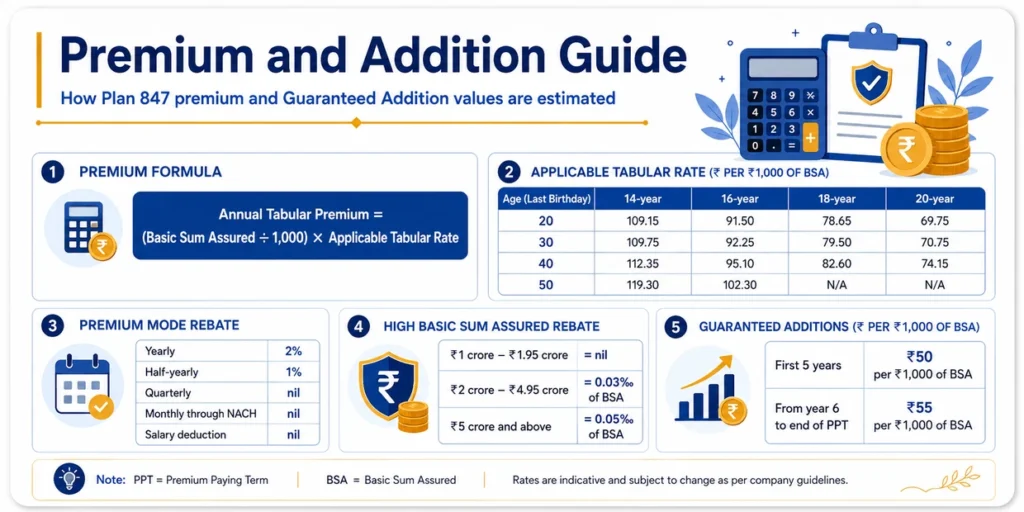
LIC’s brochure provides sample annual tabular premium rates for selected ages. The rates are quoted for every ₹1,000 of Basic Sum Assured and exclude tax.
| Age | 14-year term | 16-year term | 18-year term | 20-year term |
| 20 years | ₹109.15 | ₹91.50 | ₹78.65 | ₹69.75 |
| 30 years | ₹109.75 | ₹92.25 | ₹79.50 | ₹70.75 |
| 40 years | ₹112.35 | ₹95.10 | ₹82.60 | ₹74.15 |
| 50 years | ₹119.30 | ₹102.30 | Not available | Not available |
The premium formula is:
Annual Tabular Premium =
(Basic Sum Assured ÷ 1,000) × Applicable Tabular Rate
The brochure provides sample rates for only a few ages. A premium for another age should be labelled approximate unless the calculator contains LIC’s complete official age-wise rate table.
Premium-mode rebate
| Premium mode | Rebate |
| Yearly | 2% of tabular premium |
| Half-yearly | 1% of tabular premium |
| Quarterly | Nil |
| Monthly through NACH | Nil |
| Salary deduction | Nil |
High Basic Sum Assured rebate
| Basic Sum Assured | Rebate on tabular premium |
| ₹1 crore to ₹1.95 crore | Nil |
| ₹2 crore to ₹4.95 crore | 0.03‰ of Basic Sum Assured |
| ₹5 crore and above | 0.05‰ of Basic Sum Assured |
For a ₹2 crore Basic Sum Assured:
₹2,00,00,000 × 0.03 ÷ 1,000 = ₹600These rebates reduce the base premium. Tax, rider premium and underwriting extras are added separately.
Guaranteed Additions
Guaranteed Additions accrue during the Premium Paying Term when the required premiums are paid.
| Policy period | Guaranteed Addition rate |
| First five policy years | ₹50 per ₹1,000 of Basic Sum Assured |
| From year 6 to the end of PPT | ₹55 per ₹1,000 of Basic Sum Assured |
For a ₹1 crore Basic Sum Assured:
₹1,00,00,000 ÷ 1,000 = 10,000 unitsYearly GA during first five years
= 10,000 × ₹50
= ₹5,00,000Yearly GA from year 6 to end of PPT
= 10,000 × ₹55
= ₹5,50,000Guaranteed Additions are not yearly cash payments. They accumulate and are included with an eligible maturity or death benefit according to the policy terms. Their treatment changes if the policy becomes paid-up or is surrendered.
Survival Benefits
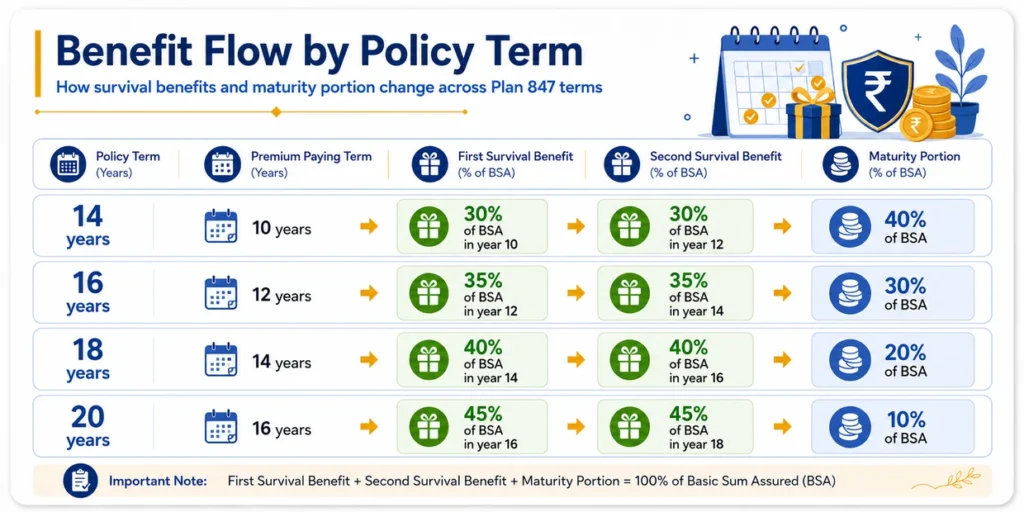
The two survival benefits are payable when the life assured survives to the specified policy anniversaries and the policy meets the applicable conditions.
| Policy term | First survival benefit | Second survival benefit |
| 14 years | 30% of BSA in year 10 | 30% of BSA in year 12 |
| 16 years | 35% of BSA in year 12 | 35% of BSA in year 14 |
| 18 years | 40% of BSA in year 14 | 40% of BSA in year 16 |
| 20 years | 45% of BSA in year 16 | 45% of BSA in year 18 |
The maturity percentage already represents the remaining part of the Basic Sum Assured. For a 14-year policy, 60% is paid through survival benefits and 40% forms the basic maturity portion.
The policy also allowed eligible survival benefits to be deferred. The deferred amount earns interest at LIC’s applicable rate, subject to the policy conditions and a timely written request.
Maturity Benefit Formula
Maturity Benefit =
Sum Assured on Maturity
+ Accrued Guaranteed Additions
+ Loyalty Addition, if declared and payable| Policy term | Sum Assured on Maturity |
| 14 years | 40% of Basic Sum Assured |
| 16 years | 30% of Basic Sum Assured |
| 18 years | 20% of Basic Sum Assured |
| 20 years | 10% of Basic Sum Assured |
Loyalty Addition depends on LIC’s declaration and the policy satisfying its conditions. It must not be shown as a guaranteed return.
Real Calculation Example
In this calculation, we will use the following details.
| Input | Value |
| Age at entry | 30 years |
| Basic Sum Assured | ₹1 crore |
| Policy term | 14 years |
| Premium Paying Term | 10 years |
| Premium mode | Yearly |
| Tabular rate | ₹109.75 per ₹1,000 BSA |
Annual premium
Tabular Premium
= (₹1,00,00,000 ÷ 1,000) × ₹109.75
= ₹10,97,500
Yearly-mode rebate:
2% of ₹10,97,500 = ₹21,950Estimated Yearly Base Premium
= ₹10,97,500 − ₹21,950
= ₹10,75,550 excluding taxTotal scheduled base premium:
₹10,75,550 × 10 = ₹1,07,55,500Guaranteed Additions
First five years
= ₹5,00,000 × 5
= ₹25,00,000
Years 6 to 10
= ₹5,50,000 × 5
= ₹27,50,000Total Guaranteed Additions
= ₹25,00,000 + ₹27,50,000
= ₹52,50,000Survival and maturity benefits
The policy pays ₹30 lakh in year 10 and another ₹30 lakh in year 12.
Basic Maturity Portion
= 40% of ₹1 crore
= ₹40,00,000
Maturity Benefit Excluding Loyalty Addition
= ₹40,00,000 + ₹52,50,000
= ₹92,50,000Total Scheduled Benefits
= ₹30,00,000 + ₹30,00,000 + ₹92,50,000
= ₹1,52,50,000The ₹1.525 crore total combines payments received in policy years 10, 12 and 14. It is not paid as one maturity amount and should not be treated as investment profit. The example excludes tax, riders, extra premium and Loyalty Addition.
Death Benefit
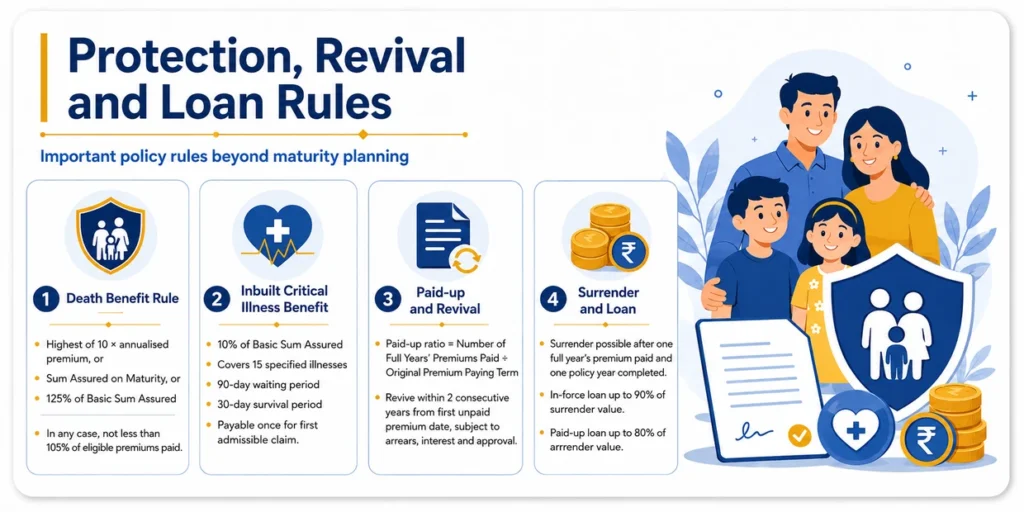
For an in-force policy, the Sum Assured on Death is the highest of:
10 × Annualised Premium

or

Sum Assured on Maturity

or

125% of Basic Sum Assured
The death benefit cannot be less than 105% of eligible premiums paid up to the date of death. Tax, rider premium and underwriting extra premium are excluded.
For the ₹1 crore example:
| Comparison | Amount |
| 10 × annualised premium | ₹1,07,55,500 |
| Sum Assured on Maturity | ₹40,00,000 |
| 125% of Basic Sum Assured | ₹1,25,00,000 |
The highest amount is ₹1.25 crore. Accrued Guaranteed Additions are added. After five policy years, Loyalty Addition may also be payable when declared and applicable.
Inbuilt Critical Illness Benefit
The inbuilt Critical Illness Benefit is 10% of the Basic Sum Assured. For a ₹1 crore policy, the benefit is ₹10 lakh.
It covers 15 specified illnesses, including certain cancers, heart conditions, kidney failure, stroke, major organ transplant, Primary Pulmonary Hypertension and other conditions listed in the policy document. Every illness must meet LIC’s exact medical definition.
A 90-day waiting period generally applies from risk commencement or revival, and a 30-day survival period applies after diagnosis. The benefit is payable once for the first admissible claim. Eligible premiums falling due within two years of an admitted claim may be deferred according to the policy terms.
Paid-Up, Revival and Surrender Rules
A policy does not acquire paid-up value if premiums stop before the required minimum period. After at least one full year’s premium has been paid and one policy year has been completed, it may continue with reduced paid-up benefits if later premiums are missed.
The basic paid-up ratio is:
Paid-Up Ratio =
Number of Full Years’ Premiums Paid
÷ Original Premium Paying Term
LIC applies this proportion through separate death, survival, maturity and Critical Illness Benefit formulas. Accrued Guaranteed Additions also have separate paid-up treatment. A calculator should not use one simple multiplication for every benefit unless all official formulas have been implemented.
Under Plan 847, a lapsed policy could be revived within two consecutive years from the first unpaid premium date, subject to arrears, interest, continued insurability and LIC’s approval.
Surrender becomes available after one full year’s premium has been paid and one policy year has been completed. LIC pays the higher of Guaranteed Surrender Value and Special Surrender Value. The final amount depends on eligible premiums, surrender factors, accrued Guaranteed Additions and any survival benefit already paid.
Policy Loan
A loan may be available after the policy acquires surrender value.
| Policy status | Maximum loan |
| In-force policy | Up to 90% of surrender value |
| Paid-up policy | Up to 80% of surrender value |
The applicable loan interest rate is decided by LIC. The 9.5% rate mentioned in the old brochure applied to loans sanctioned during a stated historical financial year and should not be treated as the current rate.
Tax Rule
Applicable tax is charged separately on the premium and does not increase policy benefits.
Plan 847 was withdrawn before the special rules introduced for certain non-ULIP policies issued on or after 1 April 2023. However, tax treatment still depends on the policy issue date, premium-to-Sum-Assured ratio and other conditions under the Income Tax Act.
Premium deduction under Section 80C and exemption under Section 10(10D) should be checked using the original policy records and applicable tax law. Individual tax advice should be obtained from a qualified professional.
Frequently Asked Questions
Is Plan 847 still available for purchase?
No. LIC lists it under withdrawn plans. This guide is intended for existing policies and historical policy records.
What is the minimum Basic Sum Assured?
The minimum is ₹1 crore. Higher amounts must be selected in multiples of ₹5 lakh.
Is the survival benefit included in the maturity benefit?
No. Survival benefits are paid during the policy term. The maturity percentage represents the remaining part of the Basic Sum Assured and is paid separately with eligible additions.
Is Loyalty Addition guaranteed?
No. It depends on LIC’s declaration and the policy satisfying the required conditions.
Are Guaranteed Additions paid every year?
No. They accrue during eligible policy years but are not paid as annual cash benefits.
Can the calculator show an exact surrender value?
Not without all applicable LIC factors and the complete policy history. The final surrender value must be confirmed with LIC.
Conclusion
LIC Jeevan Shiromani Plan 847 combines two scheduled money-back payments with a final maturity benefit, Guaranteed Additions, life cover and an inbuilt Critical Illness Benefit. The calculator makes the premium period and benefit schedule easier to understand.
Results should be treated as planning estimates. Premium, policy status, Loyalty Addition, surrender value, loan balance and claim amounts must be checked against the policy bond and LIC’s official records.