LIC Jeevan Utsav Single Premium Calculator Plan 833
Calculate estimated guaranteed additions, income benefits and maturity
Calculate Your Benefits
Estimated Policy Benefits
Policy Details
Guaranteed Additions
Survival Income
Estimated Cover & Maturity
Important Calculation Note
LIC Jeevan Utsav Plan 883 Single Premium is designed for people who prefer paying once instead of paying premiums every year. It combines whole-life insurance cover, Guaranteed Additions and an income option that can either be received regularly or accumulated for later use.
The plan is officially called LIC’s Jeevan Utsav Single Premium, with UIN 512N392V01. LIC announced Plan No. 883 on 6 January 2026, and it became available for purchase from 12 January 2026. It is a non-participating, non-linked, individual savings and whole-life insurance plan.
Use the LIC Jeevan Utsav Single Premium Plan 883 Calculator above to understand the estimated policy term, Guaranteed Additions, annual income benefit, income start year, minimum death-benefit basis and minimum maturity-benefit basis.
Important: The calculator is a benefit estimator. When Tabular Single Premium is not entered, it uses Basic Sum Assured as the minimum Sum Assured on Death and Sum Assured on Maturity. The actual LIC amounts may be higher and depend on the official Tabular Single Premium, applicable rebate, underwriting decision, rider selection and benefit illustration.
LIC Jeevan Utsav Single Premium Plan 883: Quick Facts
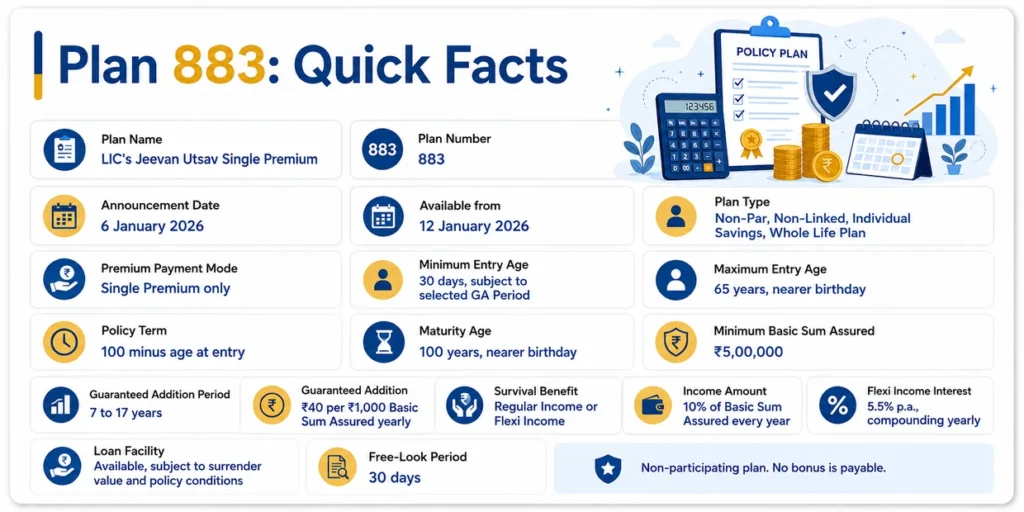
| Feature | Details |
|---|---|
| Plan Name | LIC’s Jeevan Utsav Single Premium |
| Plan Number | 883 |
| UIN | 512N392V01 |
| Announcement Date | 6 January 2026 |
| Available from | 12 January 2026 |
| Plan Type | Non-Par, Non-Linked, Individual Savings, Whole Life Plan |
| Premium Payment Mode | Single Premium only |
| Minimum Entry Age | 30 days, subject to selected GA Period |
| Maximum Entry Age | 65 years, nearer birthday |
| Policy Term | 100 minus age at entry |
| Maturity Age | 100 years, nearer birthday |
| Minimum Basic Sum Assured | ₹5,00,000 |
| Guaranteed Addition Period | 7 to 17 years |
| Minimum Age at First Income | 18 completed years |
| Guaranteed Addition | ₹40 per ₹1,000 Basic Sum Assured yearly |
| Survival Benefit | Regular Income or Flexi Income |
| Income Amount | 10% of Basic Sum Assured every year |
| Flexi Income Interest | 5.5% p.a., compounding yearly |
| Loan Facility | Available, subject to surrender value and policy conditions |
| Free-Look Period | 30 days |
LIC confirms that the plan has no bonus because it is a non-participating policy. The death and survival benefits are fixed according to policy terms and do not depend on LIC’s surplus or bonus declaration.
What Is LIC Jeevan Utsav Single Premium Plan 883?
LIC Jeevan Utsav Single Premium Plan 883 is a life insurance policy where the policyholder pays one premium at the beginning. There is no monthly, quarterly, half-yearly, or yearly premium payment requirement later.
After paying the single premium, the policy provides life cover up to maturity age 100. It also gives Guaranteed Additions for the selected period and starts survival income after that period. The policyholder can choose whether to receive the income every year or keep it accumulated under the Flexi Income option.
The plan has three main layers:
- Life cover for the Life Assured.
- Guaranteed Additions for 7 to 17 years.
- Annual income benefit after the Guaranteed Addition Period.
This is not a market-linked product. Returns do not depend on stock market movement, mutual fund performance, NAV, or LIC bonus rates.
Also Check:
- LIC Jeevan Utsav Calculator All in One
- LIC Jeevan Utsav Plan 771 Calculator
- LIC Jeevan Utsav Plan 871 Calculator
How to Use the LIC Jeevan Utsav Plan 883 Calculator
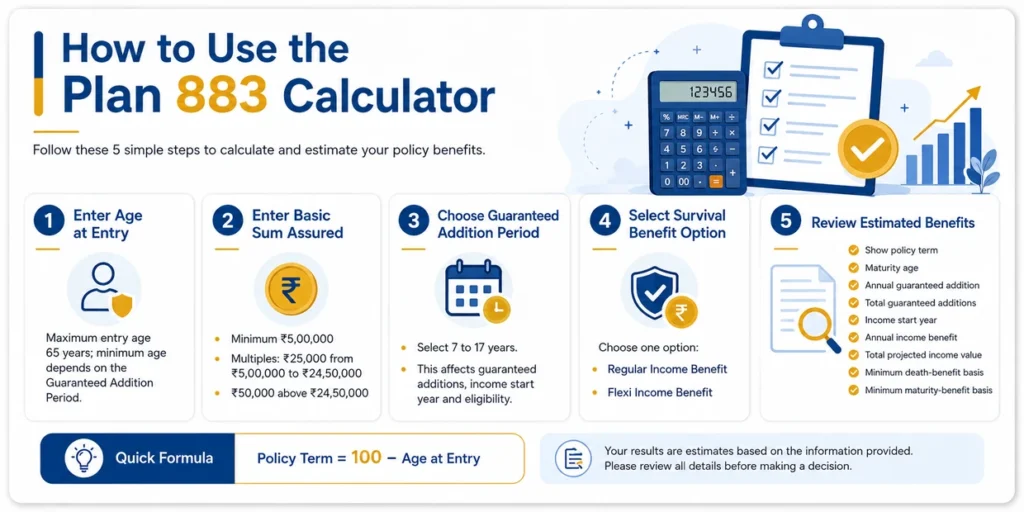
The calculator is intentionally simple. It does not ask for premium rate charts, Tabular Single Premium, GST, rider premium, or rebate details.
Follow these steps:
Step 1: Enter Age at Entry
Enter the age of the Life Assured at the time of policy purchase.
The maximum entry age is 65 years. The minimum age changes according to the Guaranteed Addition Period selected.
Step 2: Enter Basic Sum Assured
Enter the chosen Basic Sum Assured. The minimum allowed amount is ₹5,00,000.
The amount must follow LIC’s multiple rules:
| Basic Sum Assured Range | Allowed Multiple |
| ₹5,00,000 to ₹24,50,000 | ₹25,000 |
| Above ₹24,50,000 | ₹50,000 |
For example, ₹10,00,000 and ₹12,50,000 are valid values. ₹10,15,000 may not meet the prescribed multiple requirement.
Step 3: Choose Guaranteed Addition Period
Select a Guaranteed Addition Period from 7 years to 17 years.
This selection decides:
- How long Guaranteed Additions will accrue.
- When Regular Income or Flexi Income starts.
- Minimum age eligibility.
- Loan limits during the GA Period.
Step 4: Select Survival Benefit Option
Choose one of these options:
- Regular Income Benefit: Receive annual income directly.
- Flexi Income Benefit: Allow annual income to accumulate at 5.5% yearly compounding, subject to policy rules.
Step 5: Review Estimated Benefits
The calculator will show:
- Policy term
- Maturity age
- Annual Guaranteed Addition
- Total Guaranteed Additions
- Income start year
- Annual income benefit
- Total projected Regular Income or Flexi Income value
- Minimum estimated death-benefit basis when Tabular Single Premium is not entered
- Minimum estimated maturity-benefit basis when Tabular Single Premium is not entered
The official policy term is calculated as:
Policy Term = 100 − Age at EntryLIC sets maturity at age 100, while the first income benefit cannot fall due before the Life Assured completes 18 years.
Eligibility Conditions for Plan 883
| Guaranteed Addition Period | Minimum Age at Entry |
| 7 years | 10 years |
| 8 years | 9 years |
| 9 years | 8 years |
| 10 years | 7 years |
| 11 years | 6 years |
| 12 years | 5 years |
| 13 years | 4 years |
| 14 years | 3 years |
| 15 years | 2 years |
| 16 years | 1 year |
| 17 years | 30 days |
The minimum Basic Sum Assured is ₹5 lakh. There is no fixed maximum Basic Sum Assured, but higher cover is subject to LIC underwriting approval.
Guaranteed Additions Explained Simply
Guaranteed Additions are extra amounts added to the policy during the selected Guaranteed Addition Period.
LIC adds:
₹40 for every ₹1,000 of Basic Sum Assured each policy yearThis is equal to 4% of the Basic Sum Assured every year during the GA Period.
Guaranteed Addition Formula
Annual Guaranteed Addition =
Basic Sum Assured × 4%
For a Basic Sum Assured of ₹10,00,000:
₹10,00,000 × 4% = ₹40,000 per yearIf the selected Guaranteed Addition Period is 10 years:
₹40,000 × 10 = ₹4,00,000 total Guaranteed AdditionsGuaranteed Additions stop after the selected GA Period ends. If death occurs during the GA Period, LIC provides the Guaranteed Addition for that entire policy year.
When Does Income Start?
Income starts after the Guaranteed Addition Period is over.
| Guaranteed Addition Period | Income Starts From |
| 7 years | End of 8th policy year |
| 8 years | End of 9th policy year |
| 9 years | End of 10th policy year |
| 10 years | End of 11th policy year |
| 11 years | End of 12th policy year |
| 12 years | End of 13th policy year |
| 13 years | End of 14th policy year |
| 14 years | End of 15th policy year |
| 15 years | End of 16th policy year |
| 16 years | End of 17th policy year |
| 17 years | End of 18th policy year |
Both Regular Income and Flexi Income are equal to 10% of Basic Sum Assured every year. The payment continues while the Life Assured survives, up to the policy anniversary immediately before maturity.
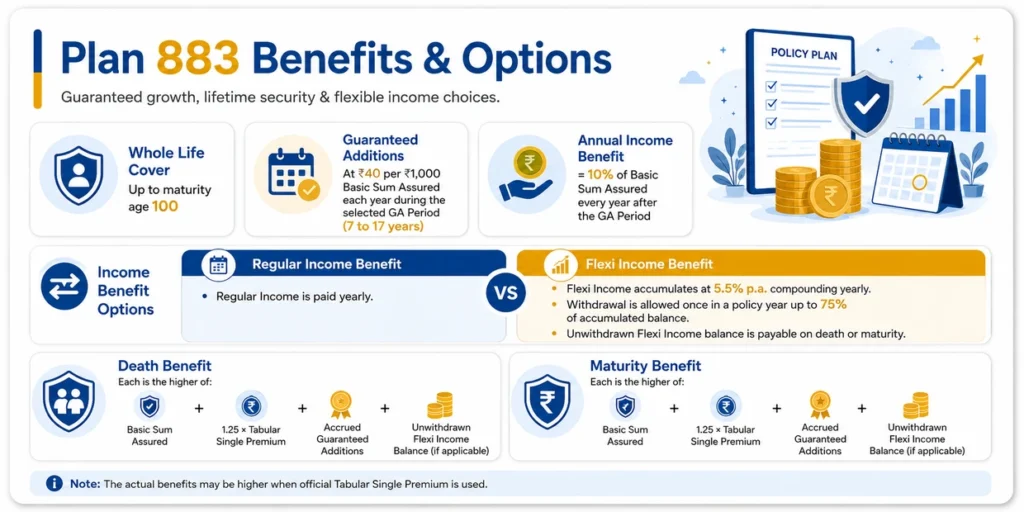
Regular Income Benefit vs Flexi Income Benefit
| Feature | Regular Income Benefit | Flexi Income Benefit |
| Annual benefit | 10% of Basic Sum Assured | 10% of Basic Sum Assured |
| Payment method | Paid directly every year | Accumulated unless withdrawn |
| Accumulation interest | Not applicable | 5.5% p.a. compounding yearly |
| Withdrawal facility | Not applicable | Once in a policy year |
| Maximum withdrawal | Not applicable | Up to 75% of accumulated balance |
| Balance payable on death or maturity | Not applicable | Yes, if not withdrawn |
| Suitable for | Regular yearly cash flow | Long-term accumulation flexibility |
Under Flexi Income, LIC accumulates unpaid income at 5.5% per year, compounded yearly for completed months. A maximum of 75% of the accumulated balance may be withdrawn once in a policy year. The remaining balance keeps accumulating.
Real LIC Jeevan Utsav Single Premium Plan 883 Calculator Example
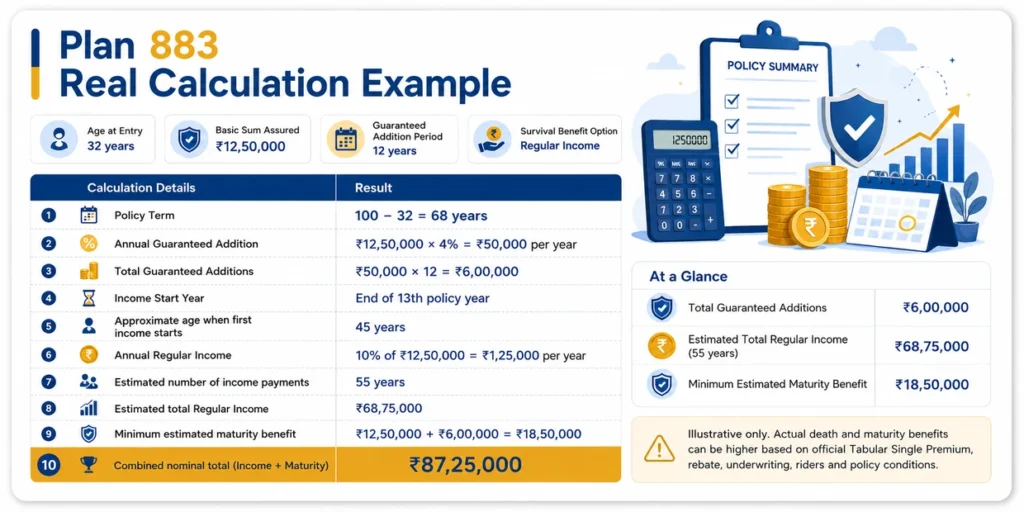
Assume the following policy details:
| Input | Value |
| Age at Entry | 32 years |
| Basic Sum Assured | ₹12,50,000 |
| Guaranteed Addition Period | 12 years |
| Survival Benefit Option | Regular Income |
Step 1: Calculate Policy Term
Policy Term = 100 − 32
Policy Term = 68 years
The policy matures when the Life Assured reaches age 100.
Step 2: Calculate Annual Guaranteed Addition
Annual Guaranteed Addition =
₹12,50,000 × 4%

= ₹50,000 per year
Step 3: Calculate Total Guaranteed Additions
Total Guaranteed Additions =
₹50,000 × 12 years

= ₹6,00,000
Step 4: Find Income Start Year
A 12-year GA Period means income starts at the end of the 13th policy year.
The first income becomes due approximately 13 years after policy commencement. Based on the entered age, the Life Assured would be approximately:
32 + 13 = 45 years oldwhen the first annual income becomes due. The exact age depends on the commencement date and age basis recorded by LIC.
Step 5: Calculate Annual Regular Income
Annual Regular Income =
10% of ₹12,50,000

= ₹1,25,000 every year
Step 6: Estimate Number of Income Payments
The policy term is 68 years. Income is payable from the end of policy year 13 through the policy anniversary immediately before maturity, which is the end of policy year 67.
Estimated number of income payments =
67 − 13 + 1

= 55 years
Step 7: Estimate Total Regular Income
₹1,25,000 × 55

= ₹68,75,000
This is the nominal total of 55 annual Regular Income payments, assuming the Life Assured survives until every payment date. It is not a present value and does not adjust for inflation or the time value of money.
Step 8: Minimum Maturity Benefit Estimate
Minimum Sum Assured on Maturity assumed =
Basic Sum Assured = ₹12,50,000

Total Guaranteed Additions = ₹6,00,000

Minimum estimated maturity benefit =
₹18,50,000
The nominal total of the assumed lifetime Regular Income payments and minimum maturity estimate becomes:
₹68,75,000 + ₹18,50,000
= ₹87,25,000
This ₹87,25,000 figure is not a lump-sum return or present value. It assumes survival to every income date and maturity, and it does not adjust for inflation or the time value of money. The actual Sum Assured on Maturity is the higher of Basic Sum Assured and 1.25 times the official Tabular Single Premium. Therefore, ₹18,50,000 is only a minimum illustrative maturity estimate.
What Is Tabular Single Premium?
Tabular Single Premium is the official premium amount calculated by LIC using the Life Assured’s age, selected Basic Sum Assured, and Guaranteed Addition Period.
It is calculated before:
- Premium rebates
- Underwriting extra premium
- Rider premium
- Taxes
LIC uses Tabular Single Premium to determine the final Sum Assured on Death and Sum Assured on Maturity.
It is important to separate three premium terms:
- Tabular Single Premium: Premium before rebate or underwriting extra and excluding tax and rider premium.
- Single Premium for Base Policy: Premium charged for the base policy after applicable adjustments, excluding rider premium and tax.
- Total Single Premium: Base-policy single premium plus rider premium, if selected, excluding tax.
That is why a simple calculator can show estimated benefits but cannot provide an exact single premium without LIC’s official rate chart or benefit illustration.
Death Benefit Under LIC Jeevan Utsav Single Premium Plan 883
On death after commencement of risk, LIC pays:
Higher of:
Basic Sum Assured
OR
1.25 × Tabular Single Premium

+ Accrued Guaranteed Additions
+ Unwithdrawn Flexi Income balance, if applicable
Under the Flexi Income option, any accumulated and unwithdrawn Flexi Income is also added to the death benefit.
The death benefit may be received as a lump sum or in instalments over 5, 10, or 15 years if that option is selected under the policy.
Maturity Benefit Under Plan 883
Maturity occurs when the Life Assured reaches age 100.
LIC pays:
Higher of:
Basic Sum Assured
OR
1.25 × Tabular Single Premium

+ Accrued Guaranteed Additions
+ Unwithdrawn Flexi Income balance, if applicable
Under Regular Income, the yearly income payments are received separately before maturity. Under Flexi Income, the accumulated unpaid income balance is added at maturity if it has not been withdrawn earlier.
Special Rule for Children Below Age 8
For a Life Assured below age 8 at entry, risk cover does not start immediately.
Risk begins on whichever is earlier:
- Two years from policy commencement, or
- The policy anniversary immediately following attainment of age 8.
If death happens before risk starts, LIC returns the single premium paid, excluding taxes, extra premium, and rider premiums. The policy automatically vests in the Life Assured after completion of age 18.
Surrender Value
The policy can be surrendered during the policy term. LIC pays the higher of:
- Guaranteed Surrender Value plus surrender value of accrued Guaranteed Additions, or
- Special Surrender Value.
During the first three policy years, the Guaranteed Surrender Value is 75% of eligible Single Premium Paid. Thereafter, the calculation differs by income option:
- Under Regular Income, it is 90% of eligible Single Premium Paid, reduced by Regular Income Benefits due and paid up to surrender.
- Under Flexi Income, it is 90% of eligible Single Premium Paid, reduced by Flexi Income Benefits due up to surrender according to the policy formula. The accumulated Flexi Income due and not withdrawn is then payable separately.
Taxes, underwriting extra premium and rider premium are excluded from the eligible Single Premium used in this calculation.
The surrender value of Guaranteed Additions is calculated separately:
Surrender Value of Accrued Guaranteed Additions =
Accrued Guaranteed Additions × Applicable GA Surrender Factor
The factor depends on the policy year. For surrender during a policy year, Guaranteed Addition is considered proportionately for completed months. Therefore, a calculator cannot show the exact surrender value without the applicable factors and complete policy details.
For Flexi Income, the accumulated unwithdrawn Flexi Income balance is also payable on surrender. Rider premiums do not receive surrender value.
Policy Loan Facility
A policy loan can be taken after three months from policy issuance or after completion of the free-look period, whichever is later.
During the Guaranteed Addition Period, the maximum loan is based on surrender value:
| GA Period | Maximum Loan as % of Surrender Value |
| 7 to 10 years | 60% |
| 11 to 14 years | 50% |
| 15 to 17 years | 40% |
After the GA Period, loan eligibility is linked to the annual income benefit and surrender value. LIC also recovers outstanding loan and interest from policy proceeds when required.
An exact loan amount also depends on the policy year, official surrender value, income benefit, outstanding loan and LIC’s applicable loan-interest conditions. A calculator result is only indicative unless these details are entered.
Optional Riders Available
Two riders may be selected at policy inception by paying an additional premium.
| Rider | Main Purpose |
| LIC Accidental Death and Disability Benefit Rider | Extra benefit for accidental death or accidental disability, subject to rider terms |
| LIC New Term Assurance Rider | Additional term cover during the rider term |
The accidental rider can provide accident death benefit in lump sum and disability benefit in monthly instalments, subject to eligibility. The term rider gives additional death cover during its rider term. Combined life rider premiums cannot exceed 30% of base policy premium, and rider Sum Assured cannot exceed Basic Sum Assured.
Important Policy Rules
The policyholder receives a 30-day free-look period from the date of receipt of the electronic or physical policy document, whichever is earlier. Because it is a single-premium policy, there is no regular premium due later, so grace period, lapse, paid-up value and revival provisions do not apply in the usual way.
In case of suicide within 12 months from commencement of risk, the nominee receives the higher of 80% of eligible single premium paid or the surrender value available on the date of death, subject to policy conditions.
Tax Rule
Tax deduction on the single premium and taxability of income, surrender, death or maturity receipts depend on the Income Tax Act provisions applicable to the policy and individual circumstances. These amounts should not automatically be treated as tax-free. The issue date, premium-to-Sum-Assured ratio and nature of the benefit can affect the result. Current rules should be checked with a qualified tax professional.
Who Should Consider Plan 883?
LIC Jeevan Utsav Single Premium Plan 883 may suit people who:
- Have a lump sum available for long-term insurance planning.
- Want life cover without yearly premium payments.
- Prefer guaranteed additions over market-linked returns.
- Need future annual income.
- Want the flexibility to accumulate income instead of withdrawing it.
- Are creating a long-term financial arrangement for a child or family member.
Who Should Avoid This Plan?
The plan may not suit people who:
- Need liquidity within a short period.
- Want high market-linked growth potential.
- Prefer small periodic premium payments.
- Need a pure term plan with maximum life cover for minimum premium.
- Cannot comfortably commit a large one-time amount.
A single-premium insurance plan should be selected only after comparing liquidity needs, existing insurance cover, family responsibilities, and long-term financial goals.
FAQs
Is LIC Jeevan Utsav Single Premium Plan 883 different from the older Jeevan Utsav plan?
Yes. Plan 883 is the single-premium version of LIC Jeevan Utsav. It has a separate UIN, separate premium structure, and different policy document.
What is the minimum Basic Sum Assured?
The minimum Basic Sum Assured is ₹5,00,000.
How much Guaranteed Addition does LIC give?
LIC provides ₹40 per ₹1,000 Basic Sum Assured every year during the selected Guaranteed Addition Period.
When does income start?
Income starts from the end of the policy year immediately after the selected GA Period. For example, a 10-year GA Period starts income from the end of the 11th policy year.
What is the difference between Regular Income and Flexi Income?
Regular Income is paid directly every year. Flexi Income can remain accumulated at 5.5% yearly compounding, with withdrawal permitted once per policy year up to 75% of the accumulated balance.
Does the calculator show the exact premium and benefits?
No. Exact premium depends on official LIC Tabular Single Premium, age, GA Period, available rebates, underwriting, riders and taxes. Without Tabular Single Premium, death and maturity results use Basic Sum Assured as the minimum benefit basis.
Can the policy be surrendered or used for a loan?
Yes. Surrender value is payable according to LIC’s Guaranteed Surrender Value and Special Surrender Value rules.
Loan is also available after the prescribed waiting period, subject to surrender value and policy conditions.
Conclusion
LIC Jeevan Utsav Single Premium Plan 883 is a one-time premium whole-life insurance plan that combines life cover, Guaranteed Additions and yearly income options. The calculator helps estimate the benefit structure clearly, especially the GA amount, income start year, annual income and minimum maturity-benefit basis.
Before purchase, always check LIC’s official benefit illustration for the exact single premium, Tabular Single Premium, death benefit, maturity benefit, rider cost, tax treatment, and surrender value.