LIC New Jeevan Shanti Plan 858 Calculator
Plan Name: LIC’s New Jeevan Shanti Plan No.: 858 UIN: 512N338V04 Launch Date: 05.01.2023 Withdrawal Date: 07.02.2024 Plan Type: Non-Linked, Non-Participating, Individual, Single Premium, Deferred Annuity
Advanced Death, Surrender & Loan Planner
Optional fields for death benefit, surrender value, installment and loan estimates.
✅ Your Annuity Estimate
| Mode | Per Installment | Annual Equivalent |
|---|
The LIC New Jeevan Shanti Plan 858 Calculator helps existing policyholders estimate annuity, surrender value and possible loan eligibility. It uses details such as purchase price, annuity rate, deferment period, payment mode and policy year to explain the main policy values.
Plan 858 is withdrawn from new sale. This guide applies to policies issued under the V04 terms. LIC’s current New Jeevan Shanti product uses Plan 758, so Plan 758 and Plan 858 should not be calculated using the same annuity-rate table.
Check the original policy schedule before using the calculator. Enter the issued annuity rate for the closest possible estimate.
The calculator is an educational tool and does not replace LIC’s official quotation, policy schedule, surrender quotation or loan statement.
Table of Contents
LIC New Jeevan Shanti Plan 858 Quick Fact
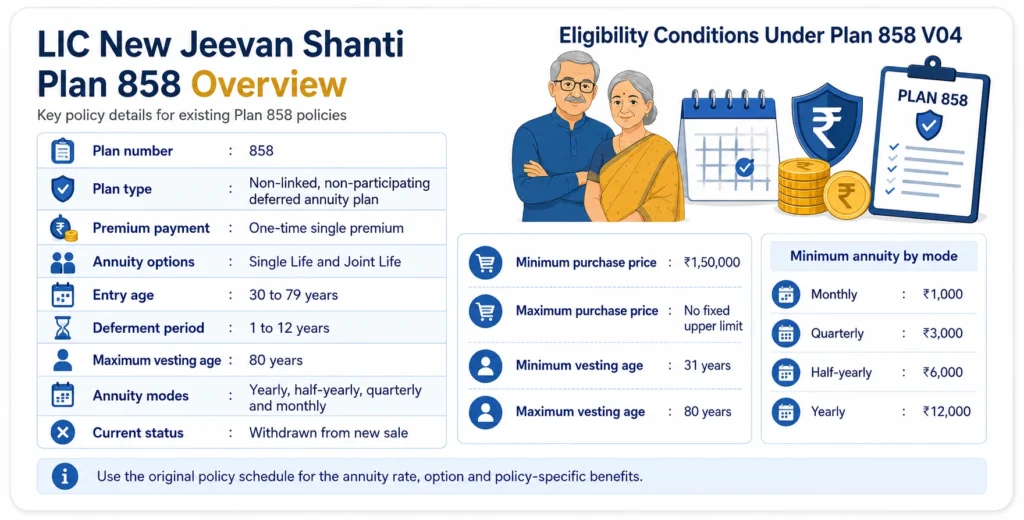
| Feature | Plan details |
|---|---|
| Plan name | LIC New Jeevan Shanti |
| Plan number | 858 |
| Plan type | Non-linked, non-participating deferred annuity plan |
| Premium payment | One-time single premium |
| Annuity options | Single Life and Joint Life |
| Entry age | 30 to 79 years |
| Deferment period | 1 to 12 years |
| Maximum vesting age | 80 years |
| Annuity modes | Yearly, half-yearly, quarterly and monthly |
| Surrender facility | Available during the policy term |
| Loan facility | Available subject to policy conditions |
| Current status | Withdrawn from new sale |
The policy offered two annuity choices: Single Life for one annuitant and Joint Life for two eligible family members. The annuity option selected at policy purchase cannot be changed later.
What Is LIC New Jeevan Shanti Plan 858?
LIC New Jeevan Shanti Plan 858 is a single-premium deferred annuity plan. A single premium means the Purchase Price is paid once at the beginning. There are no regular yearly or monthly base-premium payments. A deferred annuity means pension does not start immediately. It begins after the selected deferment period.
For example, if a person purchases the policy at age 45 and selects a 10-year deferment period, pension begins after the deferment period ends. The actual annuity depends on age, purchase price, annuity option, deferment period, payment mode and the official annuity rate fixed at policy issue. This plan is non-linked, so it is not connected with stock-market performance. It is also non-participating and does not receive a bonus or share in LIC’s profits.
Key Features of LIC New Jeevan Shanti Plan 858
- Single premium payment: The full Purchase Price is paid once at the beginning. No regular premium is required later.
- Deferred pension: Annuity begins only after the selected deferment period.
- Single Life and Joint Life options: Pension can cover one annuitant or continue for two eligible family members.
- Fixed annuity rate: The applicable rate is fixed when the policy is issued and does not depend on stock-market performance.
- Flexible deferment period: The V04 terms allowed a deferment period from 1 to 12 years, subject to the maximum vesting age.
- Multiple pension modes: Annuity can be received monthly, quarterly, half-yearly or yearly.
- Surrender facility: The policy can be surrendered during the policy term according to the applicable rules.
- Policy loan facility: A loan may be available after the required waiting period, subject to surrender value and LIC’s conditions.
- Joint Life continuation: Under Joint Life, the full annuity continues to the surviving annuitant after the first death.
- Non-linked and non-participating: The plan is not connected to market performance and does not receive a bonus or share in LIC’s profits.
These features apply to policies issued under the relevant Plan 858 terms. The original policy schedule remains the final reference for the annuity rate, option and policy-specific benefits.
Also Check:
- LIC New Jeevan Shanti Plan Calculator
- LIC Pension Plans Calculator
- LIC Jeevan Shanti Plan 850 Calculator
How to Use the LIC New Jeevan Shanti Plan 858 Calculator
- Confirm the plan version in the policy schedule.
- Enter the original Purchase Price.
- Enter the annuitant’s age at policy commencement.
- Select Single Life or Joint Life.
- Enter the deferment period.
- Select the annuity payment mode.
- Enter the issued annuity rate.
- Enter the current policy year and annuity already payable, where required.
- Select Calculate.
- Compare the result with the policy schedule or LIC quotation.
The exact annuity cannot be calculated from purchase price alone. LIC rates vary according to age, annuity option, deferment period, purchase-price slab and policy version.
How to Read the Calculator Result
Annuity Amount
The estimated annuity is based on the issued rate, Purchase Price and selected payment mode.
Surrender Value
The calculator may show an estimated Guaranteed Surrender Value. The final amount may be higher if LIC’s Special Surrender Value is more favourable.
Loan Eligibility
The result shows the maximum possible loan before applying LIC’s current interest rate and approval conditions.
Pension Start Date
The calculator may show the vesting age and expected first payment date according to the deferment period and selected payment mode.
Eligibility Conditions Under Plan 858
| Condition | Rule |
| Minimum purchase price | ₹1,50,000 |
| Maximum purchase price | No fixed upper limit |
| Minimum entry age | 30 years |
| Maximum entry age | 79 years |
| Minimum vesting age | 31 years |
| Maximum vesting age | 80 years |
| Minimum deferment period | 1 year |
| Maximum deferment period | 12 years |
The Purchase Price also had to be sufficient to produce the minimum annuity required for the selected payment mode.
| Annuity mode | Minimum annuity |
| Monthly | ₹1,000 per month |
| Quarterly | ₹3,000 per quarter |
| Half-yearly | ₹6,000 per half-year |
| Yearly | ₹12,000 per year |
For an eligible dependent person with disability under the specified arrangement, a lower minimum Purchase Price could apply subject to the policy conditions.
Single Life vs Joint Life Annuity
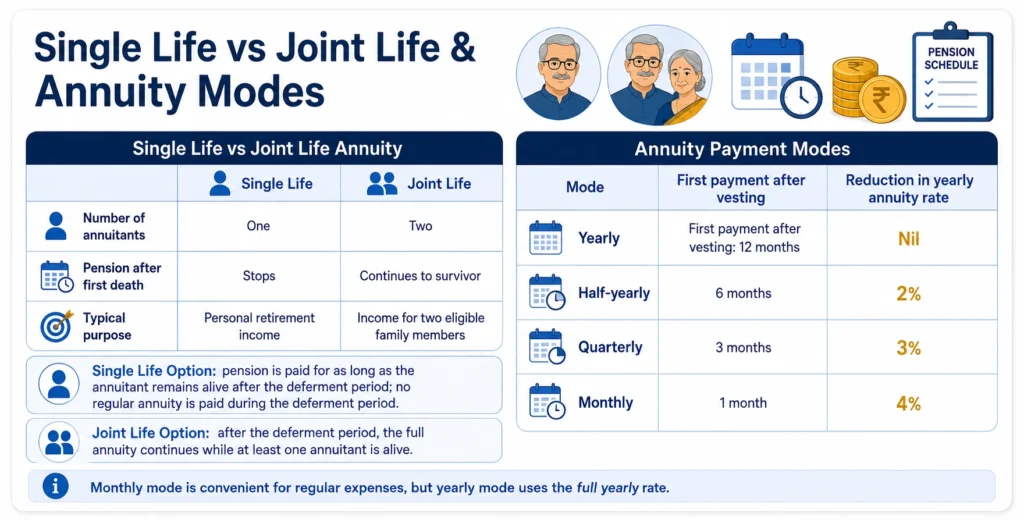
| Point | Single Life | Joint Life |
| Number of annuitants | One | Two |
| Pension after first death | Stops | Continues to survivor |
| Typical purpose | Personal retirement income | Income for two eligible family members |
Single Life Option
Under Single Life, pension is paid for as long as the annuitant remains alive after the deferment period.
During the deferment period, no regular annuity is paid.
Joint Life Option
Joint Life covers a primary annuitant and a secondary annuitant.
After the deferment period, the full annuity continues while at least one annuitant is alive. If one annuitant dies, the surviving annuitant continues receiving pension according to the policy terms.
The option could be selected for eligible family relations such as spouses, siblings and specified lineal ascendants or descendants.
Annuity Payment Modes
The annuity can be received yearly, half-yearly, quarterly or monthly. Payments are made in arrears.
| Mode | First payment after vesting | Reduction in yearly annuity rate |
| Yearly | 12 months | Nil |
| Half-yearly | 6 months | 2% |
| Quarterly | 3 months | 3% |
| Monthly | 1 month | 4% |
Monthly pension may be more convenient for regular expenses, but it uses the highest reduction in the annual annuity rate.
Yearly mode applies the full yearly rate, but the first payment becomes due after one year from vesting.
LIC New Jeevan Shanti Plan 858 Surrender Value Calculator
The surrender-value section is useful for existing policyholders who are considering closing the policy.
Plan 858 can be surrendered during the policy term. Surrender permanently ends future annuity and other policy rights after the surrender value is paid.
LIC pays the higher of:
- Guaranteed Surrender Value; or
- Special Surrender Value.
The Guaranteed Surrender Value formula is:
Guaranteed Surrender Value = GSV Factor × Purchase Price − Total annuity amount payable up to surrender
| Policy year | Guaranteed Surrender Value factor |
| Year 1 | 75% |
| Year 2 | 75% |
| Year 3 | 75% |
| Year 4 | 90% |
| Year 5 and above | 90% |
Special Surrender Value is reviewed by LIC from time to time. Therefore, the calculator can show the guaranteed amount, but the final payable value may be higher when Special Surrender Value is more favourable.
Outstanding loan, interest and any recoverable amount may be deducted before the final payment.
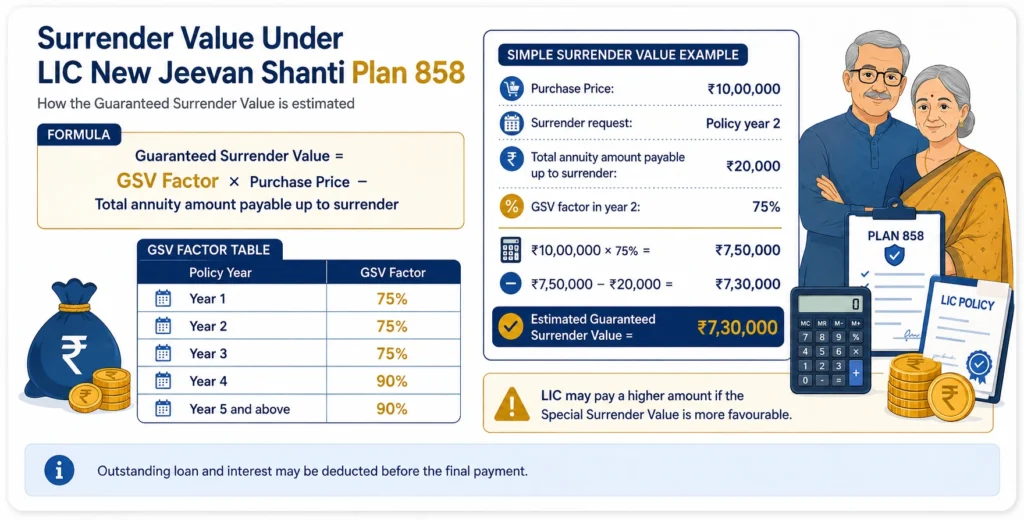
Simple Surrender Value Example
Assume:
- Purchase Price: ₹10,00,000
- Surrender request: Policy year 2
- Total annuity amount payable up to surrender: ₹20,000
The GSV factor in year 2 is 75%.
₹10,00,000 × 75% = ₹7,50,000
After deducting the total annuity amount payable:
₹7,50,000 − ₹20,000 = ₹7,30,000
The estimated Guaranteed Surrender Value is ₹7,30,000.
LIC may pay a higher amount if the Special Surrender Value is more favourable.
Loan Facility in LIC New Jeevan Shanti Plan 858
A policy loan may be available after three months from policy issuance or after the Free Look Period ends, whichever is later.
The maximum loan is subject to two main limits:
Maximum loan cannot exceed 80% of surrender value
and
Annual loan interest cannot exceed 50% of annual annuity
The available loan is therefore based on surrender value, not directly on the original Purchase Price.
Under Joint Life, the primary annuitant normally applies for the loan. The secondary annuitant may use the facility in situations permitted under the policy terms.
LIC decides the applicable loan interest rate when the loan is granted. The current rate should be confirmed before borrowing.
Outstanding loan and accrued interest may reduce the amount payable under the policy.
Important Points for Existing Policyholders
Plan 858 is a one-time Purchase Price policy and not a regular-premium plan.
The annuity option and rate were fixed when the policy was issued. These details should be taken from the original policy schedule.
Taxes were charged separately and did not increase the annuity or surrender value.
The calculator should be used for understanding policy values. Final surrender, loan and payment figures must be checked with LIC.
Frequently Asked Questions
Is LIC New Jeevan Shanti Plan 858 still available for new purchase?
No. Plan 858 is withdrawn from new sale. Existing policies continue according to their issued terms.
Is the Plan 858 calculator fully accurate?
It can provide a close estimate when the original annuity rate and policy details are entered. Without the issued rate, it should be treated only as a planning estimate.
How is surrender value calculated?
LIC pays the higher of Guaranteed Surrender Value and Special Surrender Value. The guaranteed value is based on the Purchase Price, GSV factor and annuity amount payable up to surrender.
Can a loan be taken against this policy?
Yes, subject to surrender value and LIC’s loan conditions. The maximum loan is capped according to the policy limits.
What happens after the first death under Joint Life?
The annuity continues to the surviving annuitant according to the policy terms.
What is the minimum Purchase Price?
The normal minimum was ₹1,50,000, subject to the minimum annuity condition. A different minimum could apply under specified disability-related conditions.
Which details should be taken from the policy schedule?
Use the original Purchase Price, annuity option, annuity rate, deferment period, payment mode, vesting date and annuitant details.
Conclusion
The LIC New Jeevan Shanti Plan 858 Calculator helps existing policyholders estimate annuity, surrender value and possible loan eligibility using the details recorded in the policy schedule.
The most important input is the original annuity rate. Without this rate, the calculator cannot reproduce the issued pension accurately.
Before making a surrender or loan decision, compare the calculator result with the official policy schedule and a current quotation from LIC.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.