LIC Jeevan Lakshya Plan 933 Calculator
Plan Type: Non-linked, Participating, Endowment Plan
Launch Date: 1st February 2020
Withdrawal Date: 1st October 2024
UIN: 512N297V02
Entry Age: 18-50 years | Maturity Age: Max 65 years
Policy Term: 13-25 years | PPT: Policy Term - 3 years
Calculation Results
Estimated figures based on selected inputs and assumptions.
Policy Summary
Selected age, policy term and premium period.
Premium Breakdown
Premium estimate before GST and rider charges.
Maturity Projection
Bonus values are estimates and not guaranteed.
Family Protection Illustration
Death benefit figures are estimated for an in-force policy. Actual claim is subject to LIC policy terms, premium status and official claim calculation.
What is LIC Jeevan Lakshya Plan 933?
LIC Jeevan Lakshya Plan 933 is a participating, non-linked savings and life insurance plan created for long-term family financial protection. Along with a maturity benefit, it has a special death-benefit structure that can provide annual income to the family for the remaining policy term and a lump-sum payment on the maturity date.
Plan 933 carries UIN 512N297V02. LIC launched this version on 1 February 2020 and withdrew it from new business on 1 October 2024. It is therefore relevant only to existing policyholders whose policy bond shows Plan No. 933 and the same UIN.
The LIC Jeevan Lakshya Plan 933 Calculator helps estimate premium commitment, maturity benefit, Annual Income Benefit and the final lump sum payable after death. Results are illustrative because future bonuses, Final Additional Bonus, underwriting decisions, taxes, riders and the actual status of the policy can change the final amount paid by LIC.
Table of Contents
What Is the LIC Jeevan Lakshya Plan 933 Calculator?
The LIC Jeevan Lakshya Plan 933 Calculator is an estimation tool for understanding the possible premium and benefits under this withdrawn policy. It brings the important calculations into one place and separates guaranteed policy components from bonus-based projections.
The calculator can automatically determine the Premium Paying Term, estimate the base premium, project the maturity benefit and explain how the family benefit may work if the life assured dies before maturity. It is particularly useful because Jeevan Lakshya does not pay its entire death benefit as one immediate lump sum. Part of the benefit is paid annually, while another part is due on the original maturity date.
The calculator is not an official LIC quotation or claim statement. Existing policyholders should use the premium shown on the policy bond and the vested bonus information available in their LIC records whenever those details are available.
Also Check:
LIC Jeevan Lakshya Plan 933 at a Glance
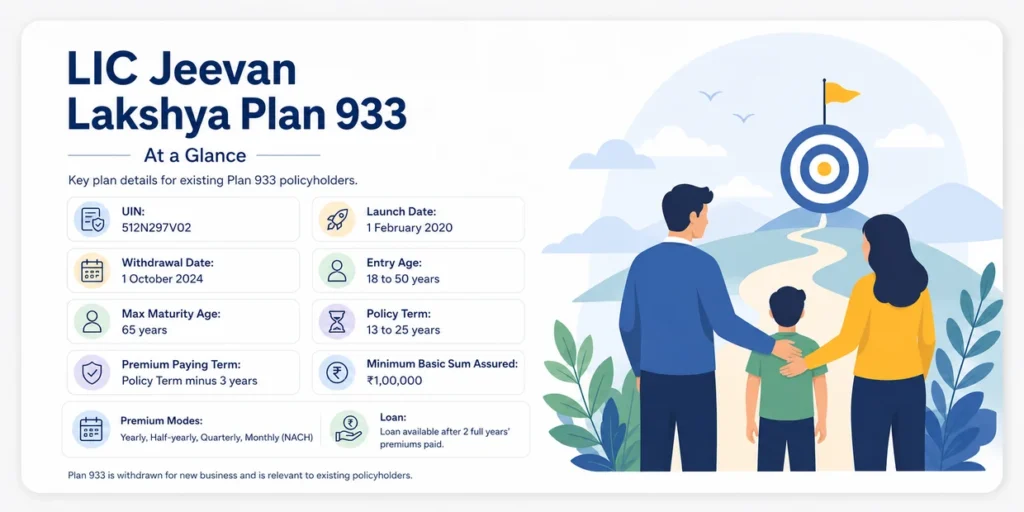
| Feature | Plan Details |
|---|---|
| Plan number and UIN | 933; 512N297V02 |
| Plan type | Participating, non-linked, individual life assurance savings plan |
| Launch and withdrawal | 1 February 2020; 1 October 2024 |
| Entry age | 18 to 50 years |
| Maximum maturity age | 65 years |
| Policy term | 13 to 25 years |
| Premium Paying Term | Policy Term minus 3 years |
| Minimum Basic Sum Assured | ₹1,00,000, in multiples of ₹10,000 |
| Premium modes | Yearly, half-yearly, quarterly and monthly through NACH; salary deduction was also permitted |
| Loan facility | Available after at least two full years’ premiums have been paid |
The maximum policy term available to an individual also depends on the maximum maturity age. For example, a person entering at age 50 cannot select a 20-year term because the maturity age would exceed 65.
Highlights of the Calculator
This calculator is useful because it can:
- identify the Premium Paying Term automatically;
- show an illustrative premium commitment for the selected term and Basic Sum Assured;
- project maturity using an adjustable bonus assumption;
- estimate the annual family income payable after death;
- show the lump sum that may become payable on the maturity date; and
- keep guaranteed amounts separate from non-guaranteed bonus projections.
These results make it easier to understand the policy structure, but they should not be treated as a guarantee of premium, bonus, surrender value or claim amount.
How to Use the LIC Jeevan Lakshya Plan 933 Calculator
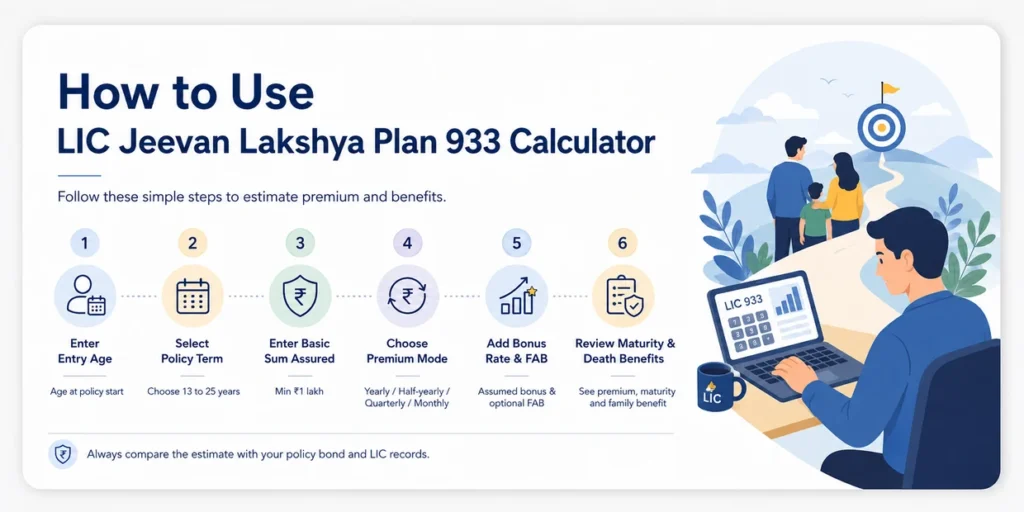
First, enter the age at which the policy began. LIC calculates age on an age-nearer-birthday basis, except as provided in the policy conditions. Next, select a policy term from the options allowed for that entry age. The calculator will determine the Premium Paying Term by subtracting three years from the policy term.
Enter the Basic Sum Assured shown on the policy bond. The minimum under Plan 933 was ₹1 lakh, and higher amounts had to be in multiples of ₹10,000. Select the premium-payment mode used under the policy.
For the maturity projection, enter an assumed Simple Reversionary Bonus rate per ₹1,000 of Basic Sum Assured. If the calculator includes Final Additional Bonus, enter an estimated FAB amount or an assumed rate in the unit clearly stated by the calculator. FAB should not be treated as a fixed percentage or guaranteed benefit.
To preview the death benefit, choose the policy anniversary on which death is assumed to occur. This timing is important because the number of Annual Income Benefit payments depends on the policy anniversary coinciding with or immediately following death.
After selecting Calculate Benefits, review the premium estimate, maturity projection and death-benefit illustration. Compare the result with the policy bond, premium receipts and vested bonus record before using it for financial decisions.
Formulas Used in the Calculator
Premium Paying Term
Premium Paying Term = Policy Term − 3 yearsA 20-year policy therefore has a Premium Paying Term of 17 years.
Estimated Maturity Benefit
For an in-force policy, the maturity benefit is:
Maturity Benefit = Basic Sum Assured
                 + Vested Simple Reversionary Bonuses
                 + Final Additional Bonus, if any
The Basic Sum Assured is the guaranteed maturity component, subject to the policy remaining in force. Future Simple Reversionary Bonuses and FAB are not guaranteed. Once a Simple Reversionary Bonus is declared and vested, it remains attached to the policy under the applicable conditions.
An illustrative annual bonus can be estimated as:
Annual Bonus = (Basic Sum Assured ÷ 1,000) × Assumed Bonus RateIf the same assumed rate is used for the complete term:
Projected Bonus = Annual Bonus × Policy TermThis is only a projection. LIC may declare different bonus rates in different years.
Death Benefit
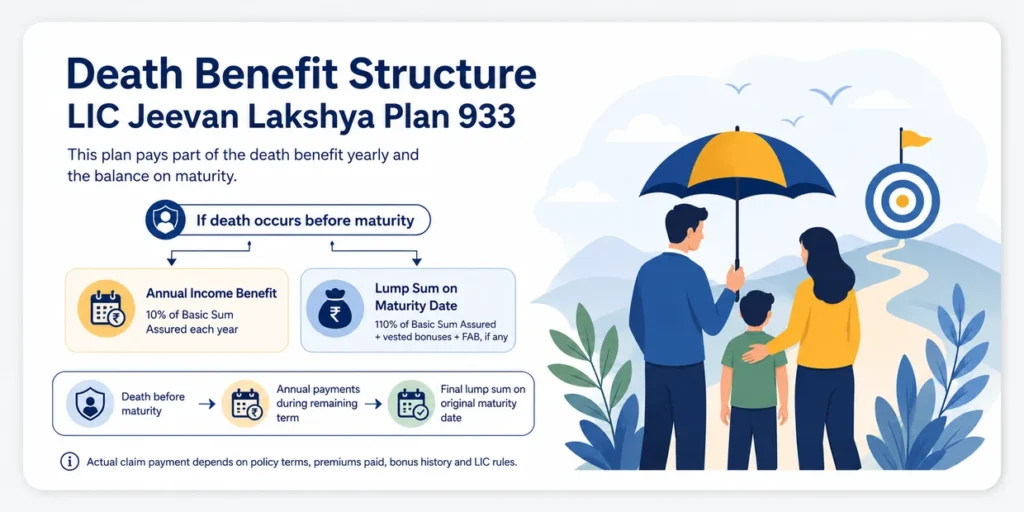
For an in-force policy, the benefit structure includes:
Annual Income Benefit = 10% of Basic Sum Assured each yearThis annual amount is payable from the policy anniversary coinciding with or following the date of death until the policy anniversary immediately before maturity.
The lump sum payable on the original maturity date includes:
110% of Basic Sum Assured
+ Vested Simple Reversionary Bonuses
+ Final Additional Bonus, if any
The official Sum Assured on Death is also subject to the higher-of condition involving seven times the annualised premium. In addition, the total death benefit cannot be less than 105% of total premiums paid up to death, as defined in the policy. Taxes, rider premiums and extra premiums are excluded from that 105% test.
LIC Jeevan Lakshya Plan 933 Calculation Example
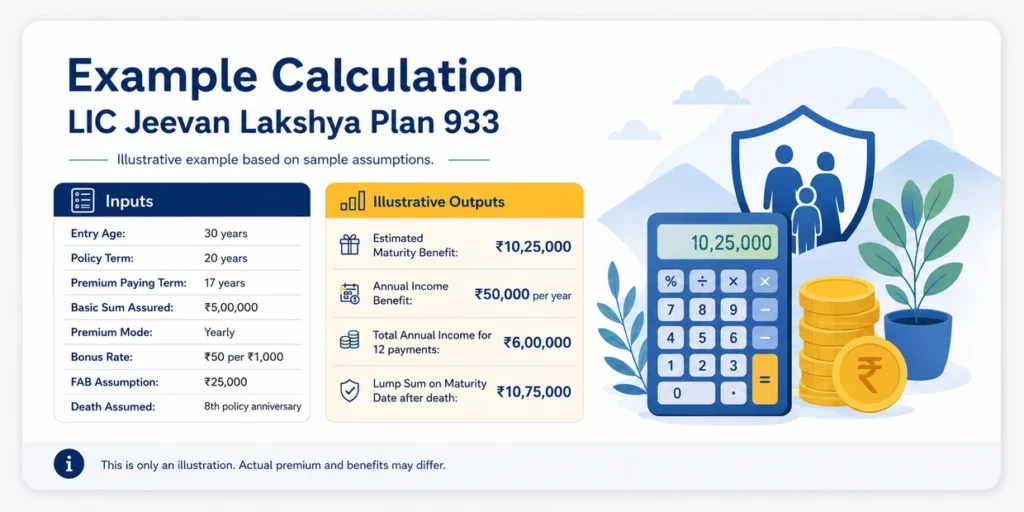
Consider an illustrative policy with these details:
- Age at entry: 30 years
- Policy term: 20 years
- Premium Paying Term: 17 years
- Basic Sum Assured: ₹5,00,000
- Premium mode: yearly
- Assumed bonus rate: ₹50 per ₹1,000 of Basic Sum Assured per year
- Assumed FAB amount: ₹25,000
Illustrative Premium Estimate
LIC’s sample premium table showed an annual premium of ₹5,718 for a 30-year-old, a 20-year policy term and ₹1 lakh Basic Sum Assured, excluding taxes. Scaling that sample to ₹5 lakh gives a starting tabular-premium estimate of ₹28,590 before the applicable rebate assumptions.
If the calculator applies an assumed high-sum-assured rebate of ₹3 per ₹1,000, the estimated rebate is ₹1,500. It may also apply the yearly-mode rebate according to the method built into the calculator.
Using the calculator’s illustrative assumptions, the annual base premium may be shown at approximately ₹26,518 and the total base premium over 17 years at approximately ₹4,50,809. These figures are not an LIC quotation. GST, rider premium, medical loading, extra premium and any difference in the applicable premium calculation are not included.
Illustrative Maturity Benefit
The projected Simple Reversionary Bonus is:
(₹5,00,000 ÷ 1,000) × ₹50 × 20
= ₹5,00,000
Using the assumed FAB amount of ₹25,000:
Estimated Maturity Benefit
= ₹5,00,000 Basic Sum Assured
+ ₹5,00,000 projected bonus
+ ₹25,000 assumed FAB
= ₹10,25,000
The ₹10.25 lakh result is an illustration, not a promised maturity amount. The actual benefit will depend on bonuses declared by LIC and the status of the policy.
Death-Benefit Illustration
Assume death occurs exactly on the eighth policy anniversary of this 20-year policy. The Annual Income Benefit would be:
10% of ₹5,00,000 = ₹50,000 per yearIt would be payable from the eighth through the nineteenth policy anniversary, resulting in 12 payments:
₹50,000 × 12 = ₹6,00,000The illustrative lump sum payable on the original maturity date would be:
110% of ₹5,00,000 = ₹5,50,000

₹5,50,000
+ ₹5,00,000 projected bonus
+ ₹25,000 assumed FAB
= ₹10,75,000
The combined nominal value in this illustration is ₹16,75,000. This simply adds the 12 annual payments and the projected maturity-date lump sum; it is not a present-value calculation or an investment return.
For this illustration, the same bonus rate is projected for the complete term because an in-force policy continues participating in profits after the death of the life assured until maturity. Actual future bonuses can differ from the assumed rate. LIC’s final claim calculation must also apply the policy’s seven-times-annualised-premium comparison and 105% minimum-benefit condition.
What Happens if Premiums Are Not Paid?
Plan 933 allowed a grace period of 30 days for yearly, half-yearly and quarterly premiums and 15 days for monthly premiums. The policy remained in force during this period. If death occurred during the grace period, applicable benefits could be paid after deducting the unpaid premium and other amounts permitted under the contract.
If the premium remained unpaid after the grace period, the policy lapsed. Where fewer than two full years’ premiums had been paid, normal policy benefits generally ceased after the grace period. After at least two full years’ premiums had been paid, the policy could continue as a reduced paid-up policy.
Paid-Up Value
The maturity paid-up sum assured is calculated broadly as:
Maturity Paid-Up Sum Assured = Basic Sum Assured
× (Period for which premiums were paid ÷ Original Premium Paying Term)
The 110% maturity-date death component and Annual Income Benefit are reduced using the corresponding paid-up ratio. Vested Simple Reversionary Bonuses remain attached, but no future bonuses accrue after the policy becomes paid-up. Final Additional Bonus is not payable under a reduced paid-up policy, and riders do not acquire a paid-up value.
Revival, Surrender and Policy Loan
A lapsed policy could be considered for revival within five consecutive years from the first unpaid premium and before maturity. Revival was subject to payment of arrears with applicable interest, evidence of continued insurability and LIC’s approval.
The policy could be surrendered after at least two full years’ premiums had been paid. LIC pays the higher of the Guaranteed Surrender Value and Special Surrender Value. The amount depends on the policy term, surrender year, premiums paid and vested bonuses. A single fixed surrender percentage cannot accurately represent every Plan 933 policy.
A loan was available after at least two full years’ premiums had been paid. The maximum was up to 90% of surrender value for an in-force policy and up to 80% for a paid-up policy. LIC could recover the outstanding loan and interest from the applicable policy benefits.
Optional Riders and Instalment Benefits
Plan 933 offered Accidental Death and Disability Benefit, Accident Benefit, New Term Assurance and New Critical Illness Benefit riders for an additional premium, subject to eligibility and rider conditions. Only one of the two accident riders could be chosen, and a maximum of three riders could be attached to one policy.
The lump-sum portion of the death benefit payable on the maturity date could be taken in instalments over 5, 10 or 15 years if the required option had been exercised. The Annual Income Benefit itself could not be converted through this option. The maturity benefit also had a Settlement Option for payment over 5, 10 or 15 years, subject to LIC’s conditions and minimum instalment requirements.
Important Limitations of the Calculator
The result may differ from LIC’s final figure because the calculator cannot independently confirm medical underwriting, extra premium, rider cover, policy assignments, outstanding loans, unpaid premiums, actual bonus history or claim conditions. An assumed bonus rate should never be presented as an assured return.
For an existing policy, the policy bond, LIC premium receipts, vested bonus record and servicing-branch statement should take priority over a generic online estimate.
Frequently Asked Questions
Is LIC Jeevan Lakshya Plan 933 still available for purchase?
No. LIC withdrew Plan 933 from new business on 1 October 2024. Existing policies continue according to their contract terms, subject to premium payment and policy status.
What is the Premium Paying Term under Plan 933?
It is three years shorter than the policy term. For example, a 20-year policy has a Premium Paying Term of 17 years.
Is the maturity amount guaranteed?
The Basic Sum Assured is the guaranteed maturity component under an in-force policy. Future Simple Reversionary Bonuses and Final Additional Bonus are not guaranteed.
What is the Annual Income Benefit after death?
It equals 10% of the Basic Sum Assured each year. The number of payments depends on the date of death and the remaining anniversaries before maturity.
Can Plan 833 details be entered in this calculator?
No. Plan 833 carries a different UIN and should be calculated using its own policy terms and records.
Can a loan be taken under Plan 933?
Yes, after at least two full years’ premiums have been paid. The permissible amount depends on surrender value and whether the policy is in force or paid-up.
Final Words
LIC Jeevan Lakshya Plan 933 combines a maturity benefit with continued family support if the life assured dies during the policy term. Its Annual Income Benefit and maturity-date lump sum make its benefit structure more complex than that of a basic endowment policy.
The LIC Jeevan Lakshya Plan 933 Calculator simplifies this structure by estimating premium commitment, maturity benefit and family benefits under stated assumptions. Its result should be treated as a planning estimate and verified against the policy bond, actual vested bonuses, current policy status and LIC’s final calculation.