LIC Jeevan Amar Premium Calculator Plan 955, 855
Plan 855 and Plan 955 · Pure-risk term insurance
Select a plan to view its detailsPremium Estimate
| Plan Summary | |
|---|---|
| Plan and UIN | — |
| Policy status | — |
| Age at entry | — |
| Policy term | — |
| Age at maturity | — |
| Cover option | — |
| Basic Sum Assured | — |
| Premium Summary | |
|---|---|
| Payment type | — |
| Premium-paying term | — |
| Payment frequency | — |
| Base premium per payment | — |
| Tax per payment | — |
| Total premium per payment | — |
| Scheduled base premium | — |
| Estimated scheduled payment | — |
| Cover Summary | |
|---|---|
| Starting absolute cover | — |
| Maximum absolute cover | — |
| Maturity benefit | ₹0 |
View year-wise cover schedule
LIC Jeevan Amar is a pure term insurance plan. It gives life cover during the selected policy term. It is not a savings or investment plan.
The most important point is simple: if the life assured survives the full policy term, the normal maturity benefit is ₹0. Premiums are not returned only because the policy term has ended.
The LIC Jeevan Amar Premium Calculator helps estimate premium payments and understand the life-cover schedule. It supports the old Jeevan Amar Plan 855 and both UIN versions of New Jeevan Amar Plan 955. This is useful because the rules of one version should not be used for another version.
The calculator can use a base premium copied from a policy or official LIC quotation. For selected Plan 955 V02 cases, it can also use exact sample premiums published in LIC’s brochure. It does not guess a premium for a combination that is not available in the brochure.
Table of Contents
What Is the LIC Jeevan Amar Premium Calculator?
The LIC Jeevan Amar Premium Calculator is an educational tool. It calculates premium payments and shows the selected life cover.
After the correct plan and policy details are entered, it may show:
- base premium for one payment;
- tax amount, when a tax rate is entered;
- total premium for one payment;
- total number of planned payments;
- total planned base premium;
- Premium Paying Term;
- starting Absolute Cover;
- highest Absolute Cover under the increasing option;
- year-wise Absolute Cover schedule; and
- normal maturity benefit of ₹0.
The calculator is not LIC’s official quotation system. The final premium can change after LIC checks health, income, occupation, smoking status, lifestyle, medical reports and other details.
Important calculator limit: For most policy combinations, the calculator needs the base premium shown in an LIC quotation or policy document. It uses that amount to calculate payment totals and benefits. It can fill the premium automatically only for the exact Plan 955 V02 sample cases included from LIC’s brochure.
What Is LIC Jeevan Amar?
LIC Jeevan Amar is an individual term insurance plan. It covers one life assured. It is non-linked, so it is not connected to the stock market. It is also non-participating, so it does not earn LIC bonuses.
Its main benefit is the death benefit. If the life assured dies while valid cover is active, LIC pays the applicable amount under the policy rules. The plan family offers level and increasing death-cover choices.
There is no normal survival benefit, bonus, Loyalty Addition, Guaranteed Addition or maturity payment. Jeevan Amar should not be compared with endowment or money-back plans on the basis of maturity returns.
Plans Supported by the Calculator
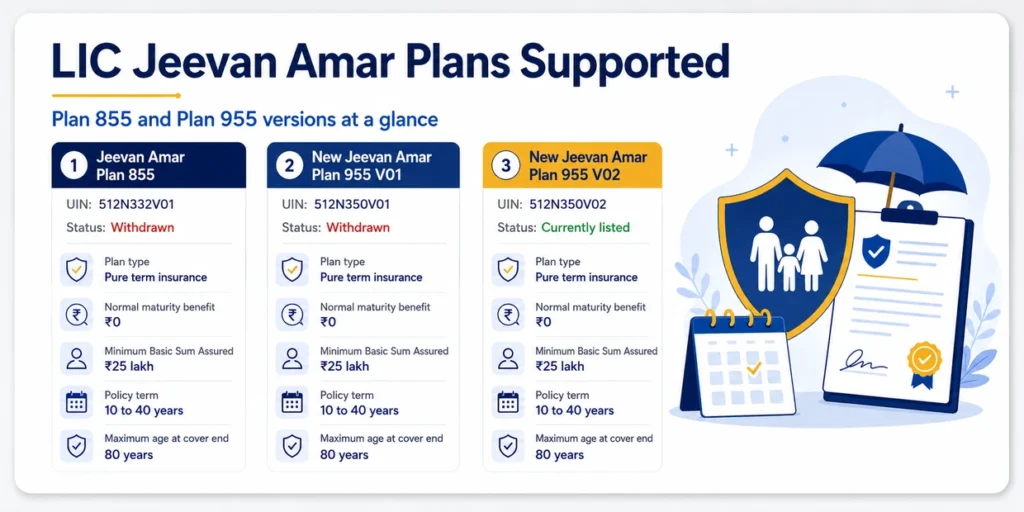
| Feature | Jeevan Amar Plan 855 | New Jeevan Amar Plan 955 V01 | New Jeevan Amar Plan 955 V02 |
|---|---|---|---|
| Plan number | 855 | 955 | 955 |
| UIN | 512N332V01 | 512N350V01 | 512N350V02 |
| Plan type | Pure term insurance | Pure term insurance | Pure term insurance |
| Status | Withdrawn | Withdrawn | Currently listed by LIC |
| Normal maturity benefit | ₹0 | ₹0 | ₹0 |
Plan 855 was launched on 5 August 2019 and withdrawn on 22 November 2022. The first Plan 955 version started on 23 November 2022. LIC now lists Plan 955 with UIN 512N350V02 among its term assurance plans.
An old policy continues under the UIN printed on its policy document. Plan 855 rates must not be mixed with Plan 955 rates. Plan 955 V01 and V02 must also be treated as separate versions.
LIC Jeevan Amar Plan 855
LIC Jeevan Amar Plan 855 carries UIN 512N332V01. It offered level and increasing death cover. Single, regular and limited premium payment choices were available under its rules.
Premium rates could differ for smokers and non-smokers. Separate rates also applied to female lives. The availability of non-smoker rates and any medical test depended on the Sum Assured and LIC’s underwriting rules. The death benefit could be paid as a lump sum, instalments or a permitted mix.
Plan 855 is closed to new sales, but an existing policy continues under its original contract. It does not provide a normal maturity benefit.
Read the detailed LIC Jeevan Amar Plan 855 guide.
LIC New Jeevan Amar Plan 955
New Jeevan Amar Plan 955 replaced the older Plan 855. The first version carries UIN 512N350V01. The revised version carries UIN 512N350V02.
Plan 955 is also pure term insurance. It offers premium-payment and death-cover choices. Premium depends on age, gender, smoking status, policy term, Sum Assured, health details and LIC’s final check. Non-smoker rates apply only when the policy conditions and LIC’s medical requirements are met.
The death benefit may be paid as a lump sum or through an available instalment option. The plan does not earn bonuses and does not provide a normal maturity payment.
Read the detailed LIC New Jeevan Amar Plan 955 guide.
Main Highlights of the Calculator
The calculator keeps the form simple. It shows only the fields needed for the selected option. For example, the UIN choice appears when Plan 955 is selected. Payment frequency is not needed for Single Premium because only one payment is made.
For Regular Premium, the calculator treats the Premium Paying Term as equal to the policy term. For Limited Premium, it shows the allowed payment periods. There is no need to work out the payment term manually.
The calculator also checks the entry age, age when cover ends, minimum Basic Sum Assured and allowed Sum Assured steps. Results stay hidden until valid details are entered and Calculate Premium is pressed.
It keeps premium and death cover separate from the ₹0 maturity benefit. This prevents the result from giving a false idea that premiums will be returned.
Two Ways to Calculate the Premium
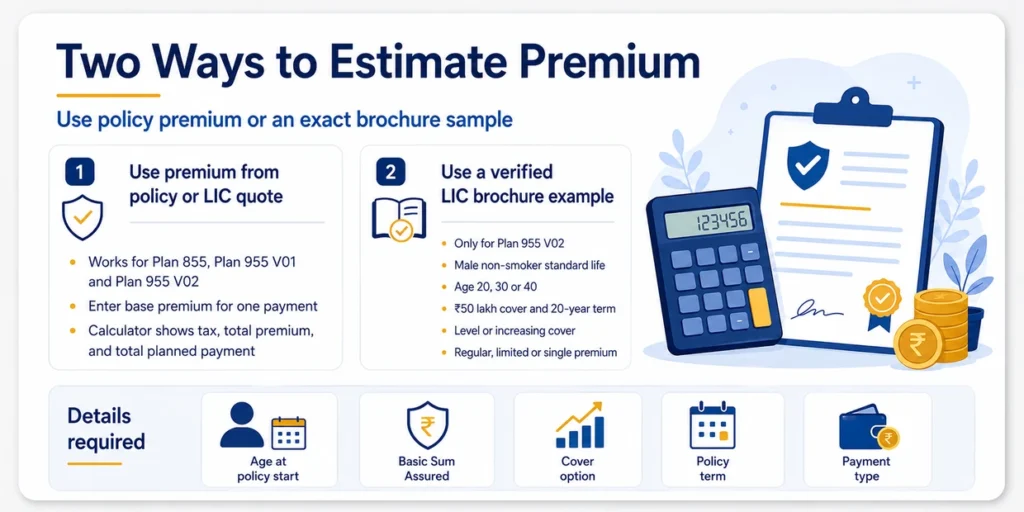
Use Premium from Policy or LIC Quote
This method works for Plan 855, Plan 955 V01 and Plan 955 V02. It is the best method for checking an existing policy or an official quotation.
Enter the base premium for one payment exactly as shown in the policy or quotation. Tax, rider premium and extra premium should not be included unless the document clearly combines them.
The calculator uses the entered amount to show tax, total premium per payment and total planned payment over the Premium Paying Term.
Use a Verified LIC Brochure Example
This method is available only for Plan 955 V02. It uses exact sample premiums from LIC’s brochure for these details:
- male non-smoker standard life;
- entry age 20, 30 or 40 years;
- Basic Sum Assured of ₹50 lakh;
- policy term of 20 years;
- level or increasing cover; and
- regular, limited or single premium.
The sample method works only for these exact combinations. It does not guess a rate for age 25, ₹70 lakh cover or another unsupported combination.
Details Required in the Calculator
Plan and UIN: Select the plan number and UIN shown on the policy or quotation. For the current Plan 955 estimate, select UIN 512N350V02.
Age at policy start: Enter the completed age when the policy began. For an old policy, do not enter the current age.
Basic Sum Assured: This is the starting life cover. The calculator accepts a minimum of ₹25 lakh. From ₹25 lakh to ₹40 lakh, enter the amount in steps of ₹1 lakh. Above ₹40 lakh, use steps of ₹10 lakh.
Cover option: Choose Level Cover or Increasing Cover.
Policy term: This is the number of years for which cover continues. The calculator removes a term when the age at the end of cover would go above the allowed limit.
Payment type: Select Single, Regular or Limited Premium. Single means one payment. Regular means payments continue for the full term. Limited means payments stop before the policy ends.
Payment frequency: For Regular and Limited Premium, select yearly or half-yearly payment.
Tax rate: This is optional. Leave it blank when tax should not be added to the estimate.
Formula Used in the LIC Jeevan Amar Premium Calculator
Tax Per Payment
When a tax rate is entered:
Tax per payment = Base premium per payment × Tax rate ÷ 100
Total premium per payment = Base premium per payment + Tax per payment
When the tax field is blank, the result shows that tax is not included.
Total Planned Premium
For yearly or half-yearly premiums:
Number of payments = Payments per year × Premium Paying Term
Total planned base premium = Base premium per payment × Number of payments
Estimated total payment = Total premium per payment × Number of payments
For Single Premium, the number of payments is one.
Option I: Level Sum Assured
Absolute Cover in every policy year = Basic Sum Assured
The Absolute Cover stays at the selected level during the policy term, subject to the policy rules.
Option II: Increasing Sum Assured
For policy years 1 to 5, cover stays equal to the Basic Sum Assured.
From policy year 6 to year 15:
Absolute Cover = Basic Sum Assured × [1 + 10% × (Policy year − 5)]
From policy year 16 onwards, the Absolute Cover stays at two times the Basic Sum Assured.
This schedule shows the Absolute Amount Assured to Be Paid on Death. It is not always the final death benefit because premium-based minimum benefit rules also apply.
Final Death Benefit
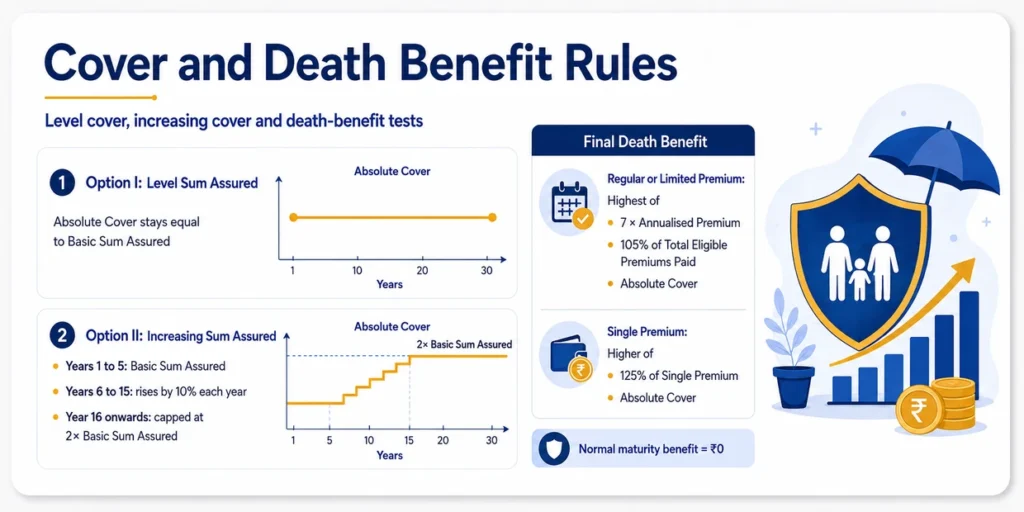
For a Regular or Limited Premium policy, the Sum Assured on Death is the highest of:
7 × Annualised Premium
105% of Total Eligible Premiums Paid up to the date of death
Absolute Amount Assured to Be Paid on Death
For a Single Premium policy, the Sum Assured on Death is the higher of:
125% of Single Premium
Absolute Amount Assured to Be Paid on Death
Annualised Premium does not include tax, rider premium, underwriting extra or modal loading. Total Eligible Premiums Paid also excludes tax, rider premium and underwriting extra.
How to Use the Calculator
- Select Plan 855 or Plan 955.
- For Plan 955, choose the UIN shown on the policy.
- Select the calculation method.
- Enter the age at policy start and Basic Sum Assured.
- Choose Level Cover or Increasing Cover.
- Select the policy term.
- Select Single, Regular or Limited Premium.
- For Limited Premium, select an available payment period.
- For Regular or Limited Premium, choose yearly or half-yearly payment.
- In policy-premium mode, enter the base premium for one payment.
- Add a tax rate only when required.
- Press Calculate Premium.
The result shows four small summary cards and detailed tables. Open View year-wise Absolute Cover schedule to see the amount for every policy year. This schedule is one part of the death-benefit calculation. Reset clears the form, and Print Result prints the displayed estimate.
Real Premium Calculation Example
Consider an exact sample from the Plan 955 V02 LIC brochure:
- male non-smoker standard life;
- entry age: 30 years;
- Basic Sum Assured: ₹50 lakh;
- policy term: 20 years;
- Option I: Level Sum Assured;
- Regular yearly premium; and
- tax not entered.
The published annual base premium for this sample is ₹7,830.
Regular Premium is selected, so the Premium Paying Term is 20 years. One payment is planned each year.
Number of payments = 1 × 20 = 20
Total planned base premium = ₹7,830 × 20 = ₹1,56,600
Tax is not entered. The base premium for each payment remains ₹7,830, and the total planned base premium remains ₹1,56,600.
Under Option I, the Absolute Cover stays at ₹50 lakh throughout the 20-year term.
The death-benefit tests are:
7 × Annualised Premium = ₹7,830 × 7 = ₹54,810
After all 20 annual premiums have been paid:
105% of Total Eligible Premiums Paid = ₹1,56,600 × 105% = ₹1,64,430
| Death-benefit test | Amount |
| 7 × Annualised Premium | ₹54,810 |
| 105% of premiums paid | ₹1,64,430 |
| Absolute Cover | ₹50,00,000 |
The highest amount is ₹50 lakh. Therefore, the death benefit in this example is ₹50 lakh while the policy remains in force.
If the life assured survives the full term:
Normal maturity benefit = ₹0
This does not mean that every 30-year-old will get the same final premium. The brochure sample applies only to the exact details above. Medical history, occupation, riders, tax and LIC’s final check can change the official amount.
Understanding the Calculator Result
Base premium is the amount before tax. It comes from the entered policy amount or an exact brochure sample.
Tax per payment appears only when a tax rate is entered. A blank field means tax was left out of the estimate.
Total planned base premium is the base premium multiplied by the planned number of payments. It assumes every payment is made and the policy does not change.
Starting Absolute Cover is the Basic Sum Assured. Under Option II, the highest Absolute Cover may become two times the Basic Sum Assured.
Final death benefit is found after comparing the Absolute Cover with the premium-based minimum amounts. The Absolute Cover schedule alone should not be treated as the final payable benefit.
Maturity benefit ₹0 means no payment is made only because the life assured survives the term. The plan still gave life cover while it was active.
Does LIC Jeevan Amar Have a Maturity Benefit?
No normal maturity benefit is paid when the life assured survives the complete policy term.
This means:
- normal maturity benefit is ₹0;
- premiums are not returned at the end;
- there is no survival benefit;
- there is no bonus;
- there is no Loyalty Addition; and
- there is no Guaranteed Addition.
Jeevan Amar is not a return-of-premium plan. Its purpose is life protection during the policy term.
Death Benefit Options
Under Option I: Level Sum Assured, the Absolute Cover stays equal to the Basic Sum Assured during the policy term.
Under Option II: Increasing Sum Assured, the Absolute Cover follows the fixed increase schedule. It cannot be changed freely every year.
The final Sum Assured on Death is found only after the Absolute Cover is compared with the other minimum benefit tests explained above.
The policy may allow the death benefit to be paid as one lump sum, instalments or a permitted mix. Instalments change the payment method. They do not increase the insured amount.
Main Premium Factors
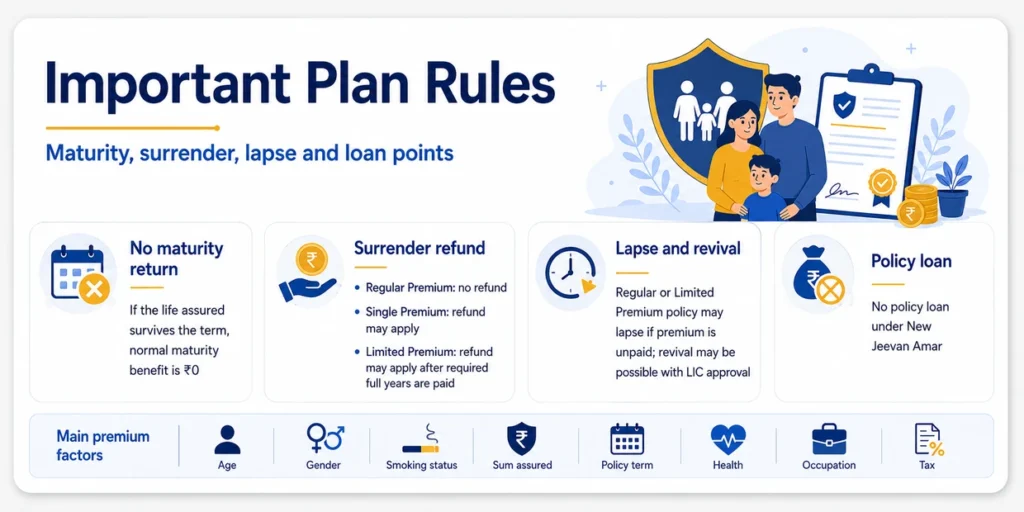
The premium can depend on entry age, gender, smoking status, Basic Sum Assured, policy term, Premium Paying Term, payment type, cover option, health, occupation and tax.
Correct information must be given to LIC. After checking the proposal, LIC may change the premium or terms, ask for medical tests, postpone the proposal or reject it.
Eligibility and Policy Limits
| Detail | Plan 855 | Plan 955 |
| Minimum entry age | 18 years | 18 years |
| Maximum entry age | 65 years | 65 years |
| Maximum age when cover ends | 80 years | 80 years |
| Policy term | 10 to 40 years | 10 to 40 years |
| Minimum Basic Sum Assured | ₹25 lakh | ₹25 lakh |
| Premium choices | Single, regular and limited | Single, regular and limited |
The available term and Premium Paying Term may be shorter at a higher entry age because cover cannot continue after the maximum allowed age. The selected option and UIN must also allow the combination.
Riders, Lapse and Revival
A rider is optional extra cover bought for an extra premium. Rider availability differs by plan and UIN. Every rider has its own limits, exclusions and claim rules.
A Regular or Limited Premium policy may lapse when a premium is not paid within the grace period. Cover may stop or change. Revival may be possible after payment of dues and interest, health proof and LIC approval.
Surrender Refund and Policy Loan
Jeevan Amar does not build savings like an endowment policy. Normal paid-up benefits do not apply in the same way as they do under a savings plan.
The surrender rules for New Jeevan Amar are:
- Regular Premium: Nothing is refunded on surrender.
- Single Premium: An applicable refund may be paid during the policy term.
- Limited Premium with a payment term below 10 years: A refund may apply after at least two full years’ premiums have been paid.
- Limited Premium with a payment term of 10 years or more: A refund may apply after at least three full years’ premiums have been paid.
LIC treats this as an applicable refund under stated conditions, not as a normal savings-based surrender value. The amount depends on the policy formula and remaining term. No policy loan is available under New Jeevan Amar. An older Plan 855 policy must be checked against its own policy document.
Tax Rule
Tax treatment depends on current Income Tax rules, the policy conditions and personal tax details. An eligible premium may qualify under Section 80C when the law and selected tax system allow it. Death-benefit treatment is subject to Section 10(10D) and other rules.
If a tax rate is entered in the calculator, the total tax estimate assumes the same rate for every future payment. This is only an example because tax rates and rules can change during the policy term.
Tax saving is not the main purpose of Jeevan Amar, and tax laws can change.
How This Calculator Helps
The calculator removes the need to count payment years, multiply half-yearly premiums or work out the increasing-cover schedule by hand.
It also keeps Plan 855, Plan 955 V01 and Plan 955 V02 separate. Withdrawn versions remain available for old-policy checks.
Most importantly, the tool does not turn a few brochure examples into a full premium table. An unsupported combination needs a base premium from an official LIC quotation or policy. This makes the result clearer and less likely to mislead.
Frequently Asked Questions
1. Can the calculator estimate every Jeevan Amar premium?
No. It uses an entered premium from an official policy or quotation, or an exact Plan 955 V02 brochure sample. It does not guess rates for unsupported details.
2. What is the difference between Plans 855 and 955?
Plan 855 is the older withdrawn product. Plan 955 is New Jeevan Amar and has separate V01 and V02 UIN versions. Their policy rules should not be mixed.
3. What is the difference between Level and Increasing Sum Assured?
Under Option I, the Absolute Cover stays equal to the Basic Sum Assured. Under Option II, it stays level for five years and then rises under the fixed plan schedule until it reaches two times the Basic Sum Assured.
4. Does LIC Jeevan Amar pay a maturity benefit?
No. The normal maturity benefit is ₹0 when the life assured survives the policy term. Jeevan Amar is not a return-of-premium plan.
5. Is New Jeevan Amar Plan 955 currently available?
As checked on 18 August 2026, LIC lists Plan 955 with UIN 512N350V02 among its term assurance plans. Availability should still be checked before applying.
Conclusion
The LIC Jeevan Amar Premium Calculator makes Plans 855 and 955 easier to understand. It shows premium payments, payment years and level or increasing cover without presenting Jeevan Amar as a savings plan.
For the most reliable result, the correct plan and UIN should be selected and the base premium should be copied from the policy or official LIC quotation. Brochure mode should be used only for its exact sample combinations.
The normal maturity benefit remains ₹0 under both plans. Final premiums and benefits must be checked against LIC’s official quotation, policy document and underwriting decision.