LIC Jeevan Shanti Plan 850 Calculator
Single Premium Annuity Estimate Calculator
Calculation Results
Purchase & Rate Summary
Plan & Eligibility Summary
Mode-Wise Annuity Payment Details
| Payment Mode | Estimated Payment | Rate per ₹1,000 | Payment Timing | Minimum Annuity |
|---|
Selected Option Benefits
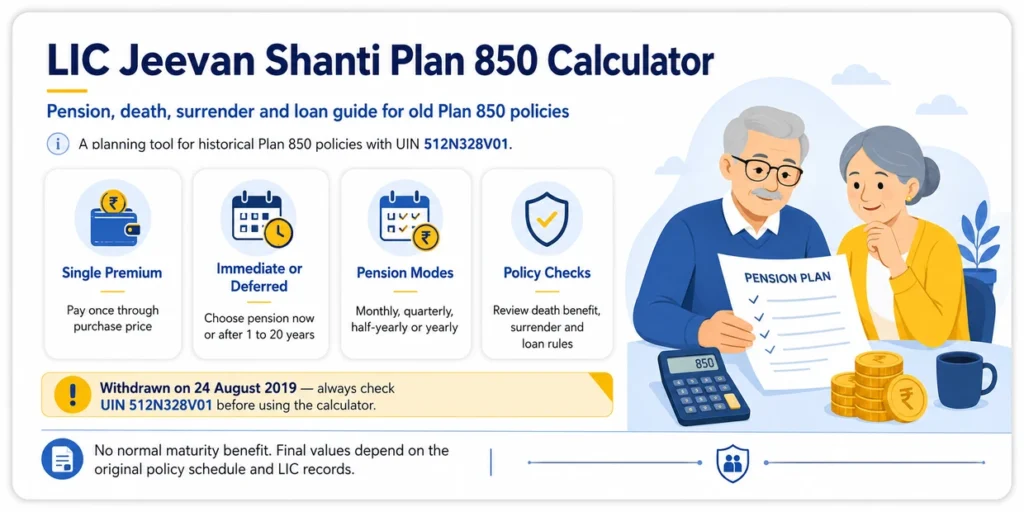
LIC Jeevan Shanti Plan 850 is a single-premium pension plan. The policyholder paid a lump sum once and received an annuity, commonly called a pension, based on the selected option.
The LIC Jeevan Shanti Plan 850 Calculator helps check the pension structure, payment mode, vesting age, death benefit and surrender eligibility of an old policy. It can also explain whether the selected option allowed a policy loan or return of the purchase price.
Important plan status: This guide is covers Plan 850 with UIN 512N328V01. LIC withdrew this version on 24 August 2019. Plan 850 was later issued under UIN 512N328V02, which had a separate policy period. Always check the UIN printed on the policy schedule before using the calculator.
Also Check:
- LIC New Jeevan Shanti Plan 758 Calculator
- LIC New Jeevan Shanti Plan 858 Calculator
- New LIC Jeevan Shanti Calculator
What Is the LIC Jeevan Shanti Plan 850?
LIC Jeevan Shanti Plan 850 was a single-premium pension plan in which the policyholder paid a lump sum only once. The plan offered immediate and deferred annuity options. Under immediate annuity, pension started after the selected payment period, while deferred annuity started after a chosen waiting period. It also offered single-life and joint-life options, return of purchase price, guaranteed pension periods and an increasing pension option. The pension rate was fixed when the policy started. Plan 850 is now withdrawn.
LIC Jeevan Shanti Plan 850 Overview
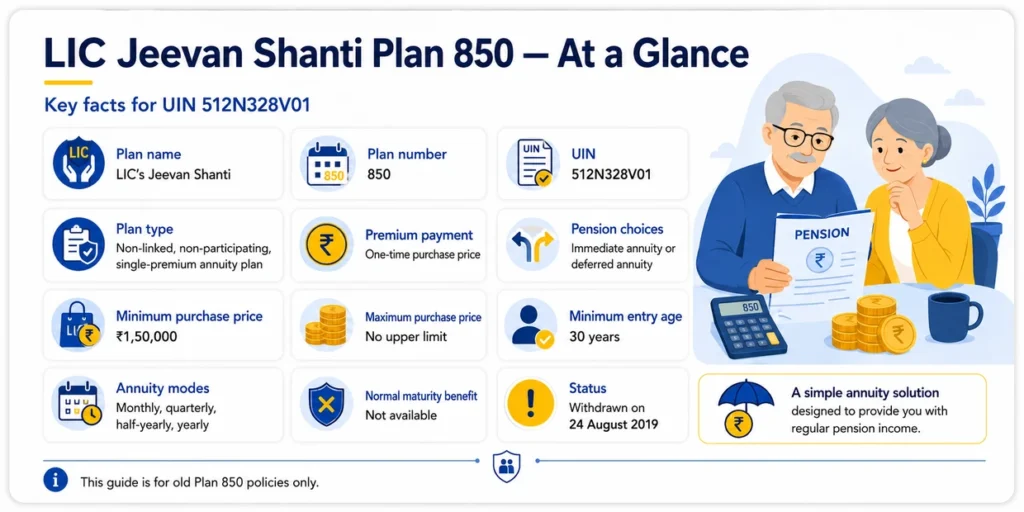
| Feature | Details |
|---|---|
| Plan name | LIC’s Jeevan Shanti |
| Plan number | 850 |
| UIN covered in this guide | 512N328V01 |
| Plan type | Non-linked, non-participating, single-premium annuity plan |
| Premium payment | One-time purchase price |
| Pension choices | Immediate annuity or deferred annuity |
| Minimum purchase price | ₹1,50,000, subject to the minimum annuity limit |
| Maximum purchase price | No upper limit |
| Minimum entry age | 30 completed years |
| Annuity modes | Monthly, quarterly, half-yearly and yearly |
| Normal maturity benefit | Not available |
| Status | Withdrawn on 24 August 2019 |
The annuity rate was fixed when the policy started. It depended on the age, purchase price, selected option, payment mode and deferment period, where applicable.
Immediate Annuity and Deferred Annuity
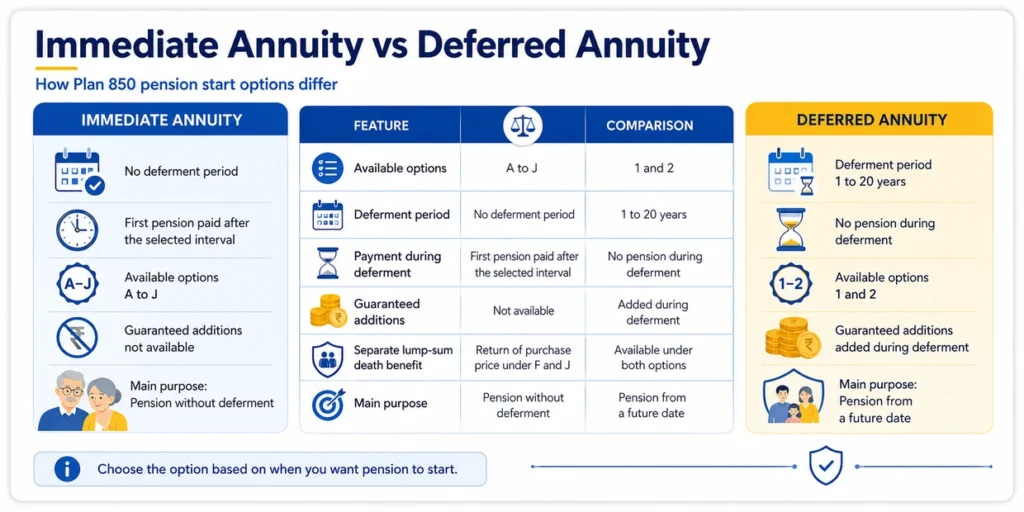
Plan 850 offered two main pension choices.
Immediate annuity
Under immediate annuity, there was no deferment period. The first pension was paid after the selected payment interval. For example, monthly pension was paid after one month and yearly pension after one year.
Deferred annuity
Under deferred annuity, pension did not start immediately. The policyholder selected a deferment period of 1 to 20 years. Pension started after the deferment period and was then paid in arrears according to the chosen mode.
| Point | Immediate Annuity | Deferred Annuity |
| Available options | Options A to J | Option 1 and Option 2 |
| Deferment period | Not applicable | 1 to 20 years |
| Payment during deferment | Not applicable | No pension paid |
| Guaranteed additions | Not available | Added during deferment |
| Separate lump-sum death benefit | Return of purchase price under F and J | Available under both options |
| Main purpose | Pension without a deferment period | Pension from a future date |
Immediate Annuity Options Under Plan 850
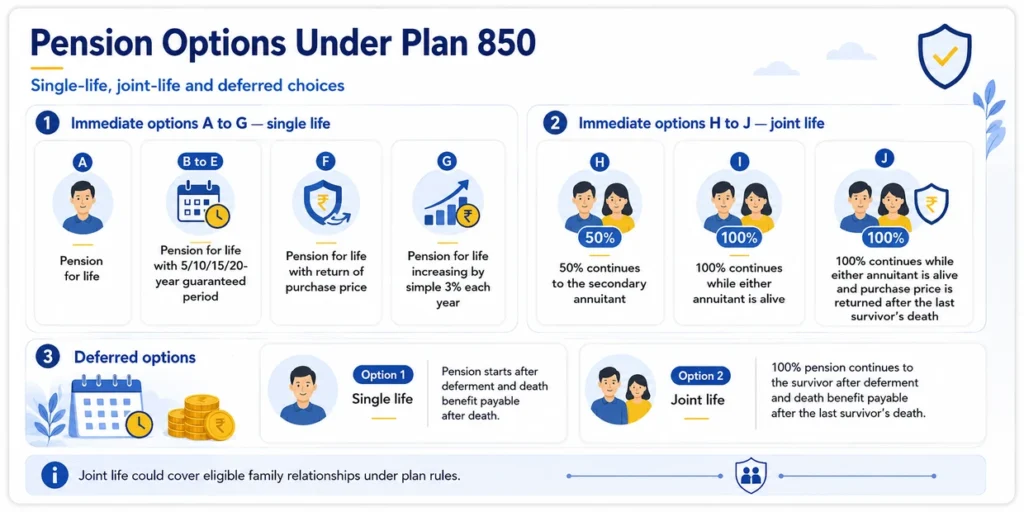
Plan 850 offered ten immediate annuity options. Each option had a different balance between regular pension and family protection.
| Option | Pension Benefit | What Happens After Death? |
| A | Pension for life | Pension stops; nothing else is payable |
| B | Pension for life with a 5-year guaranteed period | If death happens within 5 years, pension continues to the nominee until the period ends |
| C | Pension for life with a 10-year guaranteed period | If death happens within 10 years, pension continues to the nominee until the period ends |
| D | Pension for life with a 15-year guaranteed period | If death happens within 15 years, pension continues to the nominee until the period ends |
| E | Pension for life with a 20-year guaranteed period | If death happens within 20 years, pension continues to the nominee until the period ends |
| F | Pension for life with return of purchase price | Pension stops and the purchase price is payable to the nominee |
| G | Pension for life, increasing by a simple 3% each year | Pension stops; nothing else is payable |
| H | Joint-life pension; 50% continues to the secondary annuitant | Pension stops after the secondary annuitant’s death |
| I | Joint-life pension; 100% continues while either annuitant is alive | Pension stops after the last survivor’s death |
| J | Joint-life pension; 100% continues while either annuitant is alive | Purchase price is payable after the last survivor’s death |
Options A to G: Single-life choices
Options A to G covered one annuitant. Option A provided pension for life without any amount after death. Options B to E protected pension payments for a fixed minimum period. Option F returned the purchase price after death. Option G increased the pension by a simple 3% after every completed policy year.
Option F generally paid a lower pension than Option A because it also included the return-of-purchase-price benefit.
Options H to J: Joint-life choices
These options covered a primary and a secondary annuitant. Joint life was allowed between spouses, siblings, or family members in a direct ascending or descending line, such as parents, children, grandparents and grandchildren.
Under Option H, 50% of the pension continued to the secondary annuitant after the primary annuitant’s death. If the secondary annuitant died first, the full pension continued to the primary annuitant.
Under Options I and J, 100% of the pension continued while either annuitant was alive. Option J also returned the purchase price after the last survivor’s death.
Deferred Annuity Options Under Plan 850
Deferred annuity had two options.
| Option | Lives Covered | During Deferment | After Deferment | Death Benefit |
| Option 1 | Single life | No pension is paid | Pension is paid while the annuitant is alive | Payable after the annuitant’s death |
| Option 2 | Joint life | No pension is paid | Pension continues while either annuitant is alive | Payable after the last survivor’s death |
Under Joint-life Deferred Option 2, nothing was payable on the first death during the deferment period. After the deferment period, 100% pension continued to the surviving annuitant. The death benefit became payable after the last survivor’s death.
Eligibility and Annuity Limits
| Requirement | Immediate Annuity | Deferred Annuity |
| Minimum entry age | 30 years | 30 years |
| Maximum entry age | 85 years, except Option F | 79 years |
| Maximum age for Option F | 100 years | Not applicable |
| Minimum deferment period | Not applicable | 1 year |
| Maximum deferment period | Not applicable | 20 years, subject to vesting-age limit |
| Minimum vesting age | Not applicable | 31 years |
| Maximum vesting age | Not applicable | 80 years |
The minimum annuity depended on the payment mode.
| Payment Mode | Minimum Annuity |
| Monthly | ₹1,000 per month |
| Quarterly | ₹3,000 per quarter |
| Half-yearly | ₹6,000 per half-year |
| Yearly | ₹12,000 per year |
How to Use the LIC Jeevan Shanti Plan 850 Calculator
- Check that the policy UIN is 512N328V01.
- Select immediate annuity or deferred annuity.
- Choose the exact annuity option printed on the policy schedule.
- Enter the purchase price, excluding tax.
- Enter the primary annuitant’s age at policy entry.
- For a joint-life option, enter the secondary annuitant’s age.
- Select monthly, quarterly, half-yearly or yearly pension mode.
- For deferred annuity, enter the deferment period.
- Enter the historical annuity rate if the calculator asks for it.
- Select Calculate to view the estimated pension and benefit details.
The purchase price, age and policy option should match the policy schedule. Even a small change in age or option can change the pension amount.
Formula Used in the Calculator
Pension calculation
LIC annuity rates were generally shown as an amount per ₹1,000 of purchase price.
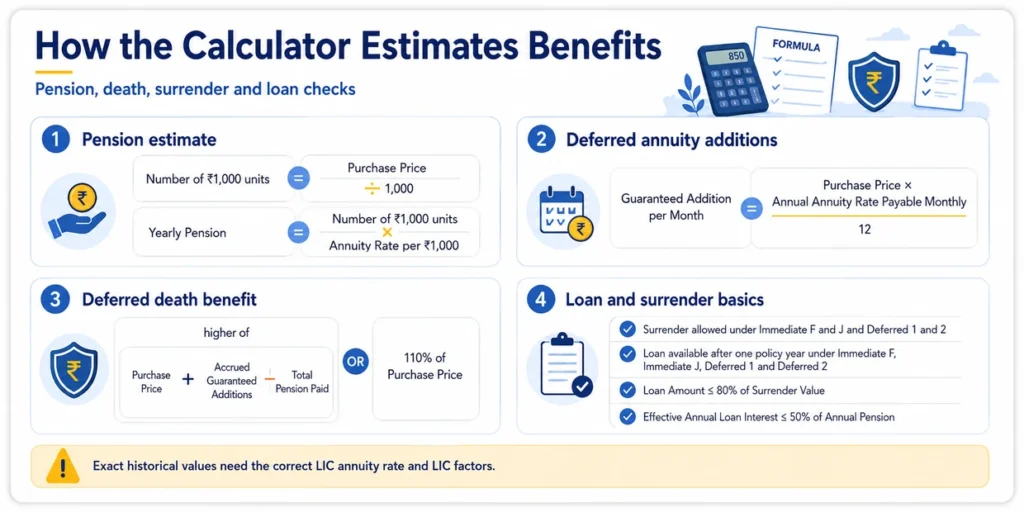
Number of ₹1,000 units = Purchase Price ÷ 1,000

Yearly Pension = Number of ₹1,000 units × Annuity Rate per ₹1,000
Mode-wise pension
The yearly pension should not be divided directly into every payment mode unless the correct LIC mode rate or adjustment is used. Where an approved yearly equivalent is already available, a simple display conversion may be shown separately:
Half-yearly display = Yearly Equivalent ÷ 2
Quarterly display = Yearly Equivalent ÷ 4
Monthly display = Yearly Equivalent ÷ 12
This display conversion does not replace LIC’s original mode-wise annuity rate.
Guaranteed additions under deferred annuity
Guaranteed additions were added at the end of each policy month during the deferment period.
Guaranteed Addition per Month =
(Purchase Price × Annual Annuity Rate Payable Monthly) ÷ 12
For this formula, LIC used the monthly tabular annuity rate without the purchase-price incentive or mode reduction.
Higher Purchase Price Incentive
LIC increased the annuity rate for higher purchase prices. The following amounts were added per ₹1,000 of purchase price.
| Purchase Price | Yearly | Half-yearly | Quarterly | Monthly |
| ₹5,00,000 to ₹9,99,999 | 1.50 | 1.40 | 1.35 | 1.30 |
| ₹10,00,000 to ₹24,99,999 | 2.10 | 2.00 | 1.95 | 1.90 |
| ₹25,00,000 to ₹49,99,999 | 2.45 | 2.35 | 2.30 | 2.25 |
| ₹50,00,000 to ₹99,99,999 | 2.60 | 2.50 | 2.45 | 2.40 |
| ₹1,00,00,000 and above | 2.70 | 2.60 | 2.55 | 2.50 |
LIC also provided a 2% increase in the annuity rate for eligible online purchases, NPS subscribers and QROPS purchases.
For deferred annuity, LIC applied the following reduction to the yearly annuity rate for non-yearly modes:
| Mode | Reduction in Yearly Annuity Rate |
| Half-yearly | 2% |
| Quarterly | 3% |
| Monthly | 4% |
These are historical Plan 850 rules. They are not current LIC annuity rates.
Official LIC Calculation Example
LIC’s brochure used this example:
| Input | Value |
| Purchase price | ₹10,00,000, excluding tax |
| Primary annuitant’s age | 45 years |
| Secondary annuitant’s age | 35 years |
| Annuity mode | Yearly |
| Deferment period | 20 years for deferred options |
The brochure showed these yearly pension amounts:
| Option | Historical Yearly Pension |
| Option A | ₹74,300 |
| Option B | ₹74,200 |
| Option C | ₹73,900 |
| Option D | ₹73,500 |
| Option E | ₹72,900 |
| Option F | ₹65,400 |
| Option G | ₹56,200 |
| Option H | ₹71,100 |
| Option I | ₹68,300 |
| Option J | ₹64,900 |
| Deferred Option 1 | ₹2,06,600 |
| Deferred Option 2 | ₹2,27,200 |
These figures are historical LIC brochure illustrations. They are not current quotations and should not be used for a policy with different details.
Option F calculation
For a purchase price of ₹10,00,000 and yearly pension of ₹65,400:
Number of ₹1,000 units = ₹10,00,000 ÷ ₹1,000
                       = 1,000 units

Rate per ₹1,000 = ₹65,400 ÷ 1,000
                = ₹65.40

Yearly Pension = 1,000 × ₹65.40
               = ₹65,400
Under Option F, ₹65,400 was paid each year while the annuitant was alive. After death, pension stopped and the purchase price was payable according to the death-benefit payment option selected under the policy.
Does Plan 850 Have a Maturity Amount?
Plan 850 did not have a normal maturity benefit. It was an annuity plan, not an endowment or money-back plan.
Under deferred annuity, the policy reached its vesting date after the deferment period. Pension then became payable in arrears according to the selected mode. Vesting did not create a separate lump-sum maturity payment.
A useful calculator should therefore show the vesting age and pension amount instead of displaying a false maturity value.
Death Benefit Under Plan 850
Immediate annuity
Options F and J included return of the purchase price. Options B to E could continue pension to the nominee until the guaranteed period ended. Options H and I continued pension to the eligible surviving annuitant, but did not provide a separate lump-sum amount after the last death.
Deferred annuity
For Deferred Options 1 and 2, the death benefit was the higher of the following two values:
Purchase Price
+ Accrued Guaranteed Additions
− Total Pension Payments Made up to the Date of Death

OR

110% of Purchase Price
The policyholder could select payment of the eligible death benefit as:
- A lump sum
- An immediate annuity for the nominee
- Instalments over 5, 10 or 15 years
The option selected by the annuitant applied to the nominee. Conditions and minimum instalment limits mentioned in the policy document also applied.
Surrender Value
Surrender was allowed only under the following options:
| Policy Type | Options Eligible for Surrender |
| Immediate annuity | Option F and Option J |
| Deferred annuity | Option 1 and Option 2 |
The policy could be surrendered after three months from the date of issue or after the free-look period ended, whichever was later.
During the deferment period
Surrender Value =
F3 × [(F1 × Yearly Equivalent Pension) + (F2 × 110% of Purchase Price)]
Under immediate annuity or after deferment
Surrender Value =
[(F1 × Yearly Equivalent Pension) + (F2 × 110% of Purchase Price)]
− Pension Instalments Paid in the Policy Year of Surrender
F1, F2 and F3 were LIC factors. Their values depended on age, surrender date, vesting details and other policy conditions. For joint-life policies, the relevant factors depended on the younger annuitant’s age.
An exact surrender value should not be shown unless the correct LIC factors for that policy are available. Surrender can also cause a financial loss, so the amount should be confirmed with LIC before taking a decision.
Policy Loan
A loan was available after completion of one policy year under:
- Immediate Option F
- Immediate Option J
- Deferred Option 1
- Deferred Option 2
The maximum loan was subject to both conditions below:
Loan Amount ≤ 80% of Surrender Value

Effective Annual Loan Interest ≤ 50% of Annual Pension
During the deferment period, loan interest was payable on a half-yearly compound basis under the policy conditions. After pension started, LIC could recover loan interest from the pension payments.
Tax Rule and Free-Look Period
Applicable tax was collected separately from the purchase price. Tax paid was not included when LIC calculated policy benefits.
Tax rules can change. The tax treatment of pension income or claim payments should be checked under the rules applicable in the relevant financial year.
| Purchase Method | Free-Look Period |
| Offline purchase | 15 days |
| Online purchase | 30 days |
The period was counted from receipt of the policy document. If the policy was returned during this period, LIC could deduct stamp duty and any pension already paid. Separate rules applied to QROPS purchases.
Frequently Asked Questions
1. Is LIC Jeevan Shanti Plan 850 still available?
No. Plan 850 with UIN 512N328V01 was withdrawn on 24 August 2019. This guide is for understanding an existing or historical policy.
2. Does Plan 850 provide a maturity amount?
No. It does not provide a normal maturity benefit. Under deferred annuity, pension starts after the deferment period, but no separate maturity lump sum is paid.
3. Which options return the purchase price?
Immediate Option F returns the purchase price after the annuitant’s death. Immediate Option J returns it after the last survivor’s death. Deferred Options 1 and 2 provide the applicable death benefit under their separate formula.
4. Which options allow surrender and a policy loan?
Immediate Options F and J and Deferred Options 1 and 2 allow surrender and a policy loan, subject to policy conditions. The loan is available only after one policy year.
5. Can the calculator show the exact pension and surrender value?
It can show an exact historical pension only when the correct LIC rate for the policy date and details is available. Exact surrender value also requires the correct LIC factors. The policy schedule and a value confirmed by LIC should be treated as final.
Conclusion
LIC Jeevan Shanti Plan 850 provided lifetime pension through one lump-sum purchase price. It offered immediate and deferred pension, single-life and joint-life choices, guaranteed-period options, increasing pension and return-of-purchase-price choices.
The calculator can make an old policy easier to understand. It can explain when pension starts, how often it is paid, what happens after death and whether surrender or a loan is allowed. However, historical rates and surrender factors must match the exact policy. Before making a surrender, loan or claim decision, check the UIN and confirm the final amount with LIC.