LIC Jeevan Arogya Plan 904 Calculator
UIN: 512N266V03 · Premium Estimate & Benefit Summary
Enter Policy Details
Premium & Benefit Summary
Premium Breakdown
Benefit Summary
LIC Jeevan Arogya Plan 904 was a fixed-benefit health insurance plan from the Life Insurance Corporation of India. The last version, UIN 512N266V03, was launched on 1 October 2020 and withdrawn from sale on 12 July 2021. It is no longer available for a new purchase, but an existing policy may continue under its issued terms.
The LIC Jeevan Arogya Plan 904 Calculator helps estimate the historical base premium and main policy benefits. These may include Hospital Cash Benefit, ICU Benefit, Major Surgical Benefit, Day Care Procedure Benefit and Other Surgical Benefit.
The calculator result is only an estimate. The current renewal premium and final claim amount depend on the policy schedule, premium notice, active cover, waiting periods, earlier claims and LIC’s assessment.
Also Check:
LIC Jeevan Arogya Plan 904 Overview
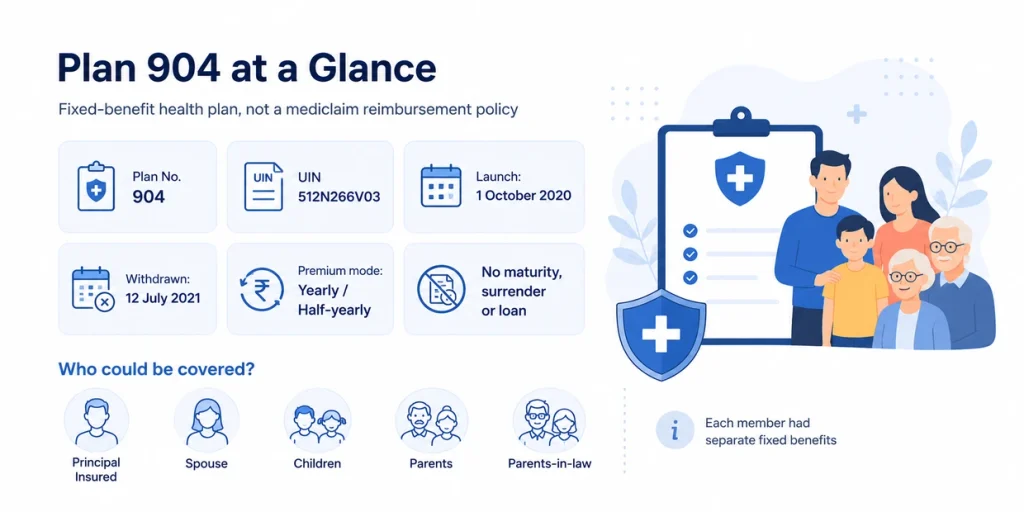
| Item | Detail |
|---|---|
| Plan name | LIC’s Jeevan Arogya |
| Plan number | 904 |
| UIN | 512N266V03 |
| Plan type | Non-linked, non-participating health plan |
| Launch date | 1 October 2020 |
| Withdrawal date | 12 July 2021 |
| Premium mode | Yearly or half-yearly |
| Maturity benefit | Not available |
| Surrender value | Not available |
| Loan facility | Not available |
LIC Jeevan Arogya was a fixed-benefit plan, not a normal medical insurance policy. It paid a set amount when an eligible hospital stay, surgery or day-care procedure met the policy conditions. It did not repay the complete hospital bill.
For example, if an eligible hospital stay gives a fixed benefit of ₹15,000 and the bill is ₹70,000, the policy may pay ₹15,000. The hospital bill does not decide the benefit amount.
What Is the LIC Jeevan Arogya Plan 904 Calculator?
The calculator uses the member’s category, age at entry, selected Initial Daily Benefit and premium mode. It can show an estimated historical base premium together with the Hospital Cash, ICU and surgical benefits linked to the selected daily amount.
LIC could review premiums after each three-year guarantee period. Therefore, the current renewal premium may be different from an old brochure rate or calculator estimate. Tax, rider premium, medical loading and policy changes may also affect the amount.
If the calculator uses LIC’s published sample rates rather than a complete official rate table, its premium result must be treated as an approximate illustration. The current LIC renewal notice remains the correct source for the amount due.
How to Use the Calculator
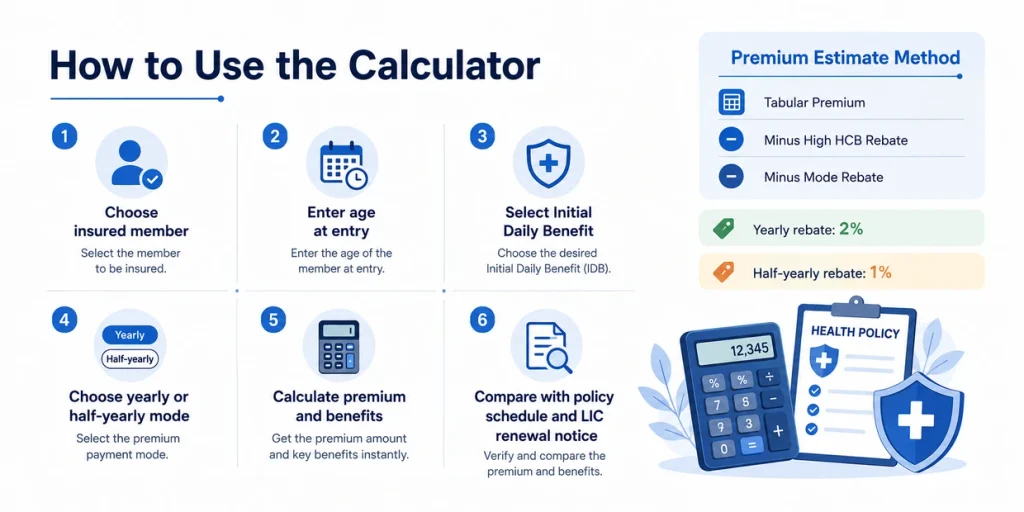
- Select the insured member: Principal Insured, spouse, parent, parent-in-law or child.
- Enter the age at which that member joined the policy.
- Select the Initial Daily Benefit shown in the policy schedule.
- Choose yearly or half-yearly premium mode.
- Press Calculate Premium to view the estimate and linked benefits.
- Compare the result with the policy schedule and latest LIC premium notice.
Age at entry is different from current age. The age used when the member was added to the policy should be entered.
Who Could Be Covered?
Plan 904 allowed eligible family members to be included under one policy. These could include the Principal Insured, spouse, dependent children, parents and parents-in-law.
This was not a shared family-floater cover. Every insured person had a separate daily benefit, surgical benefit and claim limit. A person was covered only when the name appeared in the policy schedule.
The entry age was 18 to 65 years for the Principal Insured or spouse and 18 to 75 years for parents or parents-in-law. A dependent child could enter from 91 days to 17 years. Adult cover could continue up to age 80, while child cover could continue up to age 25. The issued schedule should be checked instead of assuming that every member has the same cover.
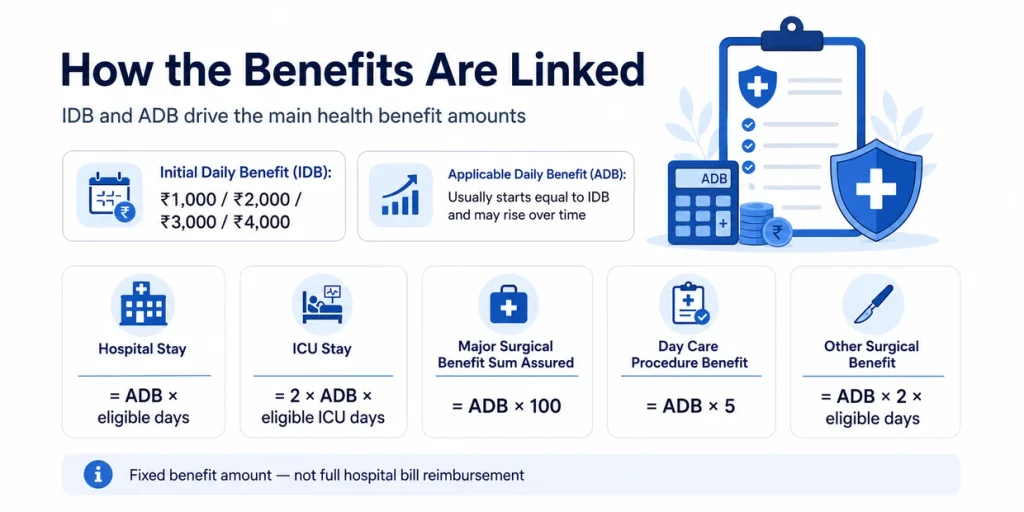
Initial Daily Benefit and Applicable Daily Benefit
The Initial Daily Benefit, or IDB, is the hospital cash amount selected when cover started. The choices were ₹1,000, ₹2,000, ₹3,000 or ₹4,000 per day.
The Applicable Daily Benefit, or ADB, is the daily benefit available in a particular policy year. During the first year, it is normally equal to the IDB.
After the first year, the regular benefit could increase by 5% of the IDB on each policy anniversary. This yearly-increase part continued until it reached 1.5 times the IDB. A separate No Claim Benefit could also increase the ADB after an eligible claim-free period.
The latest ADB should be obtained from LIC for a current claim because earlier claims and policy history may affect the available benefit.
Benefits and Formulas Used in the Calculator
| Benefit | Basic calculation |
| General hospital stay | ADB × eligible hospital days |
| ICU stay | 2 × ADB × eligible ICU days |
| Major Surgical Benefit Sum Assured | ADB × 100 |
| Major surgery payment | MSB Sum Assured × listed surgery percentage |
| Day Care Procedure Benefit | ADB × 5 |
| Other Surgical Benefit | ADB × 2 × eligible days |
These formulas show the basic amount before waiting periods, exclusions and claim limits are checked.
Hospital Cash and ICU Benefit
Hospital Cash Benefit pays a fixed amount for each eligible day in a hospital. The stay normally must continue for more than 24 hours. A further part-day may count when it continues for more than four hours.
The first 24 hours are generally not payable when the hospital stay is shorter than seven days. If one continuous stay lasts seven days or more, the first day may also become payable.
An eligible ICU day pays two times the ADB. If ICU and general-ward care happen on the same hospital day, that day may be treated as an ICU day when the ICU stay meets the required time condition.
The main limits for each insured person are:
| Limit | First policy year | Later policy years | Lifetime |
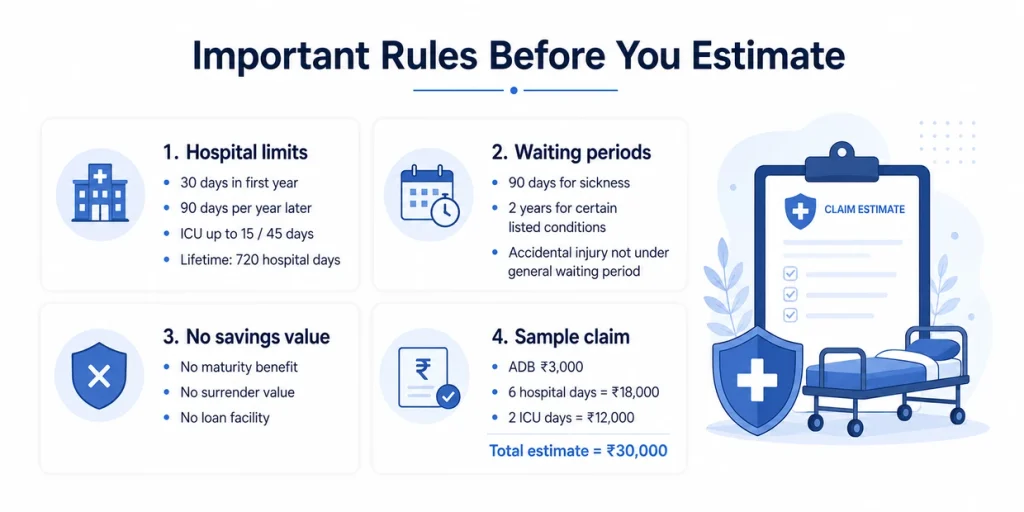
| Total hospital days | 30 days | 90 days per year | 720 days |
| ICU days included above | 15 days | 45 days per year | 360 days |
Major Surgical Benefit
Major Surgical Benefit applies when an insured person undergoes a surgery listed in the policy annexure.
Major Surgical Benefit Sum Assured = ADB × 100
The full Sum Assured is not payable for every surgery. The annexure gives each listed surgery a payment percentage. The yearly limit is 100% of the MSB Sum Assured and the lifetime limit is 800%.
An eligible Category I or Category II surgery may also provide a ₹1,000 ambulance benefit, subject to evidence. It may activate the Premium Waiver Benefit, under which one annualised policy premium can be waived according to the policy terms.
Day Care and Other Surgical Benefits
Day Care Procedure Benefit applies to a listed procedure that does not require an overnight hospital stay.
Day Care Procedure Benefit = ADB × 5
The limit is normally three eligible procedures in one policy year and 24 during the insured person’s full cover period. Hospital Cash Benefit is not paid for the same listed day-care procedure.
Other Surgical Benefit applies when an eligible surgery is not listed under Major Surgery or Day Care and it causes a qualifying hospital stay.
Other Surgical Benefit = ADB × 2 per eligible day
The limit is 15 days in the first policy year, 45 days in later years and 360 days during the full cover period.
Diseases Covered, Waiting Periods and Exclusions
Jeevan Arogya does not contain one simple list of covered diseases. It provides fixed benefits when an illness or accident causes an eligible hospital stay, listed surgery or listed day-care procedure.
For sickness-related treatment, a general waiting period of 90 days applied from the start of cover. This general waiting period did not apply to an eligible accidental bodily injury.
A two-year waiting period applied to treatments such as:
- Cataract, hernia, piles and hydrocele;
- Gallstones and kidney or urinary tract stones;
- Slipped disc and degenerative joint conditions;
- Sinus, tonsil and adenoid disorders;
- Benign thyroid, breast, prostate and uterine conditions;
- Anal fistula or fissure;
- Varicose veins; and
- Carpal tunnel syndrome.
Waiting-period conditions are not the same as permanently excluded conditions. Payment may become possible after the required period when all other policy rules are met.
The policy also excluded certain situations, including undisclosed pre-existing conditions, experimental treatment, routine check-ups, pregnancy-related treatment, non-eligible cosmetic treatment, substance misuse and other events listed in the policy document.
Premium Calculation
The historical base premium depended on age at entry, gender, insured-member category, selected IDB and payment mode.
The calculator broadly uses:
Tabular Premium = Rate for ₹1,000 daily benefit × selected benefit multiplier
Estimated Base Premium = Tabular Premium − High HCB rebate − mode rebate
The High HCB rebate was different for the Principal Insured and other members. The yearly mode rebate was 2% of the tabular premium, while the half-yearly rebate was 1%.
These formulas explain the calculator method, but they do not confirm the present renewal premium. LIC could review premium rates after every three-year guarantee period. The latest renewal notice should be used for payment.
Real Calculation Example
Assume the current ADB is ₹3,000 and an eligible hospital stay lasts eight continuous days. Two of those days include a qualifying ICU stay.
Since the continuous stay is at least seven days, all eight days are included in this illustration.
General hospital benefit for six days:
₹3,000 × 6 = ₹18,000
ICU benefit for two days:
₹3,000 × 2 × 2 = ₹12,000
Total estimated benefit:
₹18,000 + ₹12,000 = ₹30,000
The estimate can change if any day is not eligible or an annual limit has already been used. The hospital bill amount does not change this fixed-benefit calculation.
Claim Process and Documents
A health claim should be reported to LIC as early as possible. The servicing branch can confirm the current form and submission method.
Common documents may include:
- Completed health claim form;
- Policy number and identity proof;
- Admission and discharge summary;
- Doctor’s report and diagnosis;
- Medical test reports;
- Operation or procedure record;
- Hospital bills when requested; and
- Bank account details.
LIC may request more documents depending on the treatment and benefit claimed. Copies of submitted papers and the acknowledgement should be kept until the claim is completed.
Missed Premium and Revival
Yearly and half-yearly premiums had a grace period of one month, but not less than 30 days. If payment was not made within the grace period, the policy could lapse and benefits would stop.
Plan 904 V03 allowed revival within the period stated in its policy document, subject to LIC’s approval, unpaid premiums, interest and proof of continued insurability. The issued policy document should be checked before relying on a general revival period.
Does Plan 904 Have a Maturity Benefit?
No. LIC Jeevan Arogya was a health protection plan, not a savings plan. It does not provide a maturity payment, surrender value or policy loan.
Optional life and accident riders were available under stated conditions. An existing policy schedule will show whether any rider was actually selected.
Tax Rule
Premium paid for eligible health insurance may qualify for a deduction under Section 80D of the Income-tax Act, subject to the tax rules and personal eligibility for the relevant financial year. The premium receipt should be kept as proof.
The calculator cannot approve a claim or confirm medical eligibility. The policy bond, schedule, renewal notice and LIC’s final claim decision always take priority over a website estimate.
LIC Jeevan Arogya Plan 904 FAQs
Is LIC Jeevan Arogya Plan 904 available for new purchase?
No. UIN 512N266V03 was withdrawn from new sale on 12 July 2021. The calculator is meant for existing policies.
Is Jeevan Arogya a mediclaim policy?
No. It pays fixed benefits for eligible medical events instead of repaying the complete hospital bill.
Can the calculator show the current renewal premium?
It can provide an estimate based on historical rates. The latest LIC renewal notice shows the amount currently payable.
Does every surgery receive the full Major Surgical Benefit Sum Assured?
No. The payment percentage depends on the surgery category listed in the annexure attached to the policy.
Conclusion
The LIC Jeevan Arogya Plan 904 Calculator helps existing policyholders understand the historical base premium and fixed health benefits. It explains Hospital Cash, ICU, Major Surgery, Day Care and Other Surgery benefits without treating them as reimbursement of the hospital bill.
The most important details are the correct UIN, age at entry, Initial Daily Benefit and current Applicable Daily Benefit. Calculator results are useful for understanding the policy, but the issued documents and LIC records decide the actual premium and claim amount.