LIC Jeevan Mitra Maturity & Bonus Calculator
Estimate maturity and bonus for existing Jeevan Mitra Plan 88 and Plan 133 policies.
Policy details
Bonus details
Official bonus-rate periods
Combine years that used the same LIC rate. Do not use one recent rate for the whole term.
The 2021 rate depends on plan, policy term and whether Basic Sum Assured is above ₹1 lakh.
One-year bonus details
Results are estimates. Actual maturity depends on policy status, vested bonus, Final Additional Bonus and LIC’s policy records.
Estimated result
| Result | Amount or detail |
|---|
Bonus calculation details
| Rate and years | Bonus |
|---|
LIC Jeevan Mitra was a traditional participating endowment plan that combined savings, life cover and LIC bonuses. It was issued in two main versions: LIC Jeevan Mitra Double Cover Plan 88 and LIC Jeevan Mitra Triple Cover Plan 133. Both plans have been withdrawn, so they cannot be purchased as new policies. Existing policies continue according to their original terms.
The words Double Cover and Triple Cover mainly describe the death benefit during the policy term. They do not mean that LIC pays two or three times the Basic Sum Assured at normal maturity. Under both plans, maturity is generally based on the Basic Sum Assured plus vested bonuses and any applicable Final Additional Bonus.
LIC Jeevan Mitra Calculator estimates maturity, bonus, death benefit, premiums paid and Guaranteed Surrender Value from policy details.
About Jeevan Mitra
Jeevan Mitra is a participating endowment assurance plan. It provides life cover during the policy term and a maturity benefit when the life assured survives until the end of that term. It may also receive LIC bonuses. Premiums were generally payable throughout the selected term or until earlier death.
It is not a money-back plan because it does not normally provide periodic survival payments. It is also different from a pure term plan because it provides a maturity benefit.
Plans Covered by the Calculator
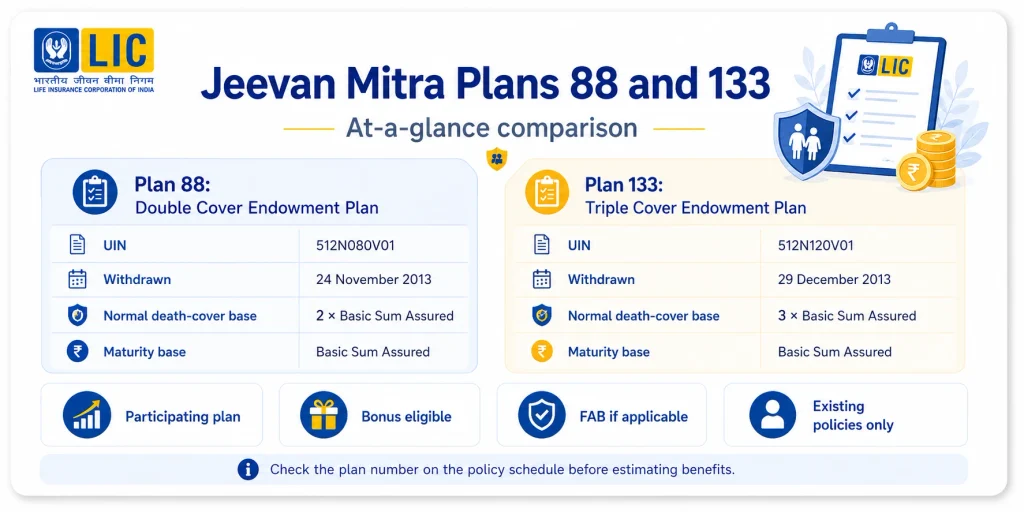
| Plan | Official name | UIN | Withdrawal date |
|---|---|---|---|
| Plan 88 | LIC Jeevan Mitra Double Cover Endowment Plan | 512N080V01 | 24 November 2013 |
| Plan 133 | LIC Jeevan Mitra Triple Cover Endowment Plan | 512N120V01 | 29 December 2013 |
The plan number and UIN printed on the policy schedule should be checked before entering any details. Selecting the wrong plan can produce an incorrect death-benefit estimate.
Plan 88 vs Plan 133
| Comparison point | Plan 88 | Plan 133 |
| Cover name | Double Cover | Triple Cover |
| Plan type | Participating endowment | Participating endowment |
| Normal death-cover base | 2 × Basic Sum Assured | 3 × Basic Sum Assured |
| Normal maturity base | Basic Sum Assured | Basic Sum Assured |
| Simple Reversionary Bonus | Applicable | Applicable |
| Final Additional Bonus | If declared and eligible | If declared and eligible |
| New purchase | Not available | Not available |
The main difference is the normal death-benefit base: twice the Basic Sum Assured under Plan 88 and three times under Plan 133. Bonuses are attached to the original Basic Sum Assured and are not multiplied. Normal maturity under both plans is one Basic Sum Assured plus applicable bonuses.
Key Highlights
- Endowment maturity benefit on survival until the end of the policy term
- Double or triple normal death cover according to the plan number
- Participation in LIC’s declared profits
- Simple Reversionary Bonus calculated on the Basic Sum Assured
- Possible Final Additional Bonus for an eligible maturity or death claim
- Yearly, half-yearly, quarterly, monthly or salary-deduction premium modes
- Surrender value after satisfying the applicable policy conditions
- Existing-policy servicing even though both plans are withdrawn
What is LIC Jeevan Mitra Calculator?
The calculator is made for existing Jeevan Mitra Plan 88 and Plan 133 policies. It uses the policy details entered to estimate the bonus, maturity amount and normal death benefit. It can also show the total basic premiums paid and an estimated Guaranteed Surrender Value.
If the total vested bonus is available in LIC records, it can be entered directly. If it is not available, an assumed average bonus rate can be used for a rough estimate. For a paid-up policy, the reduced maturity Sum Assured confirmed by LIC should be entered instead of the full Basic Sum Assured.
The result includes a simple calculation breakdown, but it is not an official LIC quotation. The calculator cannot confirm a claim, future bonus, Special Surrender Value, revival amount or policy loan.
Input Required for Calculation
Most required input information is available on the policy bond or latest LIC statement.
| Detail | What to enter |
| Plan number | Plan 88 or Plan 133 |
| Policy status | In force, Paid-up |
| Basic Sum Assured | Original amount printed on the policy schedule |
| Policy commencement | Start date or year shown in the policy records |
| Policy term | Complete term in years |
| Bonus information | Total vested bonus or verified bonus-rate periods |
| Final Additional Bonus | Enter only when confirmed for the claim |
| Basic instalment premium | Premium excluding tax, rider premium, late fee and extra premium |
| Premium mode | Yearly, half-yearly, quarterly or monthly |
| Total instalments paid | Number of basic premium instalments actually paid |
| Paid-up maturity Sum Assured | Reduced amount confirmed by LIC for a paid-up estimate |
How to Use LIC Jeevan Mitra Calculator
- Select Plan 88 or Plan 133 and choose the required calculation.
- Select the current policy status and enter the original Basic Sum Assured and policy details.
- Use the total vested bonus shown in LIC records. If it is unavailable, use verified rates or an assumed average rate for a projected estimate.
- Enter Final Additional Bonus only when LIC has confirmed that it applies.
- For premium or surrender calculations, enter the basic instalment premium, premium mode and total instalments paid.
- For a paid-up policy, enter the paid-up maturity Sum Assured confirmed by LIC.
- Select Calculate to view the estimate and breakdown.
Always enter the original Basic Sum Assured in its field. Do not enter the doubled or tripled death-cover amount as the Basic Sum Assured.
Formulas Used in the Calculator
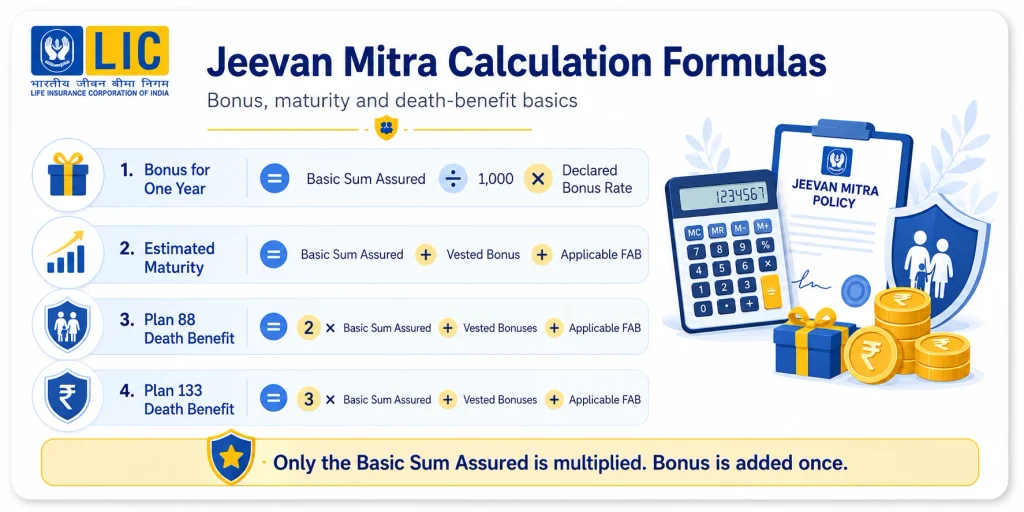
Bonus for One Year
LIC generally declares Simple Reversionary Bonus as an amount for every ₹1,000 of Basic Sum Assured.
Bonus for One Year
= Basic Sum Assured ÷ 1,000 × Declared Bonus Rate
If the Basic Sum Assured is ₹5,00,000 and the declared rate is ₹45 per ₹1,000, the bonus for that year is:
₹5,00,000 ÷ 1,000 × ₹45
= ₹22,500
This calculation covers only the selected valuation year. It is not the total bonus for the complete policy term.
Estimated Bonus Using an Average Rate
When the actual vested bonus and complete year-wise rates are unavailable, an average rate may be used for a rough projection.
Estimated Bonus
= Basic Sum Assured ÷ 1,000
× Assumed Average Bonus Rate
× Estimated Bonus Years
This result is a projected bonus estimate. It is not the vested bonus recorded under the policy. An assumed rate does not become guaranteed merely because it is entered in the calculator.
Actual rates can change by year, plan and policy term. The vested bonus shown in LIC records is more reliable than an average-rate estimate.
Final Additional Bonus
Final Additional Bonus, commonly called FAB, is different from the annual Simple Reversionary Bonus. When an applicable rate has been confirmed, it can be calculated as:
Final Additional Bonus
= Basic Sum Assured ÷ 1,000 × Applicable FAB Rate
FAB is not added every year. Eligibility can depend on the plan, policy duration, claim type and LIC’s declaration for the relevant year. Leave it out when LIC has not confirmed it.
Maturity Benefit
For an eligible in-force Plan 88 or Plan 133 policy:
Estimated Maturity Benefit
= Basic Sum Assured
+ Vested Simple Reversionary Bonus
+ Applicable Final Additional Bonus
For a paid-up policy, the full Basic Sum Assured should not be used automatically. Use the paid-up maturity Sum Assured confirmed by LIC.
Death Benefit
For an eligible in-force Plan 88 policy:
Estimated Death Benefit
= 2 × Basic Sum Assured
+ Vested Bonuses
+ Applicable Final Additional Bonus
For an eligible in-force Plan 133 policy:
Estimated Death Benefit
= 3 × Basic Sum Assured
+ Vested Bonuses
+ Applicable Final Additional Bonus
Only the Basic Sum Assured is multiplied. The bonus is added once.
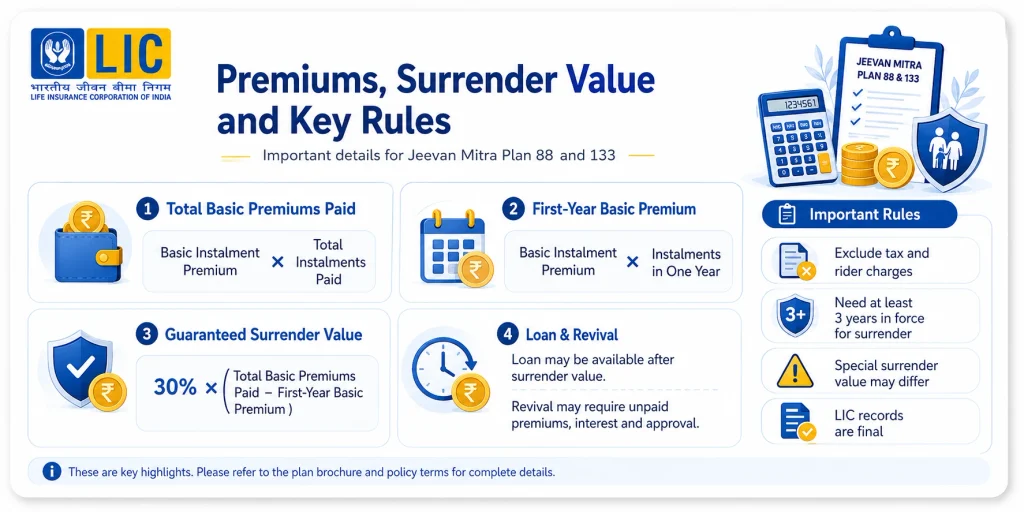
Total Basic Premiums Paid
Total Basic Premiums Paid
= Basic Instalment Premium × Total Instalments Paid
Use only the basic premium. Premium tax, rider premium, late fee and any extra premium charged by LIC should remain separate.
| Premium mode | Instalments in one year |
| Yearly | 1 |
| Half-yearly | 2 |
| Quarterly | 4 |
| Monthly or salary deduction | 12 |
The complete first-year basic premium is:
First-Year Basic Premium
= Basic Instalment Premium × Instalments in One Year
Guaranteed Surrender Value
Guaranteed Surrender Value
= 30% × (Total Basic Premiums Paid − First-Year Basic Premium)
The policy must first satisfy the surrender conditions. This formula does not calculate the Special Surrender Value or the value LIC may allow for vested bonuses.
Maturity Benefit
Normal maturity under both plans is one Basic Sum Assured plus applicable bonuses. A Basic Sum Assured of ₹5,00,000 must not be changed to ₹10,00,000 under Plan 88 or ₹15,00,000 under Plan 133. Policy status, confirmed bonuses, FAB eligibility and outstanding loans can affect the final payment.
Death Benefit
Plan 88 uses twice the Basic Sum Assured for the normal eligible death benefit, while Plan 133 uses three times. Bonuses are added only once. An accidental benefit should be included only when the policy schedule confirms the relevant supplementary benefit or rider and its conditions are satisfied. LIC determines the actual claim after checking the policy status, documents, conditions and outstanding amounts.
How Bonuses Work
Simple Reversionary Bonus is declared after LIC’s annual valuation. Once a declared bonus is attached to an eligible policy, it forms part of the policy benefits. Future bonuses remain uncertain because LIC may declare different rates in different years.
When a policy statement shows the total vested bonus, enter that amount directly. When only individual rates are available, calculate each year or rate period separately and add the results:
Total Vested Bonus
= Bonus for Year 1
+ Bonus for Year 2
+ Bonuses for the remaining eligible years
Do not treat projected benefits shown in an old sales illustration as the actual vested bonus of a policy. Those figures were created using assumed investment-return scenarios and were not guaranteed results.
Complete Calculation Example
Assume an existing in-force Plan 133 policy has these details:
- Basic Sum Assured: ₹5,00,000
- Policy term: 20 years
- Total vested bonus shown in LIC records: ₹4,00,000
- FAB confirmed as applicable for this example: ₹50,000
The maturity estimate is:
Estimated Maturity Benefit
= ₹5,00,000 + ₹4,00,000 + ₹50,000
= ₹9,50,000
The estimated maturity amount is ₹9,50,000. It is not ₹15,00,000 merely because Plan 133 is called Triple Cover.
If death occurred during the active policy term and the normal Plan 133 death benefit applied, the estimate would be:
Estimated Death Benefit
= 3 × ₹5,00,000 + ₹4,00,000 + ₹50,000
= ₹19,50,000
These figures are hypothetical and explain the formulas only. Actual payment depends on the policy status, claim timing, recorded bonus, FAB eligibility, policy conditions and deductions.
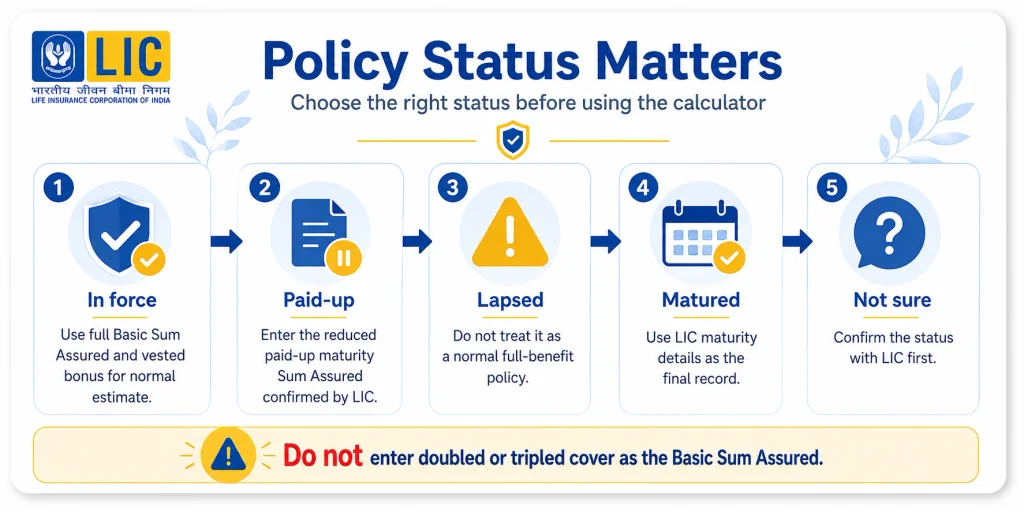
Select Correct Policy Status
Select In force when all required premiums have been paid and the policy is active. The calculator can then use the full Basic Sum Assured and vested bonus for the normal maturity estimate.
Select Paid-up when premiums were stopped but the policy continues with reduced benefits. Enter the reduced maturity Sum Assured confirmed by LIC. Do not use the full Basic Sum Assured.
Select Lapsed when the policy stopped because the required premiums were not paid and paid-up benefits have not been confirmed. A normal full maturity amount should not be shown for this status. Select Not sure when the current status is unknown and check it with LIC before calculating.
Select Matured when the policy term has already ended. In this case, use LIC’s maturity details as the final record and use the calculator only to compare the figures.
What is Paid-Up Policy
If premiums stop after the policy has acquired paid-up value, it may continue with reduced benefits instead of full benefits. The ratio below helps explain why benefits may be reduced:
Paid-Up Ratio
= Number of Premium Instalments Paid
÷ Total Premium Instalments Payable
Do not use this ratio alone to calculate paid-up maturity or death benefits. Enter the paid-up maturity Sum Assured confirmed by LIC, and check the reduced death benefit, revival amount and surrender value directly with LIC.
Surrender Value
The official Jeevan Mitra brochures state that a policy may be surrendered after it has remained in force for at least three years. The Guaranteed Surrender Value is 30% of basic premiums paid, excluding the complete first-year basic premium.
Suppose a yearly basic premium of ₹20,000 has been paid for five years:
Total Basic Premiums Paid
= ₹20,000 × 5
= ₹1,00,000

Premium Used for GSV
= ₹1,00,000 − ₹20,000
= ₹80,000

Guaranteed Surrender Value
= 30% × ₹80,000
= ₹24,000
LIC may calculate a Special Surrender Value that is equal to or higher than the Guaranteed Surrender Value. The actual surrender amount can depend on the premiums paid, policy duration, reduced benefits, vested bonus value, outstanding loan and interest. The calculator can show only the guaranteed formula; the final quotation must come from LIC.
Policy Loan
A policy loan may be available after the policy acquires surrender value, subject to its terms and LIC’s rules. Do not estimate a fixed amount without the applicable percentage and current surrender value. Unpaid loan and interest may be deducted from policy proceeds.
Lapse and Revival
Premiums should be paid by the due date or within the grace period allowed under the issued policy. If payment is not made, the policy may lapse or continue with reduced paid-up benefits if it has already acquired paid-up value.
A lapsed policy should not be treated as providing the same full benefits as an in-force policy. Revival may be possible under the period and conditions stated in the contract. LIC may require unpaid premiums, interest, evidence of health and approval before restoring the benefits.
Tax Benefits and Tax Rules
Tax treatment depends on the policy conditions, issue date, premium-to-Sum-Assured relationship, applicable law and chosen tax regime. Premium tax, rider charges, late fees and extra premiums are excluded from calculator formulas and policy benefits. Check the current rules before claiming a deduction or exemption.
Important Points to Remember
- Confirm whether the policy is Plan 88 or Plan 133.
- Select the correct current policy status.
- Use the original Basic Sum Assured as the bonus base; do not multiply maturity, vested bonus or FAB.
- Prefer the total vested bonus shown in LIC records.
- Label an average-rate result as projected bonus, not vested bonus.
- Include FAB only when LIC has confirmed that it applies.
- Exclude tax, rider premiums, late fees and extra premiums from basic-premium formulas.
- Deduct the complete first-year basic premium when calculating GSV.
- Consider any outstanding policy loan and interest.
Frequently Asked Questions
What is the maturity benefit of Plan 88?
For an eligible in-force Plan 88 policy, maturity is generally the Basic Sum Assured plus vested Simple Reversionary Bonus and any applicable Final Additional Bonus. Double Cover does not make maturity twice the Basic Sum Assured.
What is the maturity benefit of Plan 133?
For an eligible in-force Plan 133 policy, maturity is generally the Basic Sum Assured plus vested Simple Reversionary Bonus and any applicable Final Additional Bonus. Triple Cover applies to the normal death benefit, not the maturity multiplier.
How is the Jeevan Mitra bonus calculated?
Divide the Basic Sum Assured by 1,000 and multiply it by the applicable declared bonus rate. If rates changed, calculate each year or rate period separately. An assumed average rate produces only a projected bonus, not an LIC-confirmed vested bonus.
Can maturity be estimated for a paid-up policy?
Yes, but the paid-up maturity Sum Assured confirmed by LIC should be entered. Using the full Basic Sum Assured or only a simple paid-up ratio can overstate the result.
Are Plans 88 and 133 still available?
No. Plan 88 was withdrawn on 24 November 2013 and Plan 133 was withdrawn on 29 December 2013. Existing policies continue according to their issued terms.
Conclusion
LIC Jeevan Mitra Plans 88 and 133 are participating endowment policies with enhanced death protection. Plan 88 provides double normal death cover, while Plan 133 provides triple normal death cover. Under both plans, normal maturity remains based on one Basic Sum Assured plus applicable bonuses.
The calculator can combine the applicable Sum Assured, vested bonus and confirmed Final Additional Bonus to provide a maturity estimate. It can also calculate a one-year bonus, projected bonus, death benefit, basic premiums paid and an illustrative Guaranteed Surrender Value. Accurate use requires the correct plan, policy status, and LIC-confirmed information.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.