LIC Jeevan Mitra Plan 88 Maturity Calculator
Calculate estimated maturity value, death benefit, bonus and guaranteed surrender value.
Policy Details
Premium Details
Bonus Details
Calculation Result
Calculation Summary
LIC Jeevan Mitra Plan 88, officially called Jeevan Mitra Double Cover Endowment Plan, its a traditional life insurance and savings policy. It provided a higher death benefit during the policy term and paid a maturity amount if the life assured survived until the end of the term.
This plan is no longer available for purchase. LIC withdrew it from new sale on 24 November 2013. In this guide, we will know LIC Jeevan Mitra Plan 88 Maturity Calculator will help existing policyholders to know their estimated maturity amount, death benefit, total basic premiums, and minimum surrender value.
Also Check: LIC Jeevan Mitra Plan 133
About the LIC Jeevan Mitra Plan 88 Calculator
The calculator uses the Basic Sum Assured, premium, policy term, premiums already paid, vested bonus and Final Additional Bonus to estimate the main policy values.
It will give a more accurate result when the original policy bond and current bonus details are available to enter the correct values. An active policy that has not yet reached maturity may receive more bonuses in the future. Therefore, its result should be read as the value based on the bonus entered, not as a guaranteed final maturity amount.
LIC Jeevan Mitra Plan 88 Quick Overview
| Particular | Details |
|---|---|
| Plan name | Jeevan Mitra Double Cover Endowment Plan |
| Plan number | 88 |
| UIN | 512N080V01 |
| Plan type | Participating endowment plan |
| Premium payment | Regular premium throughout the policy term or until earlier death |
| Death benefit | Twice the Basic Sum Assured plus applicable bonuses |
| Maturity benefit | Basic Sum Assured plus applicable bonuses |
| Bonus | Simple Reversionary Bonus and possible Final Additional Bonus |
| Surrender eligibility | After the policy remains in force for at least three years |
| Current status | Withdrawn from sale |
What is LIC Jeevan Mitra Double Cover Plan 88?
Plan 88 is an endowment policy that combined life cover with savings. Premiums could be paid yearly, half-yearly, quarterly, monthly or through salary deduction. If the life assured survived until maturity, LIC paid the Basic Sum Assured with bonuses added to the policy.
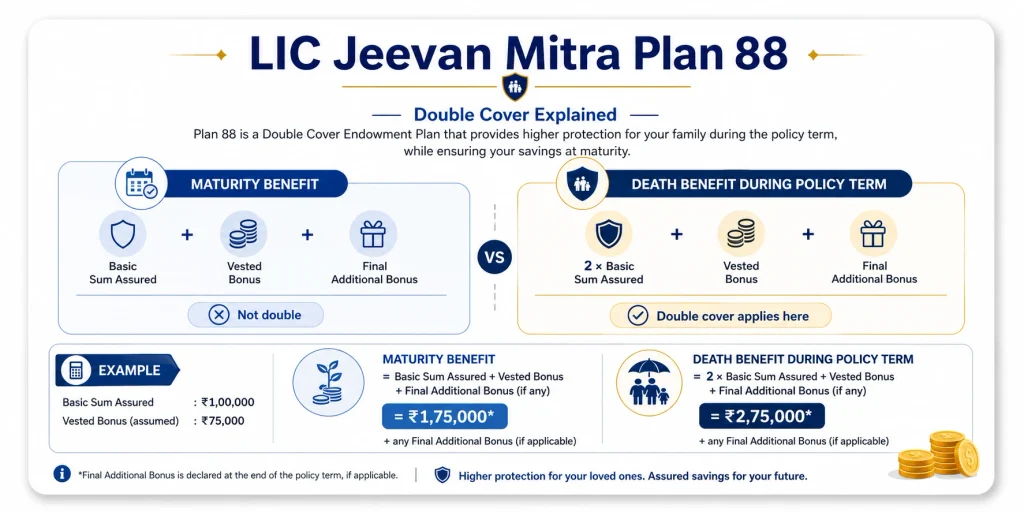
The words Double Cover apply to the death benefit, not to the maturity amount. If the life assured died while the policy was valid, the base death cover was twice the Basic Sum Assured. Bonuses were then added separately.
For example, a policy with a Basic Sum Assured of ₹1,00,000 did not automatically pay ₹2,00,000 at maturity. Its maturity benefit was ₹1,00,000 plus applicable bonuses. The ₹2,00,000 base amount applied to the death benefit during the policy term.
Main Highlights of the Double Cover Plan 88
The policy provided double life cover during its term while keeping the maturity benefit equal to one Basic Sum Assured plus bonuses. It participated in LIC’s profits, so Simple Reversionary Bonuses could be added each year. A Final Additional Bonus could also be paid when declared and applicable.
The plan allowed different premium-payment modes and provided a surrender facility after three years. Its final value depended on the premiums paid, policy status and bonuses declared by LIC.
How to Use LIC Jeevan Mitra Double Cover Calculator?
Start with the Basic Sum Assured printed on the policy bond. Enter the full policy term and the number of years completed. Select the premium-payment mode and enter only the basic instalment premium. Do not include tax, rider premium, late fee, extra premium or revival interest.
Enter the number of premium instalments actually paid. For example, ten years of quarterly payments normally means 40 instalments. Enter the total vested bonus shown in LIC records and add Final Additional Bonus only when an applicable amount has been confirmed.
Select the correct policy status and calculate the result. If premiums were stopped, the original full-benefit formula may not apply. In that situation, the calculator can provide only a basic estimate and the reduced benefit should be checked with LIC.
Formulas Used in the Calculator
The calculator uses the following main formulas:
Maturity Benefit =
Basic Sum Assured
+ Vested Simple Reversionary Bonus
+ Final Additional Bonus, if applicable
Death Benefit =
(2 × Basic Sum Assured)
+ Vested Simple Reversionary Bonus
+ Final Additional Bonus, if applicableTotal Basic Premium Paid =
Basic Instalment Premium × Number of Instalments PaidThe surrender calculation needs the full first-year basic premium. It should not deduct only one instalment when premiums were paid monthly, quarterly or half-yearly.
Maturity Benefit
If the life assured survives until the end of the term and the policy has full benefits, the maturity amount is calculated by adding the Basic Sum Assured, vested Simple Reversionary Bonus and any Final Additional Bonus payable at that time.
Maturity Benefit = Basic Sum Assured + Applicable BonusesThe maturity amount is not double the Basic Sum Assured. This is the most important point to remember about Plan 88. Double cover is available only for the death benefit during the policy term.
For an active policy that has not matured, future bonuses cannot be known in advance. A calculator using only the current vested bonus shows the value built up so far, along with any other confirmed amount entered.
Death Benefit
If the life assured dies during the policy term while full benefits are available, LIC pays twice the Basic Sum Assured plus bonuses on the Basic Sum Assured.
For example, if the Basic Sum Assured is ₹1,00,000 and the vested bonus is ₹75,000:
Death Benefit =
(2 × ₹1,00,000) + ₹75,000

= ₹2,75,000
The bonus is added once. It is not doubled with the Basic Sum Assured. Any eligible Final Additional Bonus may increase the benefit. Outstanding policy loan, loan interest or other deductions may reduce the amount finally paid.
How Bonuses Work
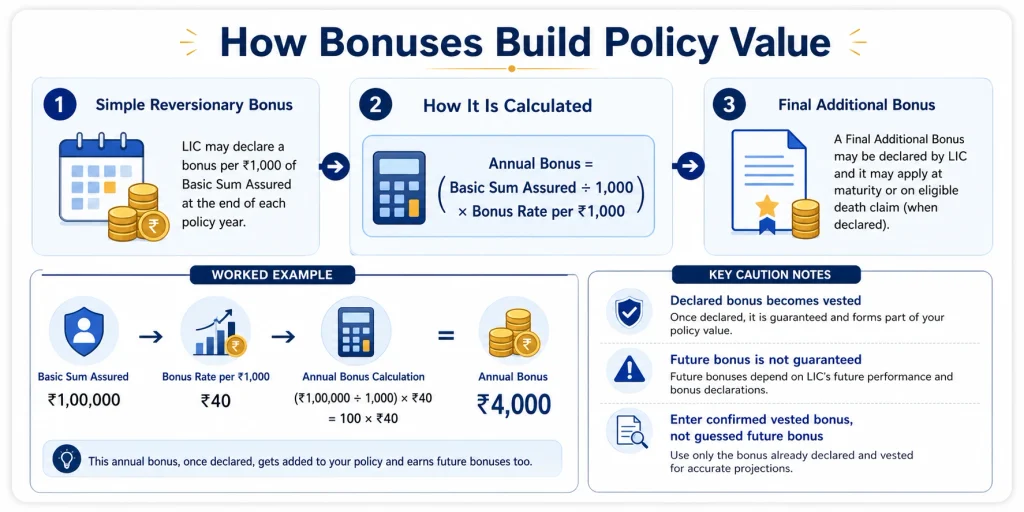
Plan 88 participated in LIC’s profits. LIC could declare a Simple Reversionary Bonus for every ₹1,000 of Basic Sum Assured. Once a bonus was declared and added to the policy, it became a vested benefit.
The annual bonus formula is:
Annual Bonus =
(Basic Sum Assured ÷ 1,000) × Bonus Rate per ₹1,000
Suppose the Basic Sum Assured is ₹1,00,000 and LIC declares a bonus rate of ₹40 per ₹1,000:
(₹1,00,000 ÷ 1,000) × ₹40
= 100 × ₹40
= ₹4,000
Future bonus rates are not guaranteed. The safest method is to enter the total vested bonus shown in the latest available LIC record instead of guessing future rates.
Final Additional Bonus is different from the yearly bonus. It may be paid at maturity or on an eligible death claim when LIC declares it and the policy meets the required conditions. It should be entered as zero when the applicable amount is not known.
Guaranteed Surrender Value
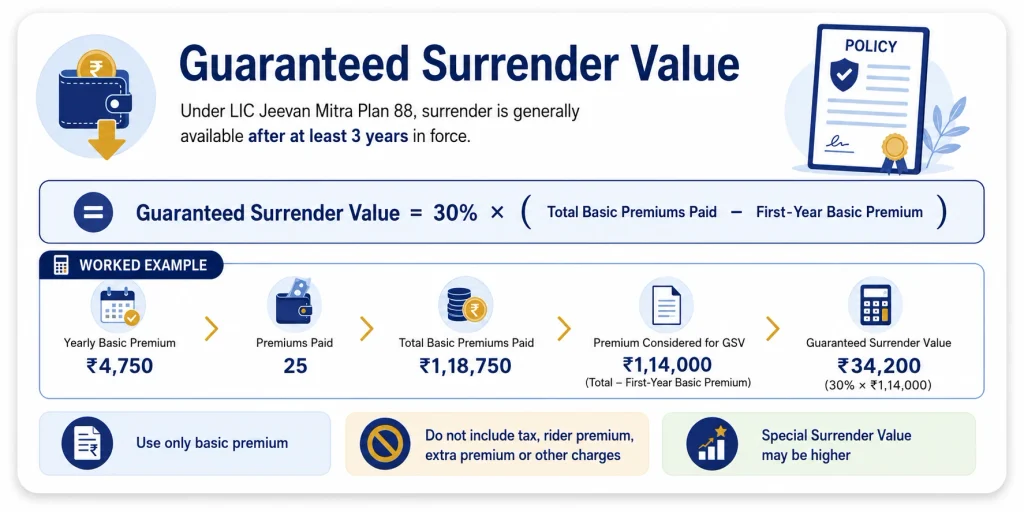
The policy could be surrendered after it had remained in force for at least three years. The minimum Guaranteed Surrender Value given in the sales brochure is:
Guaranteed Surrender Value =
30% × (Total Basic Premiums Paid − First-Year Basic Premium)
Tax, rider premium, extra premium and other charges should not be included in the basic premium used for this calculation.
Suppose a yearly premium policy has a basic premium of ₹4,750 and 25 premiums have been paid:
Total Basic Premiums Paid =
₹4,750 × 25
= ₹1,18,750

Premium considered for GSV =
₹1,18,750 − ₹4,750
= ₹1,14,000

Guaranteed Surrender Value =
30% × ₹1,14,000
= ₹34,200
This is only the guaranteed minimum under the brochure formula. LIC may pay a Special Surrender Value if it is higher. The exact amount depends on the policy duration, premiums paid and surrender factors used by LIC.
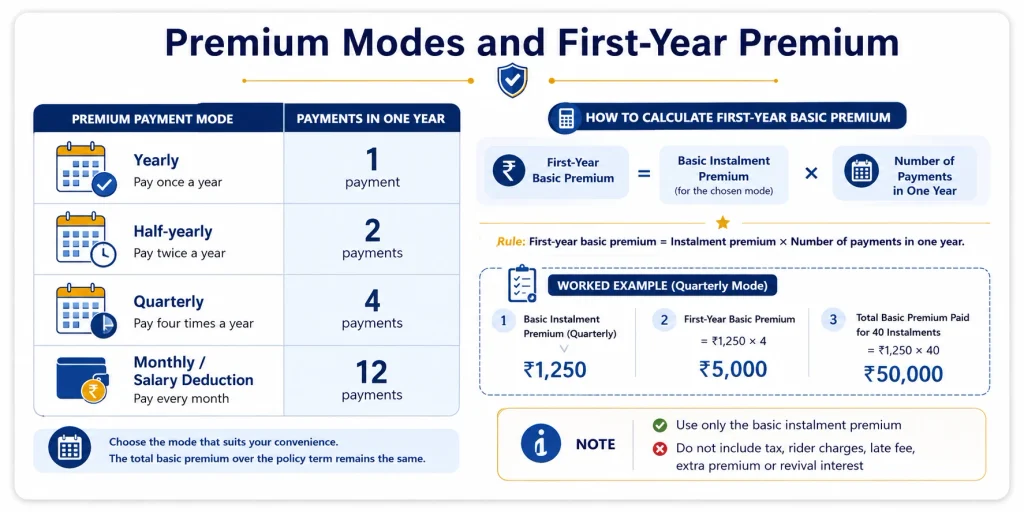
Premium Calculation for Different Payment Modes
The first-year basic premium must include every basic instalment payable during one year.
| Premium mode | Payments in one year | First-year basic premium |
| Yearly | 1 | Instalment premium × 1 |
| Half-yearly | 2 | Instalment premium × 2 |
| Quarterly | 4 | Instalment premium × 4 |
| Monthly or salary deduction | 12 | Instalment premium × 12 |
For example, if the quarterly basic premium is ₹1,250, the first-year basic premium is ₹5,000. If 40 quarterly instalments were paid, the total basic premium paid is ₹50,000.
First-Year Basic Premium = ₹1,250 × 4 = ₹5,000

Total Basic Premium Paid = ₹1,250 × 40 = ₹50,000
Complete Calculation Example
Consider an illustrative policy with these details:
| Particular | Amount |
| Basic Sum Assured | ₹1,00,000 |
| Yearly basic premium | ₹4,750 |
| Policy term | 25 years |
| Premiums paid | 25 |
| Vested bonus entered | ₹75,000 |
| Final Additional Bonus entered | ₹10,000 |
The maturity calculation is:
₹1,00,000 + ₹75,000 + ₹10,000
= ₹1,85,000
The death-benefit calculation during the policy term is:
(2 × ₹1,00,000) + ₹75,000 + ₹10,000
= ₹2,85,000
The total basic premium paid is:
₹4,750 × 25 = ₹1,18,750The Guaranteed Surrender Value based on the brochure formula is:
30% × (₹1,18,750 − ₹4,750)
= ₹34,200
The bonus amounts in this example are assumed only to explain the calculation. They do not represent a bonus promised by LIC.
LIC’s historical sales brochure also showed ₹69,500 as a projected variable benefit under an assumed 6% investment-return scenario and ₹1,89,500 under an assumed 10% scenario for its 25-year example. These were illustration figures, not actual vested bonuses or guaranteed returns.
What Happens If We Do Not Pay Premiums?
If premiums were stopped after the policy had earned a reduced benefit, the original Basic Sum Assured and full death cover may no longer apply in the same way. The amount can depend on how many premiums were paid, the policy term, vested bonuses and the conditions written in the policy contract.
A lapsed policy may also be eligible for revival, subject to LIC’s rules. An online calculator should not show a paid-up or lapsed estimate as a confirmed claim amount. The current status, revival amount and reduced benefits should be obtained from LIC.
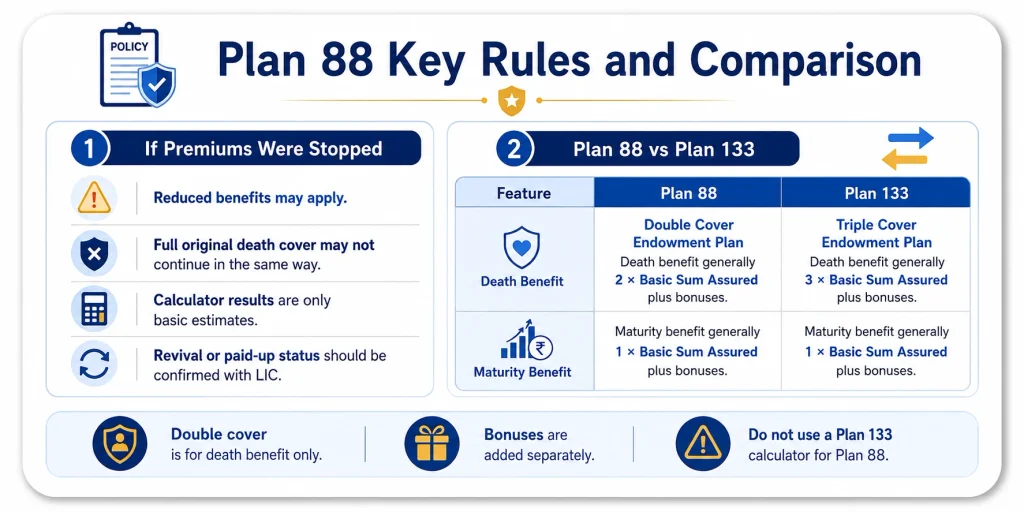
Main Difference Between Plan 88 and Plan 133
Plan 88 was the Double Cover Endowment Plan, while Plan 133 was the Triple Cover Endowment Plan. Plan 88 generally used twice the Basic Sum Assured for death benefit, whereas Plan 133 used three times the Basic Sum Assured. Both normally paid one Basic Sum Assured plus applicable bonuses at maturity. A Plan 133 calculator should therefore not be used for Plan 88.
Tax Benefits and Tax Rules
Tax treatment depends on the policy conditions and the tax law applicable when the premium or benefit is received. A premium may qualify for a deduction, while maturity or death proceeds may be taxable or exempt depending on the relevant rules.
Tax, rider premium and late fees should not be included in the basic premium used for calculator formulas. The latest tax rules should be checked before claiming any deduction or exemption.
Important Points to Remember
- Double cover applies to death benefit, not maturity benefit.
- Bonuses are added separately and are not doubled.
- Future bonus and Final Additional Bonus are not guaranteed.
- Use basic premium without tax, rider charges or late fees.
- Deduct the full first-year basic premium while estimating Guaranteed Surrender Value.
- Confirm paid-up, lapsed, surrender and final claim values with LIC.
Frequently Asked Questions
How is the Plan 88 maturity amount calculated?
The maturity amount is the Basic Sum Assured plus vested Simple Reversionary Bonus and Final Additional Bonus, if applicable. It is not twice the Basic Sum Assured.
Does Plan 88 pay double Sum Assured at maturity?
No. Double cover applies to death during the policy term. Maturity normally includes one Basic Sum Assured plus applicable bonuses.
How is the death benefit calculated?
The full death-benefit formula is twice the Basic Sum Assured plus vested bonuses and any applicable Final Additional Bonus. The bonus itself is not doubled.
Is the bonus guaranteed?
Future bonus is not guaranteed. A Simple Reversionary Bonus becomes part of the policy benefit after LIC declares and adds it to the policy. Final Additional Bonus is payable only when declared and applicable.
How is the surrender value calculated?
The minimum Guaranteed Surrender Value is 30% of total basic premiums paid after excluding the full first-year basic premium. LIC may pay a higher Special Surrender Value under its applicable rules.
Conclusion
The LIC Jeevan Mitra Plan 88 Maturity Calculator helps existing policyholders understand maturity value, double-cover death benefit, bonuses, total basic premiums and minimum surrender value.
The main difference is simple: maturity includes one Basic Sum Assured plus bonuses, while death during the policy term generally includes twice the Basic Sum Assured plus bonuses. Accurate results require the actual premium and vested bonus shown in LIC records.
1 thought on “LIC Jeevan Mitra Plan 88 Maturity Calculator Double Cover Endowment Plan”