LIC Jeevan Labh Plan No. 936 Calculator
(UIN: 512N304V02)
Launch Date: 01 February 2020
Withdrawn Date: 01 October 2024
Plan Type: Non-Linked, Participating, Limited Premium Payment Endowment Assurance Plan
Premium Details
Indicative EstimatePolicy Benefits
Plan Benefit Summary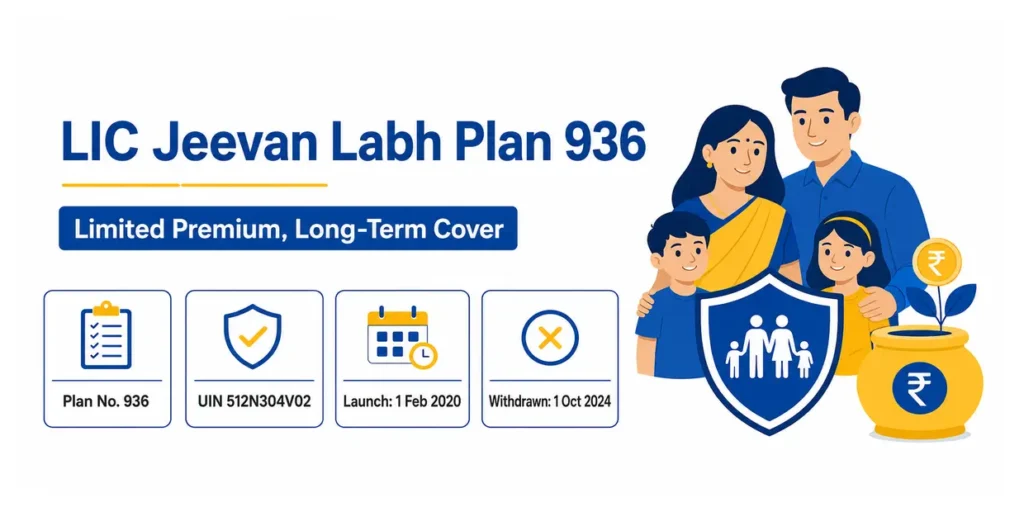
LIC Jeevan Labh Plan 936 was a participating, non-linked, limited-premium endowment plan from Life Insurance Corporation of India. It combined life insurance protection with long-term savings. Premiums were payable for a shorter period than the full policy term, while the life cover continued until maturity as long as the policy remained in force.
The plan was launched on 1 February 2020 and withdrawn from new business on 1 October 2024. Therefore, it cannot be purchased now. Existing policies issued under Plan 936 continue according to their policy terms. The LIC Jeevan Labh Plan 936 Calculator is mainly useful for these policyholders because it provides an indicative estimate of premiums and important policy benefits.
Table of Contents
What Is LIC Jeevan Labh Plan 936 Calculator?
The LIC Jeevan Labh Plan 936 Calculator is an online estimation tool for understanding the possible premium commitment and benefits under the plan. Based on the details entered, it can show the applicable premium-paying term, estimated premium, total base premium, maturity benefit basis and minimum death-cover basis. It may also help estimate paid-up or surrender values when the required policy details and applicable factors are available.
The calculator is not an official LIC quotation or claim-settlement system. Bonus amounts are also not guaranteed in advance. For a more realistic maturity estimate, use the vested bonus shown in the latest LIC policy record. The actual benefit depends on the issued policy, premium history, policy status, vested bonuses, outstanding loan and LIC’s applicable terms.
Also Check:
- LIC Jeevan Labh Calculator All in One
- LIC Jeevan Labh Plan 736 Calculator
- LIC Jeevan Labh Plan 836 Calculator
LIC Jeevan Labh Plan 936 at a Glance
| Feature | Details |
|---|---|
| Plan name | LIC’s Jeevan Labh |
| Plan number | 936 |
| UIN | 512N304V02 |
| Plan type | Participating, non-linked, limited-premium endowment plan |
| Launch date | 1 February 2020 |
| Withdrawal date | 1 October 2024 |
| Policy terms | 16, 21 and 25 years |
| Premium-paying terms | 10, 15 and 16 years respectively |
| Minimum entry age | 8 years completed |
| Maximum maturity age | 75 years |
| Minimum Basic Sum Assured | ₹2,00,000 |
| Sum Assured multiple | ₹10,000 |
| Premium modes | Yearly, half-yearly, quarterly and monthly |
| Policy loan | Available after payment of two full years’ premiums, subject to conditions |
| Current status | Withdrawn for new business |
Highlights of the Calculator
The calculator brings the main policy calculations together instead of requiring separate manual calculations. It automatically connects the selected policy term with the correct premium-paying term, checks the general age limits and displays the premium in the selected payment mode.
It can also separate the guaranteed Basic Sum Assured from non-guaranteed bonus additions. This distinction is important because a large projected maturity amount should not be presented as completely guaranteed. Existing policyholders can use the tool to understand how vested bonus, paid-up status, surrender factors and an outstanding loan may affect the final value.
The calculator is especially useful for comparing the total premium commitment with the maturity benefit basis. However, it should be used for estimation and policy understanding, not as a substitute for the policy bond, LIC servicing statement or official claim quotation.
Eligibility and Available Terms
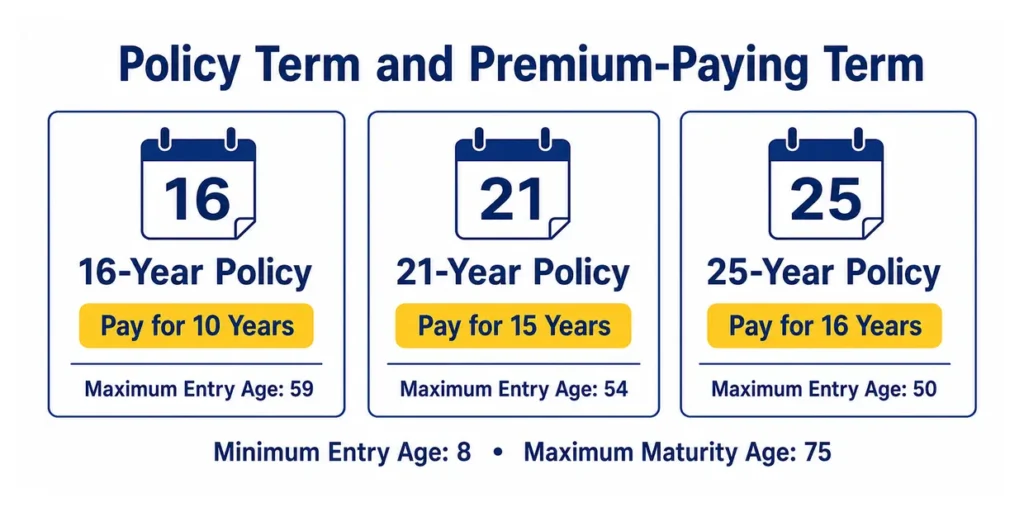
Plan 936 offered three fixed combinations of policy term and premium-paying term. The maximum entry age depended on the selected term.
| Policy term | Premium-paying term | Maximum entry age |
| 16 years | 10 years | 59 years |
| 21 years | 15 years | 54 years |
| 25 years | 16 years | 50 years |
The minimum entry age was eight years completed, and the maximum age at maturity was 75 years. The minimum Basic Sum Assured was ₹2 lakh and higher amounts had to be selected in multiples of ₹10,000. The maximum Basic Sum Assured was subject to LIC’s underwriting decision.
For a policy taken on the life of a child, the policy vested in the life assured on the policy anniversary coinciding with or immediately following completion of 18 years of age, according to the policy conditions.
How to Use LIC Jeevan Labh Plan 936 Calculator
First, enter the age at entry shown in the policy document. This means the age when the policy commenced, not the present age. Select the policy term of 16, 21 or 25 years. The calculator should automatically apply the corresponding premium-paying term of 10, 15 or 16 years.
Next, enter the Basic Sum Assured. It must be at least ₹2,00,000 and in multiples of ₹10,000. Select the premium-payment mode used in the policy. If the calculator asks for an existing policy premium, enter the base premium excluding GST, rider premium and any underwriting extra premium.
For a maturity estimate, enter the vested bonus from the latest policy record. Add a Final Additional Bonus only when an applicable amount is known or when making a clearly labelled assumption. If paid-up, surrender or loan calculations are available, enter the number of premiums actually paid, the surrender year, applicable factors and outstanding loan accurately.
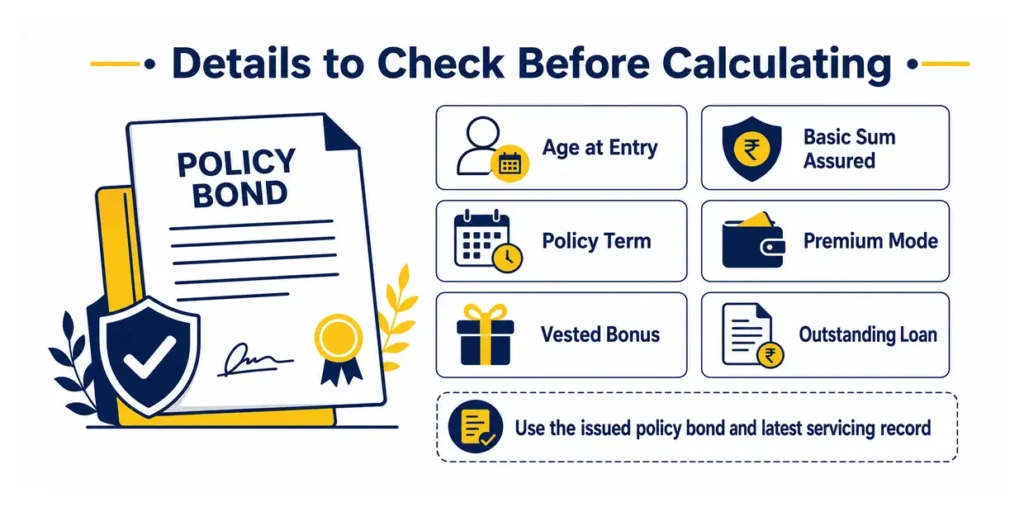
After checking all entries, click Calculate. Read the main result first and then review the premium, maturity, death, paid-up and surrender sections. A calculation warning should be shown whenever the result depends on an assumed bonus or an estimated premium rate.
Formula Used in the Calculator
Premium-paying term
The premium-paying term is fixed according to the selected policy term:
16-year policy term → 10-year premium-paying term
21-year policy term → 15-year premium-paying term
25-year policy term → 16-year premium-paying term
Total base premium
Estimated Total Base Premium =
Base Premium per Instalment × Instalments per Year × Premium-Paying Term
This amount excludes GST, rider premium and any extra premium charged after underwriting.
Maturity benefit
For an eligible in-force policy, the maturity benefit is:
Maturity Benefit =
Basic Sum Assured
+ Vested Simple Reversionary Bonuses
+ Final Additional Bonus, if declared and applicable
The Basic Sum Assured is the guaranteed base component. Future bonuses and Final Additional Bonus are not guaranteed in advance.
Death benefit
The Sum Assured on Death is the higher of:
Basic Sum Assured
or
7 × Annualised Premium
The benefit is then calculated as:
Death Benefit =
Sum Assured on Death
+ Vested Simple Reversionary Bonuses
+ Final Additional Bonus, if applicable
It must not be less than 105% of all eligible premiums actually paid up to the date of death. Taxes, rider premiums and underwriting extra premiums are excluded for this test.
Paid-up value
If the policy has acquired paid-up status, the reduced maturity base can be estimated as:
Paid-up Maturity Sum Assured =
Basic Sum Assured ×
(Number of Premiums Paid ÷ Total Number of Premiums Originally Payable)
The reduced death base is calculated using the applicable Sum Assured on Death and the same premium-payment proportion. Vested bonuses already attached to the policy continue according to the policy terms, but a paid-up policy does not participate in future profits.
Surrender value
The surrender value is the higher of the Guaranteed Surrender Value and Special Surrender Value, where available:
Guaranteed Surrender Value =
Eligible Premiums Paid × Applicable GSV Factor
The surrender value of vested bonuses is calculated separately using the applicable bonus surrender factor. A reliable surrender estimate therefore requires the factors for the relevant policy term and surrender year. A fixed surrender percentage should not be applied to every policy year.
Real Calculation Example
Consider a standard-life sample based on a premium figure shown in the LIC brochure:
| Policy detail | Example value |
| Age at entry | 30 years |
| Policy term | 25 years |
| Premium-paying term | 16 years |
| Premium mode | Yearly |
| Basic Sum Assured | ₹2,00,000 |
| Annual base premium excluding tax | ₹9,134 |
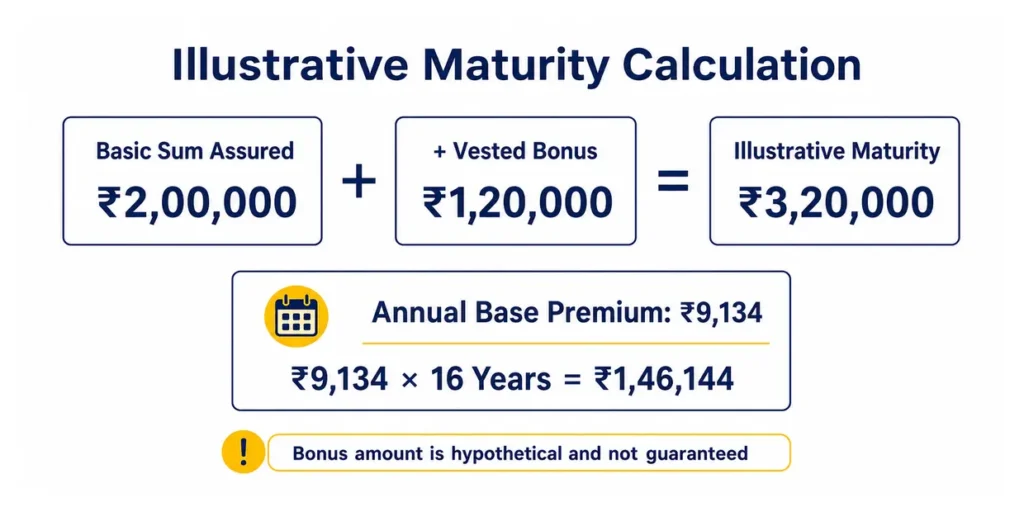
The estimated total base premium over the full premium-paying term is:
₹9,134 × 16 = ₹1,46,144This total assumes that all 16 yearly premiums remain equal and are paid as scheduled. It excludes GST, rider premium and any extra premium.
The base maturity component is ₹2,00,000. Suppose the policy record shows a vested bonus of ₹1,20,000 and no Final Additional Bonus is included. The illustrative maturity amount would be:
₹2,00,000 + ₹1,20,000 = ₹3,20,000The ₹1,20,000 bonus is a hypothetical amount used only to explain the formula. It is not an official bonus projection for this policy.
For the death-benefit calculation:
7 × Annualised Premium =
7 × ₹9,134 = ₹63,938
The higher of ₹2,00,000 and ₹63,938 is ₹2,00,000. Therefore, the Sum Assured on Death in this example is ₹2,00,000.
The 105% test must use only premiums paid up to the date of death. If death occurs after five complete yearly premiums have been paid:
Premiums paid up to death =
₹9,134 × 5 = ₹45,670

105% of premiums paid =
₹45,670 × 105% = ₹47,953.50
Since ₹2,00,000 is higher than ₹47,953.50, the applicable death-benefit base remains ₹2,00,000. Vested bonuses and any applicable Final Additional Bonus would be added according to the policy terms. This example does not represent an official claim quotation.
Premium Modes and Rebates
Premiums could be paid yearly, half-yearly, quarterly or monthly. The mode rebate was 2% of tabular premium for yearly payment and 1% for half-yearly payment. No mode rebate applied to quarterly or monthly payment.
High Sum Assured rebates also applied to eligible slabs. The rebate was nil for a Basic Sum Assured from ₹2,00,000 to ₹4,90,000; ₹1.25 per ₹1,000 Basic Sum Assured from ₹5,00,000 to ₹9,90,000; ₹1.50 per ₹1,000 from ₹10,00,000 to ₹14,90,000; and ₹1.75 per ₹1,000 for ₹15,00,000 and above.
These rebates affect the tabular premium calculation. They should not be subtracted again if the premium entered from the policy document already includes them.
Maturity Benefit and Bonuses
When the life assured survived to the end of the policy term and the policy satisfied the applicable conditions, LIC paid the Basic Sum Assured along with vested Simple Reversionary Bonuses and Final Additional Bonus, if declared and applicable.
As a participating policy, Plan 936 was eligible to share in LIC’s surplus through bonuses. A Simple Reversionary Bonus declared for an eligible policy becomes vested and remains attached to it. Future bonus rates cannot be known in advance because LIC declares them according to its experience and applicable rules. Final Additional Bonus may be declared at death or maturity for qualifying policies, but it should never be treated as guaranteed.
What Happens if Premium Payment Stops?
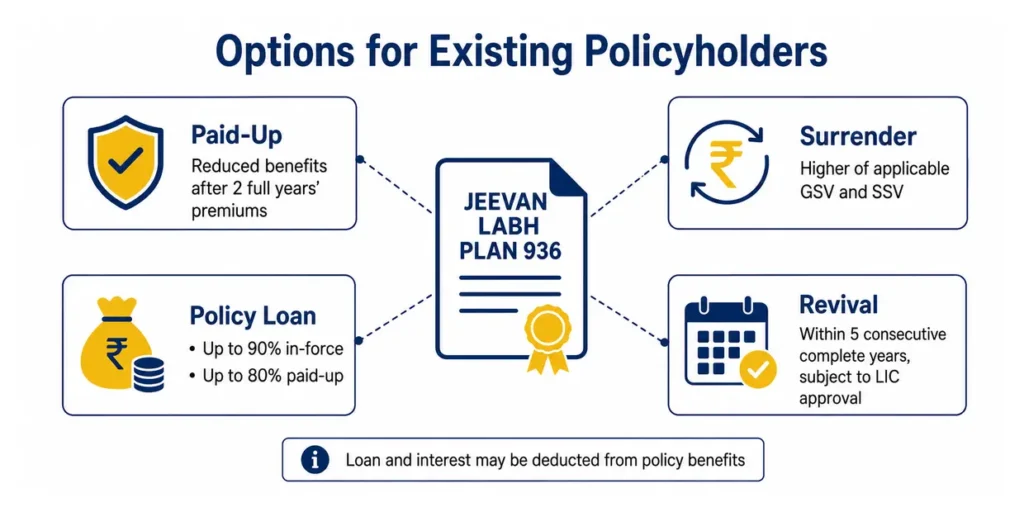
If premiums for less than two full years have been paid, the policy generally lapses after the grace period. If at least two full years’ premiums have been paid, the policy can continue as a paid-up policy with reduced benefits, subject to its conditions.
A paid-up policy does not receive future Simple Reversionary Bonuses. Bonuses already vested remain attached according to the policy terms. The reduced paid-up benefit depends on the number of premiums paid compared with the total originally payable.
A lapsed policy could be revived within five consecutive complete years from the date of the first unpaid premium and before the end of the policy term, subject to LIC’s approval. Revival could require overdue premiums with interest, evidence of insurability and satisfaction of underwriting conditions.
Surrender Value and Policy Loan
The policy acquired a surrender value after payment of at least two full years’ premiums. LIC paid the higher of the applicable Guaranteed Surrender Value and Special Surrender Value. The result depended on the term, surrender year, eligible premiums paid, vested bonuses and factors applicable to that policy.
A policy loan was available after payment of at least two full years’ premiums. The maximum was up to 90% of surrender value for an in-force policy and up to 80% for a paid-up policy, subject to LIC’s conditions. Interest applied separately. Any outstanding loan and interest could be deducted from surrender, maturity or death benefits.
Grace Period, Free Look and Settlement Options
The grace period was 30 days for yearly, half-yearly and quarterly premiums and 15 days for monthly premiums. Cover continued during the grace period according to the policy terms. If the premium remained unpaid after it ended, the policy could lapse or become paid-up depending on the premium history.
The applicable free-look period should be checked in the issued policy document because the period can depend on how the policy was purchased or delivered. A cancellation during the permitted period was subject to deductions allowed under the policy conditions.
The maturity benefit could be taken in instalments over 5, 10 or 15 years instead of entirely as a lump sum. A similar option was available for full or part of the death benefit. Instalment amounts depended on the option selected and LIC’s applicable interest rate. The minimum instalment amounts were ₹5,000 monthly, ₹15,000 quarterly, ₹25,000 half-yearly and ₹50,000 yearly.
Riders Available Under Plan 936
Subject to eligibility and payment of additional premium, Plan 936 offered riders such as Accidental Death and Disability Benefit, Accident Benefit, New Term Assurance, New Critical Illness Benefit and Premium Waiver Benefit. The two accident-related riders could not be selected together. Availability, entry conditions, cover limits and the permitted time of selection depended on the individual rider terms.
Rider benefits should be calculated separately from the base-policy maturity value. Rider premiums do not form part of the maturity benefit or surrender value of the base policy.
FAQs
Is LIC Jeevan Labh Plan 936 still available?
No. The plan was withdrawn from new business on 1 October 2024. Policies issued before withdrawal continue according to their terms.
What is the maturity benefit under Plan 936?
For an eligible in-force policy, it consists of the Basic Sum Assured, vested Simple Reversionary Bonuses and Final Additional Bonus, if declared and applicable.
Is the entire maturity amount guaranteed?
No. The Basic Sum Assured is the guaranteed base maturity component. Future bonuses and Final Additional Bonus are not guaranteed in advance.
How is the death benefit calculated?
The Sum Assured on Death is the higher of the Basic Sum Assured and seven times the annualised premium. Vested bonuses and any applicable Final Additional Bonus are added. The result is also subject to a minimum of 105% of eligible premiums paid up to the date of death.
When does the policy acquire paid-up value?
The policy can acquire paid-up status after at least two full years’ premiums have been paid. Its death and maturity benefits are then reduced according to the applicable policy formula.
When can Plan 936 be surrendered?
It can be surrendered after at least two full years’ premiums have been paid. The payable value is determined using the applicable Guaranteed or Special Surrender Value rules.
Can a loan be taken against the policy?
Yes. After at least two full years’ premiums have been paid, a loan may be available against the surrender value, subject to LIC’s conditions and applicable interest.
Conclusion
LIC Jeevan Labh Plan 936 provided a combination of limited premium payment, life cover and a maturity benefit linked to the Basic Sum Assured and participating bonuses. Although the plan is closed to new customers, existing policyholders may still need to estimate premiums, maturity benefits, paid-up values, surrender values and loan-adjusted proceeds.
The LIC Jeevan Labh Plan 936 Calculator makes these calculations easier to understand, but its results remain indicative. The policy bond, premium history, vested bonus statement, surrender factors, outstanding loan and official LIC servicing records should be checked before making a financial decision or relying on a final claim amount.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.