The LIC Navjeevan Plan 853 Calculator helps estimate the maturity amount, death benefit, paid-up value, Guaranteed Surrender Value and loan eligibility of an existing policy. It supports both payment choices offered under the plan: Single Premium and five-year Limited Premium.
LIC Navjeevan is a savings and life insurance policy. It paid the Basic Sum Assured at maturity and could also pay a Loyalty Addition when LIC declared it and the policy met the required conditions.
Plan status: LIC Navjeevan Plan 853 was available from 13 March 2019 to 16 August 2019. It is now withdrawn and cannot be purchased. Existing policies continue according to their original terms and present status.
Table of Contents
What LIC Navjeevan Plan 853 Calculator Estimate?
The calculator is mainly useful for existing Plan 853 policyholders. It uses the policy information which is given by the policyholder bond, including the premium option, age when the policy started, policy term, Basic Sum Assured and premium amount.
For a Single Premium policy, it can estimate the maturity amount, death benefit, Guaranteed Surrender Value and loan limit. For a Limited Premium policy, it can also estimate reduced benefits after premiums are stopped.
The calculator may include an entered Loyalty Addition to show an estimated maturity or death benefit. This amount must remain separate because Loyalty Addition was not guaranteed.
LIC Navjeevan Plan 853 Overview
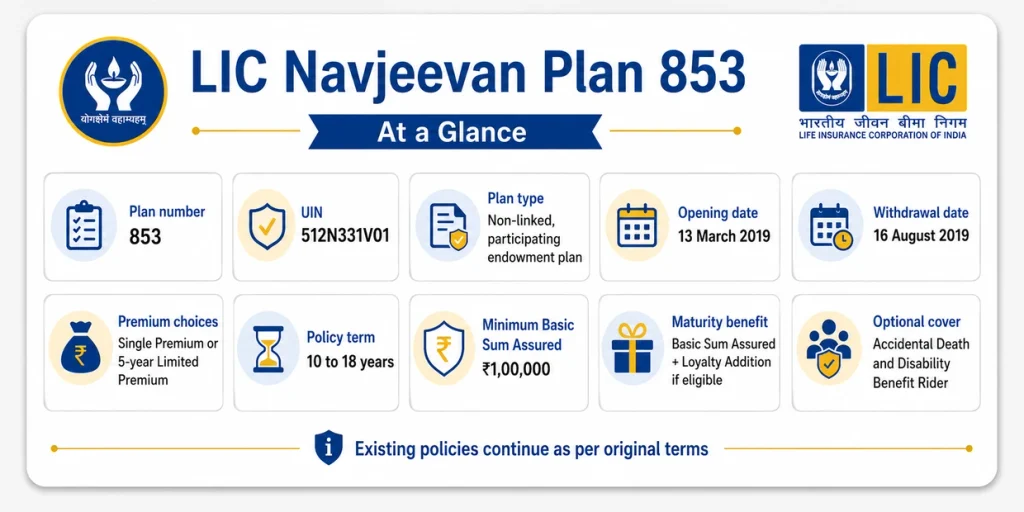
| Particular | Plan detail |
|---|---|
| Plan name | LIC’s Navjeevan |
| Plan number | 853 |
| UIN | 512N331V01 |
| Plan type | Non-linked, participating endowment plan |
| Opening date | 13 March 2019 |
| Withdrawal date | 16 August 2019 |
| Premium choices | Single Premium or five-year Limited Premium |
| Policy term | 10 to 18 years |
| Minimum Basic Sum Assured | ₹1,00,000 |
| Maximum Basic Sum Assured | No fixed limit, subject to LIC approval |
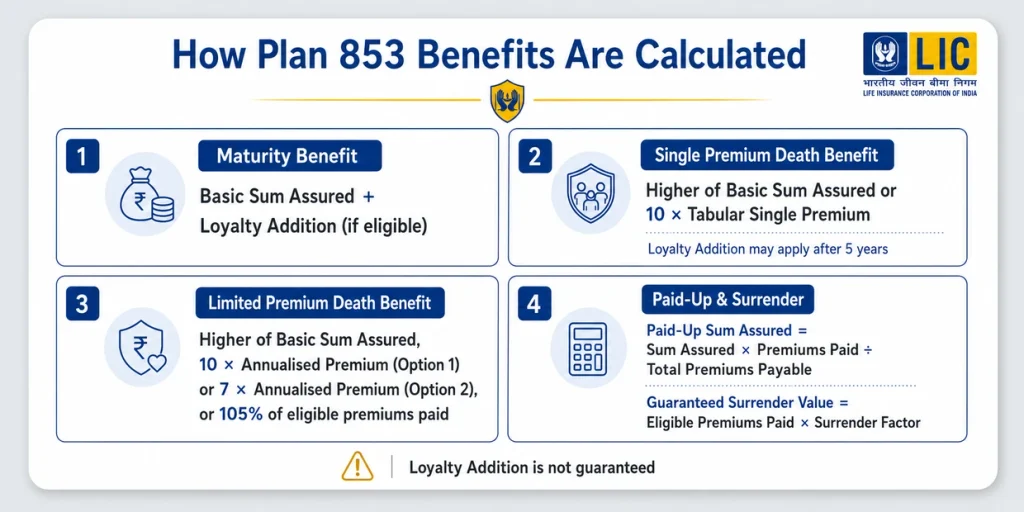
| Maturity benefit | Basic Sum Assured plus Loyalty Addition, if eligible |
| Optional cover | Accidental Death and Disability Benefit Rider |
| Policy loan | Available after meeting the conditions for the selected premium option |
The Basic Sum Assured had to follow these multiples:
| Premium option | Basic Sum Assured range | Required multiple |
| Single Premium | ₹1,00,000 to ₹9,00,000 | ₹20,000 |
| Single Premium | Above ₹9,00,000 | ₹50,000 |
| Limited Premium | ₹1,00,000 to ₹9,00,000 | ₹20,000 |
| Limited Premium | Above ₹9,00,000 | ₹25,000 |
What is LIC Navjeevan Plan 853?
LIC Navjeevan is an endowment policy that combined life cover with a maturity payment. It was not linked to the share market, mutual funds or NAV. The benefit depended on the selected policy details and any Loyalty Addition declared by LIC.
The policy could be taken for a term of 10 to 18 years. The main difference from many other endowment plans was the choice between paying the full premium once or paying premiums for only five years.
The plan was available for children and adults. However, when the insured child was below eight years at entry, full life cover did not always start immediately. This rule is explained separately because it affects the death-benefit calculation.
Choose the Correct Premium Option
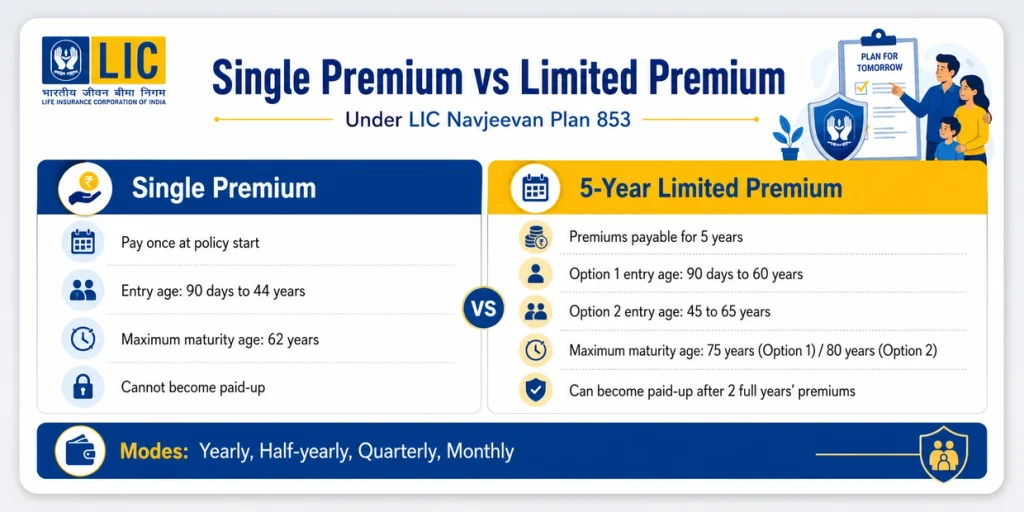
Single Premium
Under this option, the full premium was paid once when the policy started. No regular premium was required later.
The entry age ranged from 90 days to 44 years. The maximum age at maturity was 62 years. A Single Premium policy could not become paid-up because the required premium had already been paid in full.
Five-Year Limited Premium
Under this option, premiums were payable for five years while the policy continued for the full selected term.
Limited Premium offered two death-benefit choices. Option 1 was available from 90 days to 60 years of entry age. Option 2 was available only from age 45 to 65 years. The maximum maturity age was 75 years under Option 1 and 80 years under Option 2.
Premiums could be paid yearly, half-yearly, quarterly or monthly through the arrangements allowed by LIC.
How to Use the Calculator
Enter all required values for the policy document for exact result.
- Select Single Premium or Limited Premium exactly as shown on the policy.
- Enter the age when the policy started, not the present age.
- Enter the Basic Sum Assured and policy term.
- For Limited Premium, select Death Benefit Option 1 or Option 2.
- Enter the tabular premium or annual premium requested by the calculator.
- Enter the number of full premiums paid when checking paid-up or surrender value.
- Add Loyalty Addition only when using an official amount or a clearly marked estimate.
- Press Calculate and read the fixed and estimated amounts separately.
Do not include tax, rider premium or any extra premium charged by LIC in the amounts used for benefit calculations.
How Premium Is Estimated via Navjeevan Plan 853 Calculator
An exact Plan 853 premium requires the original LIC rate for the insured person’s age, policy term, Basic Sum Assured and selected option. The brochure does not provide the full rate table for every possible policy.
For the most accurate result, use the premium shown on the policy bond. A calculator should not guess an unavailable LIC rate.
Under Limited Premium, LIC added an extra percentage when premiums were paid more often than yearly:
| Payment mode | Extra charge on tabular annual premium |
| Yearly | Nil |
| Half-yearly | 2% |
| Quarterly | 3% |
| Monthly through permitted arrangements | 3.5% |
High Basic Sum Assured and online-sale rebates could reduce the original premium. Tax, rider premium and any health-related extra premium were added separately.
For death-benefit calculations, Annualised Premium means the tabular premium for one full year after adding the payment-mode charge but before deducting High Sum Assured, online-sale or other allowed rebates. It does not include tax, rider premium or any extra premium charged by LIC.
Maturity Amount and Loyalty Addition
For an active policy where all required premiums have been paid, the maturity calculation is:
Maturity Benefit
= Basic Sum Assured
+ Loyalty Addition, if declared and eligible
The Basic Sum Assured is the main amount payable at maturity. Loyalty Addition was not fixed and was not added every year like an annual bonus.
The policy became eligible for Loyalty Addition after completing five policy years when all premiums due had been paid. LIC could consider it at maturity or on an eligible death after five policy years. It was not payable under a paid-up policy.
Death Benefit under Single Premium
After life cover started, the Sum Assured on Death under Single Premium was the higher of:
1. Basic Sum Assured
2. 10 × Tabular Single Premium before rebates
Death Benefit
= Sum Assured on Death
+ Loyalty Addition, if death occurs after five policy years and it is eligibleThe Tabular Single Premium used here is the amount based on age and Basic Sum Assured before High Sum Assured, online-sale or other rebates. It excludes tax, rider premium and any extra premium.
Death Benefit under Limited Premium
Limited Premium offered two choices for the death-cover multiple.
Option 1: Ten Times Annualised Premium
Option 1 used ten times the Annualised Premium. The Sum Assured on Death was the higher of:
1. Basic Sum Assured
2. 10 × Annualised Premium
3. 105% of eligible premiums paid up to death
Option 2: Seven Times Annualised Premium
Option 2 used seven times the Annualised Premium. It was available only when the entry age was 45 years or above.
1. Basic Sum Assured
2. 7 × Annualised Premium
3. 105% of eligible premiums paid up to death
For either option, an eligible Loyalty Addition could be added when death occurred after completion of five policy years.
When Does Life Cover Start for a Child?
When the insured child was below eight years at entry, life cover started on the earlier of these two dates:
- one day before completing two years from the policy start date; or
- one day before the policy anniversary on or after the child completed eight years of age.
If death happened before life cover started, LIC refunded eligible premiums paid without interest. The normal Sum Assured on Death applied only after life cover had started.
For an insured person aged eight years or more at entry, life cover started when LIC accepted and issued the policy.
Paid-Up Value after Stopping Premiums
Paid-up value applied only to Limited Premium policies. A policy could become paid-up after at least two full years’ premiums had been paid.
If premiums stopped before completing two full years, the policy normally lapsed after the grace period without paid-up benefits. If two or more full years’ premiums had been paid, the policy continued with lower death and maturity benefits.
Maturity Paid-Up Sum Assured
= Basic Sum Assured
× Number of Premiums Paid
÷ Total Premiums Payable
Death Paid-Up Sum Assured
= Sum Assured on Death
× Number of Premiums Paid
÷ Total Premiums PayableBecause the premium-paying term was five years, the yearly-mode ratio would be the number of full yearly premiums paid divided by five. The matching number of instalments applies for other payment modes.
Loyalty Addition was not payable under a paid-up policy. Rider benefits also stopped when the policy lapsed and did not receive a paid-up value.
Surrender Value Calculation
A Single Premium policy could be surrendered during the policy term. The Guaranteed Surrender Value was:
| Surrender time | Guaranteed Surrender Value |
| During the first policy year | 70% of eligible Single Premium |
| After the first policy year | 90% of eligible Single Premium |
A Limited Premium policy could be surrendered after at least two full years’ premiums had been paid.
Limited Premium Guaranteed Surrender Value
= Eligible Premiums Paid
× Applicable Surrender Factor
The surrender factor depended on both the policy term and surrender year. LIC paid the higher of Guaranteed Surrender Value or Special Surrender Value.
Loyalty Addition was not part of the normal Guaranteed Surrender Value formula. After five policy years, it could be considered while LIC calculated Special Surrender Value when all required premiums had been paid.
Policy Loan Availability
A loan was available against the policy’s surrender value after meeting the conditions below:
| Policy type or status | Loan condition | Maximum loan |
| Single Premium | After three months from issue or the end of the free-look period, whichever was later | Up to 80% of surrender value |
| Limited Premium, active | After two full years’ premiums | Up to 80% of surrender value |
| Limited Premium, paid-up | After two full years’ premiums | Up to 70% of surrender value |
LIC decided the loan interest rate from time to time. Any unpaid loan and interest could be deducted from maturity, surrender or death payments.
Real Calculation Example
Consider a Limited Premium policy with these details:
| Policy detail | Example value |
| Death-benefit choice | Option 1 |
| Entry age | 35 years |
| Policy term | 15 years |
| Basic Sum Assured | ₹5,00,000 |
| Annualised Premium for death calculation | ₹60,000 |
| Eligible yearly premium actually paid | ₹56,500 |
| Premium-paying term | 5 years |
Death Benefit
Suppose death happens after completion of policy year six and all five premiums have been paid.
Basic Sum Assured = ₹5,00,000

10 × Annualised Premium
= 10 × ₹60,000
= ₹6,00,000

105% of Eligible Premiums Paid
= 105% × (₹56,500 × 5)
= ₹2,96,625
The highest amount is ₹6,00,000. An eligible Loyalty Addition may also be added because death happened after completion of five policy years.
Maturity Benefit
If the policy remains active until maturity, the fixed maturity amount is ₹5,00,000. If LIC confirms a Loyalty Addition of ₹40,000, the estimated maturity amount becomes:
₹5,00,000 + ₹40,000
= ₹5,40,000
The ₹40,000 used here is only an example and is not a promised amount.
Paid-Up Value
If only three of the five yearly premiums are paid:
Maturity Paid-Up Sum Assured
= ₹5,00,000 × 3 ÷ 5
= ₹3,00,000

Death Paid-Up Sum Assured
= ₹6,00,000 × 3 ÷ 5
= ₹3,60,000
No Loyalty Addition would be payable after the policy became paid-up.
Guaranteed Surrender Value
Suppose all five eligible yearly premiums of ₹56,500 were paid and the policy was surrendered in policy year eight. For a 15-year policy, the applicable factor was 54.29%.
Eligible Premiums Paid
= ₹56,500 × 5
= ₹2,82,500

Guaranteed Surrender Value
= ₹2,82,500 × 54.29%
= ₹1,53,369.25
LIC could pay a higher Special Surrender Value. Any unpaid policy loan and interest would reduce the final payment.
Important Points for Existing Policies
- Confirm whether the policy is Single Premium or Limited Premium before calculating.
- Under Limited Premium, check whether Death Benefit Option 1 or Option 2 was selected.
- Use the premium figures printed on the policy bond whenever possible.
- Keep Loyalty Addition separate because it was not guaranteed.
- A Limited Premium policy required two full years’ premiums before receiving paid-up or surrender value.
- A child policy may have a later life-cover start date.
- Surrender ends the policy and all future benefits.
- LIC’s records and final quotation decide the actual payable amount.
Frequently Asked Questions
Is LIC Navjeevan Plan 853 still available?
No. Plan 853 was withdrawn on 16 August 2019. New policies cannot be purchased, but existing policies continue according to their original terms and present status.
What is the maturity benefit under Plan 853?
For an active policy, the maturity benefit is the Basic Sum Assured plus Loyalty Addition, if LIC declares it and the policy meets the conditions. Any unpaid loan and interest may be deducted.
How is the death benefit calculated?
The formula depends on the premium option. Single Premium compares the Basic Sum Assured with ten times the Tabular Single Premium. Limited Premium compares the Basic Sum Assured with the selected annual-premium multiple and 105% of eligible premiums paid.
When does a Limited Premium policy become paid-up?
It can continue with reduced paid-up benefits after at least two full years’ premiums have been paid. Loyalty Addition and rider benefits are not available under a paid-up policy.
Is Loyalty Addition guaranteed?
No. LIC decides whether to declare it and what rate will apply. The policy must also complete five years and meet the required premium conditions.
Conclusion
The LIC Navjeevan Plan 853 Calculator helps explain an existing policy by separating the rules for Single Premium and five-year Limited Premium. It can estimate maturity, death, paid-up, surrender and loan values using information from the policy bond.
The Basic Sum Assured forms the main maturity benefit, while Loyalty Addition depends on LIC’s declaration. Death, surrender and loan calculations change according to the selected premium option, so choosing the correct route in the calculator is essential.
Plan 853 is withdrawn and cannot be purchased. LIC’s official policy record and final calculation will decide the actual amount payable under an existing policy.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.