LIC Bima Platinum Plan 770 Calculator
Check plan benefits without a premium or calculate complete benefits from an existing policy.
Policy details
Death claim details
Paid-up details
Policy benefit result
Premium payment options
Year-wise policy schedule
| Year | Base premium | Guaranteed Addition | Yearly income | Booster | Maturity |
|---|
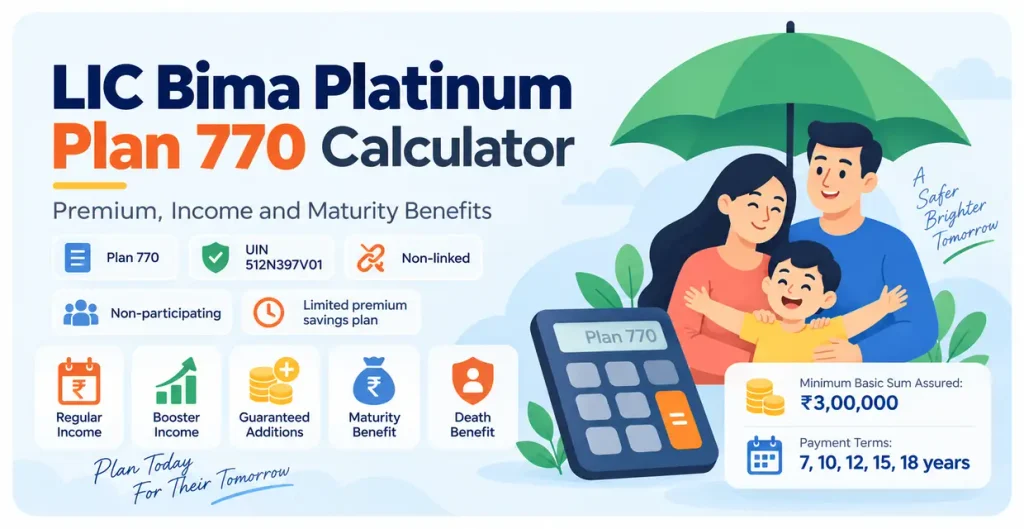
LIC Bima Platinum Plan 770 is a savings and protection plan with limited premium payment. In this plan, policyholders will receive a regular income benefit during the payout period, a booster income benefit at a fixed policy anniversary, and a maturity benefit at the end of the policy term. Guaranteed Additions accrue during the Premium Paying Term.
LIC Bima Platinum calculator explains each benefit separately. It does not show all scheduled payments as one maturity amount. A person who is planning to buy this policy can calculate the main benefits without entering a premium. An existing policyholder enters the yearly base premium to calculate Guaranteed Additions, premium instalments, death benefits, and paid-up benefits.
LIC launched Bima Platinum as Plan 770 with UIN 512N397V01 under its Endowment Plans, and its available for sale from 7 September 2026 to 31 March 2027.
Table of Contents
LIC Bima Platinum Plan 770 Highlights
| Plan detail | Official rule |
|---|---|
| Plan number | 770 |
| UIN | 512N397V01 |
| Plan type | Non-linked, non-participating, individual savings plan |
| Minimum Basic Sum Assured | ₹3,00,000 |
| Basic Sum Assured steps | Multiples of ₹10,000 |
| Premium Paying Terms | 7, 10, 12, 15 or 18 years |
| Policy Term | 17 to 40 years, depending on the selected Premium Paying Term and maturity age |
| Regular Income | 10% of Basic Sum Assured each year during the payout period |
| Booster Income | 70% of Basic Sum Assured at the specified policy anniversary |
| Basic maturity amount | 100% of Basic Sum Assured |
| Guaranteed Addition base rate | ₹70 per ₹1,000 of cumulative annualized premiums paid |
| Maximum maturity age | 75 years under the standard route |
This plan is not a traditional bonus plan. It uses a fixed Guaranteed Addition formula and extra Guaranteed Addition rates for eligible cases.
LIC Bima Platinum Plan 770 Calculator
The LIC Bima Platinum Plan 770 Calculator is an online tool that is based on the LIC official brochure, which helps to estimate the benefits written into the plan using the age, Payment Term, Policy Term, Basic Sum Assured and, for a complete policy calculation, the yearly base premium.
It shows yearly and total Regular Income, Booster Income, income received before maturity, the maturity amount, Guaranteed Additions, complete scheduled benefits, premium instalments, death benefit, paid-up benefit and a year-wise policy schedule.
The calculator has two options; it’s designed to help both people who someone planing to buy a policy and also someone alredy buy this policy.
- Check Plan Benefits — Not a Policyholder requires age, Payment Term, Policy Term and Basic Sum Assured. It calculates Regular Income, Booster Income and the basic maturity amount; it does not ask for the premium.
- Complete Calculation — Existing Policyholder also requires the yearly base premium and relevant policy details. It calculates Guaranteed Additions, premium options, complete benefits, death benefit, and paid-up benefit.
What Is Bima Platinum Plan 770?
LIC Bima Platinum is a Non-Par, Non-Linked, Life, Individual, Savings Plan. “Non-Par” means the plan does not share in LIC’s surplus and does not receive discretionary bonuses. LIC uses the term Guaranteed Additions in its plan brochure, which refers to the fixed additions under the plan.
It is a limited-premium plan. The Premium Paying Term is shorter than, or equal to, the Policy Term. The available Premium Paying Terms are 7, 10, 12, 15 and 18 years. The Policy Term starts at 17 years for a 7-year Payment Term, 20 years for a 10-year Payment Term, 22 years for a 12-year Payment Term, 25 years for a 15-year Payment Term and 28 years for an 18-year Payment Term. The maximum Policy Term is 40 years, subject to the maturity-age limit.
The plan provides three main survival benefits:
- Regular Income Benefit during the payout period.
- Booster Income Benefit at the specified policy anniversary.
- Sum Assured on Maturity plus accrued Guaranteed Additions at the end of the Policy Term.
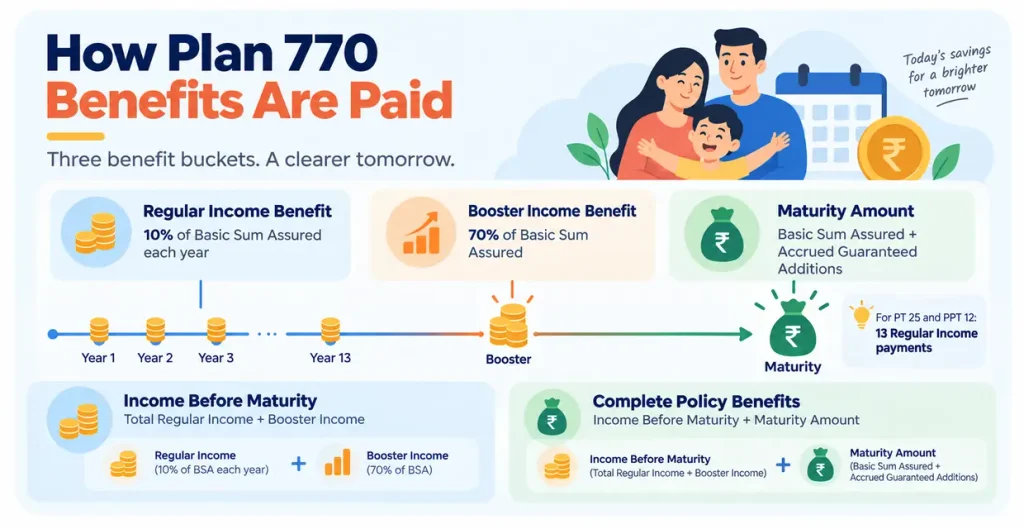
LIC Bima Platinum Plan 770 Benefits Explained
Regular Income Benefit
The Regular Income Benefit is 10% of the Basic Sum Assured. It starts at the end of the Premium Paying Term and continues at the end of each subsequent Policy Year until the policy anniversary before maturity, provided the policy is in force and the Life Assured survives.
The number of Regular Income payments is: Policy Term − Premium Paying Term
For example, a 25-year Policy Term and a 12-year Payment Term provide 13 Regular Income payments, from the end of year 12 to the end of year 24.
Booster Income Benefit
The Booster Income Benefit is 70% of the Basic Sum Assured. It is payable on survival at the policy anniversary specified for the selected Payment Term:
| Payment Term | Booster payment anniversary |
|---|---|
| 7 years | 12th policy anniversary |
| 10 years | 15th policy anniversary |
| 12 years | 17th policy anniversary |
| 15 years | 20th policy anniversary |
| 18 years | 23rd policy anniversary |
We see Booster Income separately in the calculator result because it is paid before maturity and is not part of the maturity amount.
Maturity Benefit
The Sum Assured on Maturity is equal to the Basic Sum Assured. At maturity, the policy pays:
Maturity Amount = Basic Sum Assured + Accrued Guaranteed Additions
This amount is payable when the Life Assured survives to the stipulated maturity date and the policy is in force.
Guaranteed Additions
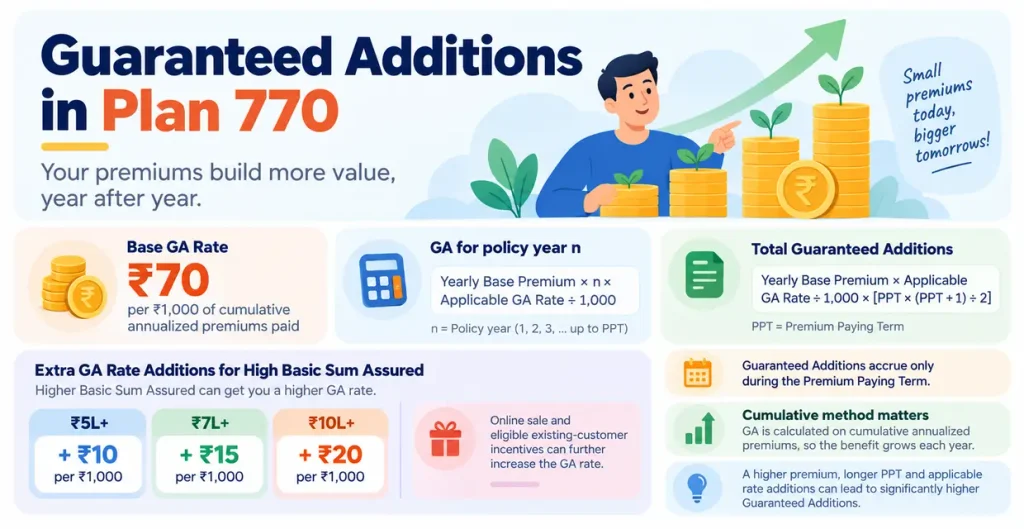
For an in-force policy, Guaranteed Additions accrue at the end of each policy year during the Premium Paying Term. The base rate is ₹70 per ₹1,000 of total annualized premiums paid up to that policy year. No further Guaranteed Additions accrue after the Premium Paying Term.
The applicable rate increases when the policy qualifies for an incentive, such as the High Basic Sum Assured incentive, Online Sale incentive or eligible existing-policyholder incentive. The calculator adds only the incentive selected in the existing-policyholder details.
For a yearly premium, the calculation for policy year n is:
Guaranteed Addition for policy year n = Yearly base premium × n × Applicable GA rate ÷ 1,000
The total at the end of the Premium Paying Term is:
Total Guaranteed Additions = Yearly base premium × Applicable GA rate ÷ 1,000 × [PPT × (PPT + 1) ÷ 2]
This cumulative method is important. Multiplying one year’s addition only by the Premium Paying Term produces an incorrect result.
High Basic Sum Assured Addition to the GA Rate
The values below are added to the base rate of ₹70 per ₹1,000.
| Payment Term | ₹3 lakh to below ₹5 lakh | ₹5 lakh to below ₹7 lakh | ₹7 lakh to below ₹10 lakh | ₹10 lakh and above |
|---|---|---|---|---|
| 7 years | 0 | 3 | 6 | 8 |
| 10 years | 0 | 4 | 7 | 9 |
| 12 years | 0 | 5 | 8 | 10 |
| 15 years | 0 | 6 | 10 | 12 |
| 18 years | 0 | 7 | 12 | 15 |
An eligible direct online purchase adds 30 for Payment Terms 7 and 10, 24 for 12, 22 for 15 and 20 for 18. The eligible existing-customer addition is 1, 1.25, 1.5, 1.75 or 2 for the same respective Payment Terms. Eligibility must match LIC’s proposal records; the rates are not selected merely to increase the result.
Understanding the Bima Platinum Calculator Results
These three results must not be treated as the same amount.
- Total Income Before Maturity = Total Regular Income + Booster Income
The money is scheduled during the Policy Term. It is not paid as one lump sum at maturity.
2. Amount Payable at Maturity = Basic Sum Assured + Total Guaranteed Additions
This is the amount connected with the maturity date.
3. Complete Policy Benefits = Income Received Before Maturity + Amount Payable at Maturity
The complete-policy total is not a single payment. It combines money received during the payout period with the maturity payment received at the end.
How to Use LIC Bima Platinum Plan 770 Calculator
The calculator has two options for policyholders and non-policyholders
1. Check Plan Benefits — Not a Policyholder
Use this choice when the yearly premium is not known.
- Select Check Plan Benefits — Not a Policyholder.
- Enter the age at policy start.
- Select a Payment Term.
- Select a Policy Term from the valid options shown for that age and Payment Term.
- Enter the Basic Sum Assured.
- Select Calculate.
- Read the separate sections for income before maturity, amount payable at maturity and complete policy benefits.
This mode does not show value for Guaranteed Additions because the calculation needs the yearly base premium.
2. Complete Calculation — Existing Policyholder
Use this choice when the policy quotation or policy documents are available or know the yearly base premium.
- Select Complete Calculation — Existing Policyholder.
- Choose Full policy benefits, Death benefit or Paid-up benefits.
- Enter age, Payment Term, Policy Term and Basic Sum Assured.
- Enter the yearly base premium before tax, riders and extra charges.
- Select the current payment frequency.
- Select the purchase route and applicable existing-policyholder incentive.
- Add death-year or paid-up details when that calculation is selected.
- Select Calculate.
The detailed result includes the Guaranteed Addition rate, premium payment options, benefit totals, and year-wise policy schedule.
Premium Payment Options
This plan provides premium payment at yearly, half-yearly, quarterly, or monthly intervals. Monthly payments are through e-NACH/NACH only or through the permitted salary-deduction route.
The calculator starts with the known yearly base premium and applies LIC’s official conversion factors:
| Payment mode | Conversion factor | Calculation |
|---|---|---|
| Yearly | 1.0000 | Yearly premium × 1.0000 |
| Half-Yearly | 0.5090 | Yearly premium × 0.5090 |
| Quarterly | 0.2568 | Yearly premium × 0.2568 |
| Monthly | 0.0861 | Yearly premium × 0.0861 |
For example, if the yearly base premium is ₹1,00,000, the calculator shows ₹50,900 for each Half-Yearly instalment, ₹25,680 for each Quarterly instalment, and ₹8,610 for each Monthly instalment. These are base-premium figures before tax, riders, and other extra charges.
Official Sample Annual Premiums
Here’s the sample annual base premiums for a ₹3,00,000 Basic Sum Assured, 30-year Policy Term, standard life and offline sale. These samples explain how age and Payment Term change the premium; they are not a complete premium table.
| Age | 7-year Payment Term | 10-year | 12-year | 15-year | 18-year |
|---|---|---|---|---|---|
| 15 | ₹81,810 | ₹54,735 | ₹43,020 | ₹32,145 | ₹24,990 |
| 25 | ₹83,145 | ₹55,275 | ₹43,290 | ₹32,220 | ₹25,005 |
| 35 | ₹87,495 | ₹57,015 | ₹44,160 | ₹32,445 | ₹25,005 |
| 45 | ₹1,00,365 | ₹62,025 | ₹46,770 | ₹33,465 | ₹25,425 |
The final premium depends on the exact age, Basic Sum Assured, Policy Term, Payment Term, purchase route, underwriting, and rider selection. A complete calculation must use the annual base premium printed in the LIC quotation or policy document.
Official LIC Bima Platinum Plan 770 Calculation Example
In this calculation, we use the LIC official sales brochure, which includes this benefit illustration:
- Age at policy start: 35 years
- Payment Term: 12 years
- Policy Term: 25 years
- Basic Sum Assured: ₹10,00,000
- Yearly base-plan premium: ₹1,46,650
- Purchase route: Offline
- Sum Assured on Death at the start: ₹16,13,150
The ₹10 lakh Basic Sum Assured adds 10 to the base Guaranteed Addition rate for a 12-year Payment Term. The applicable rate is therefore ₹80 per ₹1,000. The brochure’s year-wise figures confirm the calculation below.
Yearly Regular Income : ₹10,00,000 × 10% = ₹1,00,000 per year
Total Regular Income:
Number of payments = 25 − 12 = 13 Total Regular Income = ₹1,00,000 × 13 = ₹13,00,000
Booster Income: ₹10,00,000 × 70% = ₹7,00,000
For a 12-year Payment Term, the Booster Income is scheduled at the 17th policy anniversary.
Guaranteed Additions:
Guaranteed Addition in year 1 = ₹1,46,650 × 1 × ₹80 ÷ ₹1,000 = ₹11,732
Guaranteed Addition in year 2 = ₹1,46,650 × 2 × ₹80 ÷ ₹1,000 = ₹23,464
The same cumulative calculation continues through year 12:
Total Guaranteed Additions at the end of year 12 = ₹11,732 × (1 + 2 + … + 12) = ₹11,732 × 78 = ₹9,15,096
Amount Payable at Maturity: ₹10,00,000 + ₹9,15,096 = ₹19,15,096
Complete Policy Benefits:
Income before maturity = ₹13,00,000 + ₹7,00,000 = ₹20,00,000 Complete policy benefits = ₹20,00,000 + ₹19,15,096 = ₹39,15,096
The result is ₹13,00,000 in Regular Income from years 12 to 24, ₹7,00,000 Booster Income at the end of year 17, and ₹19,15,096 at maturity in year 25. Total scheduled benefits across the policy equal ₹39,15,096.
The complete-policy figure is not a return percentage and is not paid at one time. It is the arithmetic total of 13 income payments, one Booster payment, and the maturity payment. It also does not deduct the premiums paid or account for the timing of each cash flow.
Death Benefit Calculation
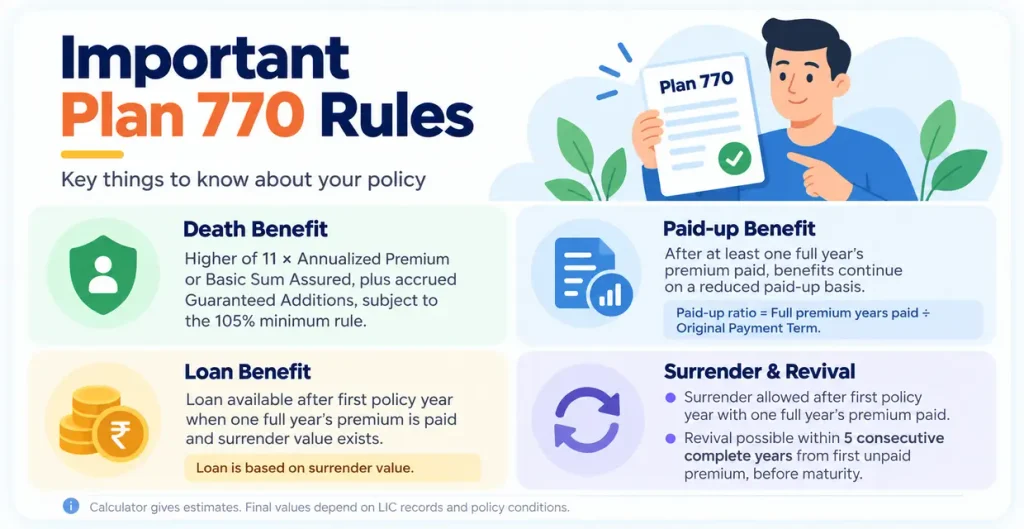
For an in-force policy, the Sum Assured on Death is the higher of:
11 × Annualized Premium
or
Basic Sum Assured
Accrued Guaranteed Additions are added to the Sum Assured on Death. The Death Benefit is not less than 105% of the total base premiums paid up to the date of death, and it is not less than the applicable surrender value.
LIC defines Annualized Premium as the yearly base premium excluding taxes, rider premiums, underwriting extra premiums, and modal loadings. Total Premiums Paid excludes extra premiums, rider premiums, and taxes collected separately.
Paid-Up Benefit Calculation
After at least one full year’s premium has been paid, a policy that stops receiving later premiums continues as a paid-up policy after the grace period, subject to the policy conditions. A policy with less than one full year’s premium paid receives no paid-up benefit after the grace period.
The paid-up calculation uses the proportion of the Payment Term completed:
Paid-up ratio = Full premium years paid ÷ Original Payment Term
LIC Bima Platinum Surrender Value
Plan 770 permits surrender after completion of the first policy year when at least one full year’s premium has been paid. After surrender, the policy ends, and no death, income, or maturity benefit remains payable.
LIC compares the applicable Guaranteed Surrender Value with the Special Surrender Value and pays the higher amount. Guaranteed Surrender Value becomes available after two consecutive years’ premiums have been paid. Its calculation uses LIC’s surrender factors for the selected Policy Term and surrender year, along with the surrender value of accrued Guaranteed Additions. Regular Income or Booster Income already paid is adjusted according to the policy formula.
LIC Bima Platinum Loan Benefit
A policy loan becomes available after completion of the first policy year when one full year’s premium has been paid, and the policy has acquired surrender value. The loan limit is calculated from surrender value, not from the Basic Sum Assured.
| Policy status during Payment Term | Before two full years’ premiums | After two full years’ premiums |
|---|---|---|
| In force | 50% of surrender value | 75% of surrender value |
| Paid up | 40% of surrender value | 65% of surrender value |
After the Payment Term, the maximum loan is 65% of surrender value. LIC also restricts the loan so that its effective yearly interest does not exceed 50% of the eligible Regular Income Benefit. Outstanding loan and interest are recovered from policy payments or claim proceeds under the policy conditions.
The loan interest rate is not fixed for the full life of the product. LIC sets the applicable rate for loans sanctioned during each notified period. A current LIC loan quotation is therefore required before borrowing.
LIC Bima Platinum Plan 770 Eligibility
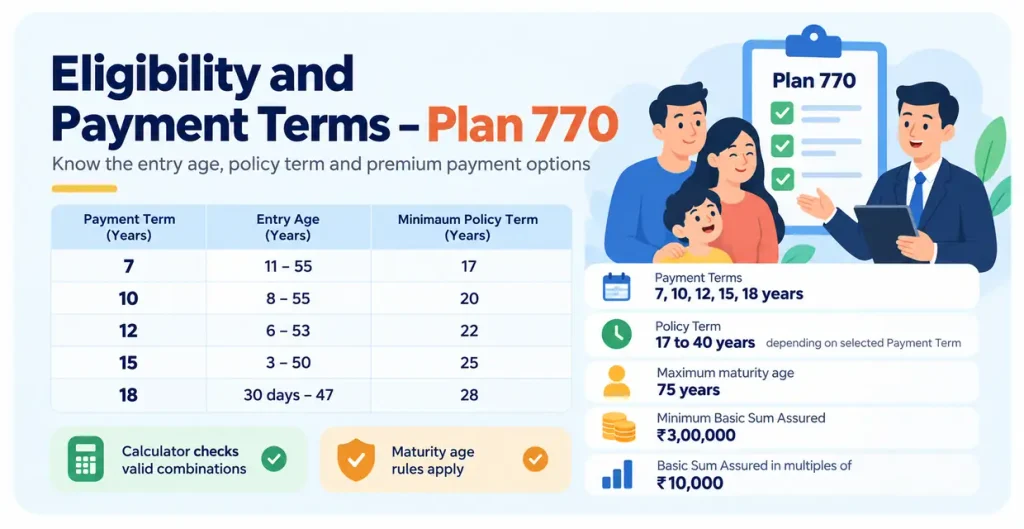
The calculator checks the following Plan 770 conditions before showing a result:
- Payment Term must be 7, 10, 12, 15, or 18 years.
- The entry-age range must match the selected Payment Term.
- The Policy Term must meet the minimum for the selected Payment Term.
- Maturity age must be at least 28 years and not exceed the applicable maximum maturity age.
- Basic Sum Assured must be at least ₹3,00,000.
- Basic Sum Assured must be in multiples of ₹10,000.
- Death-year input must fall within the Policy Term.
- Paid-up calculation must use fewer paid years than the original Payment Term.
The standard entry-age and minimum-term limits are:
| Payment Term | Entry age | Minimum Policy Term | Maximum Policy Term |
|---|---|---|---|
| 7 years | 11 to 55 years | 17 years | 40 years |
| 10 years | 8 to 55 years | 20 years | 40 years |
| 12 years | 6 to 53 years | 22 years | 40 years |
| 15 years | 3 to 50 years | 25 years | 40 years |
| 18 years | 30 days to 47 years | 28 years | 40 years |
The maximum Policy Term is also restricted by the maximum maturity age of 75. Policies sold through POSP-LI or CPSC-SPV follow tighter limits: maximum maturity age 65 and maximum Policy Term 20 years.
Deferring Income and Taking Maturity in Instalments
Plan 770 permits an in-force or paid-up policyholder to defer future Regular Income and Booster Income up to the maturity date, subject to the policy conditions. LIC applies the accumulation rate fixed for each deferred payment. The rate is linked to the five-year government-security yield and is not a permanent fixed rate. The calculator therefore shows scheduled income on its normal due dates and does not add an assumed deferral return.
The maturity benefit is also payable in instalments over 5, 10 or 15 years when the settlement option is selected instead of a lump sum. This changes the payment method; it does not add a benefit. LIC calculates the instalments using the applicable rate and minimum-instalment rules at that time.
Optional Riders Available with Plan 770
Plan 770 offers five optional riders for an additional premium: LIC’s Accidental Death and Disability Benefit Rider, Accident Benefit Rider, New Term Assurance Rider, Premium Waiver Benefit Rider and Critical Illness Health Rider. Each rider has separate age, term, cover and claim rules.
Only one of the two accident riders is selectable. The New Term Assurance Rider and Critical Illness Health Rider are selected at policy commencement. The Premium Waiver Benefit Rider applies to an eligible policy taken on a minor’s life and covers the proposer under its own conditions. Riders are unavailable for policies sold through POSP-LI or CPSC-SPV.
Grace Period, Paid-Up Status and Revival
The grace period is 30 days for yearly, half-yearly, and Quarterly premiums and 15 days for Monthly premiums. Risk cover continues during the grace period under the policy conditions. If the premium remains unpaid after the grace period, the policy becomes lapsed or paid-up according to the number of full years paid and the policy terms.
If less than one full year’s premium has been paid, the base-policy benefits stop after the grace period. After at least one full year’s premium has been paid, the policy continues with reduced paid-up benefits.
A discontinued policy is eligible for revival within five consecutive complete years from the first unpaid premium and before maturity. Revival requires payment of unpaid premiums with applicable interest and LIC’s approval of continued insurability. LIC issues a revival receipt only after accepting the revival.
LIC Bima Platinum Tax Benefits
Tax charged on the base premium, rider premium or underwriting extra premium is collected separately. It is not counted as premium for calculating Regular Income, Booster Income, Guaranteed Additions, maturity or death benefit.
Income-tax treatment is not a fixed benefit promised by Plan 770. A deduction for premiums and an exemption for Regular Income, Booster Income, death proceeds or maturity proceeds depend on the tax law applying to the financial year, the policy issue date, premium-to-cover conditions, total premiums across relevant policies and the taxpayer’s chosen tax regime. LIC’s brochure instructs policyholders to obtain individual tax advice rather than treating every payment as automatically tax-free.
Free-Look Period
The policyholder has 30 days from receipt of the electronic or physical policy document to return it. The request must state the reason for cancellation. LIC cancels the policy and refunds the premium after deducting the permitted proportionate risk premium, medical-examination expenses and stamp duty charges.
Advantages and Limitations of Plan 770
The main strength of Plan 770 is its defined payment structure. Regular Income equals 10% of Basic Sum Assured, Booster Income equals 70%, the basic maturity amount equals the Basic Sum Assured, and Guaranteed Additions follow the policy formula. Premiums stop after the selected 7, 10, 12, 15 or 18-year Payment Term, while the policy continues for the longer Policy Term. Loan, income-deferral and instalment-payment facilities add flexibility.
The plan also requires a long financial commitment. Early surrender does not guarantee recovery of the premiums paid. Fixed future income loses purchasing power when prices rise. The policy has no market-linked growth and no profit-linked LIC bonus. Its death benefit must be compared with the family’s actual life-cover requirement because Plan 770 does not automatically provide adequate family protection.
Other Related Calculators:
- LIC Jeevan Shree Plan 162
- LIC New Jeevan Shree Plan 151
- LIC Jeevan Mitra Plan 88
- LIC Jeevan Rakshak Plan 827
Frequently Asked Questions
Does the calculator work without a known premium?
Yes. Select Check Plan Benefits — Not a Policyholder. Enter age, Payment Term, Policy Term and Basic Sum Assured. The calculator shows Regular Income, Booster Income and the basic maturity amount. It does not show Guaranteed Additions in rupees without the yearly base premium.
Is complete policy benefit the same as maturity amount?
No. Complete policy benefits include Regular Income and Booster Income received before maturity plus the amount payable at maturity. The maturity amount is paid at the end of the Policy Term.
Why is the yearly base premium required for Guaranteed Additions?
LIC calculates each year’s Guaranteed Addition from the cumulative annualized premiums paid up to that year and the applicable rate per ₹1,000. The calculator therefore requires the yearly base premium for a complete policy calculation.
Does the calculator show monthly and half-yearly premiums?
Yes. After entering the yearly base premium, the calculator shows Yearly, Half-Yearly, Quarterly and Monthly instalments using LIC’s published conversion factors. Tax and rider charges are shown separately in the policy quotation and are not included in these base-premium figures.
Does the calculator calculate death and paid-up benefits?
Yes. These options are available under Complete Calculation — Existing Policyholder. The calculator needs the policy year of death or the full premium years paid, depending on the selected calculation.
Conclusion
The LIC Bima Platinum Plan 770 Calculator separates the plan into the figures that matter: Regular Income, Booster Income, Guaranteed Additions, maturity and the complete scheduled benefits. The first mode explains the benefit structure without a premium. The existing-policyholder mode uses the yearly base premium for the cumulative Guaranteed Addition calculation, payment-mode amounts, death benefit and paid-up benefit.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.