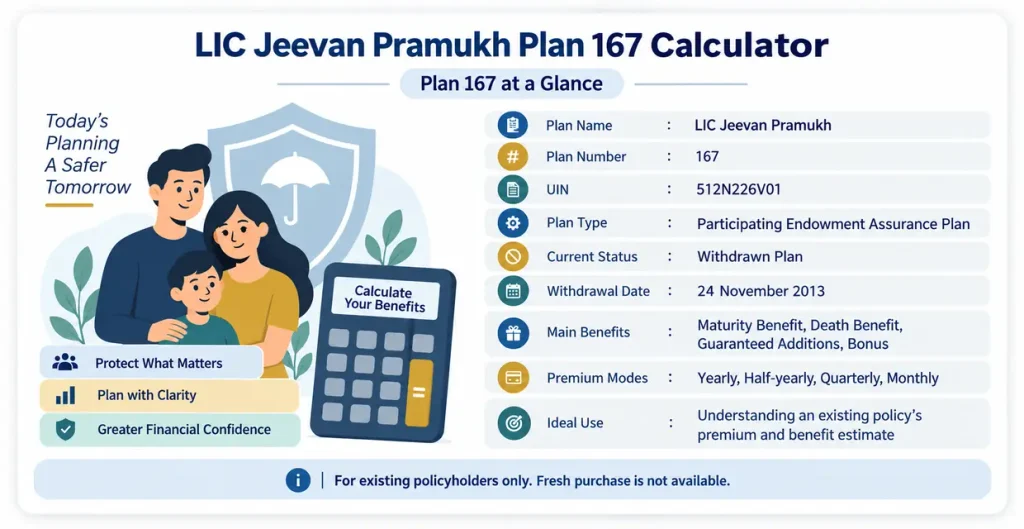
LIC Jeevan Pramukh Plan 167 is a traditional participating endowment policy designed for policyholders who want life insurance protection along with a maturity benefit. It is an old LIC plan and is relevant today mainly for people who already hold this policy and want to understand their premium, Guaranteed Additions, bonus, maturity amount, death benefit, or surrender value.
The official name is LIC Jeevan Pramukh Plan No. 167, with UIN 512N226V01. LIC currently lists it under withdrawn plans, with a withdrawal date of 24 November 2013. Therefore, it cannot be purchased as a new policy today, but existing policyholders can still track policy status, pay eligible premiums, claim maturity, or check benefits through LIC or using LIC Jeevan Pramukh Plan 167 Calculator.
| Particular | Details |
|---|---|
| Plan Name | LIC Jeevan Pramukh |
| Plan Number | 167 |
| UIN | 512N226V01 |
| Plan Type | Participating Endowment Assurance Plan |
| Current Status | Withdrawn plan |
| Withdrawal Date | 24 November 2013 |
| Main Benefits | Maturity benefit, death benefit, Guaranteed Additions, bonus |
| Premium Modes | Yearly, half-yearly, quarterly, monthly |
| Bonus Type | Simple Reversionary Bonus |
| Guaranteed Additions | ₹50 per ₹1,000 Sum Assured for first five completed years |
| Ideal Use | Understanding an existing policy’s premium and benefit estimate |
What Is LIC Jeevan Pramukh Plan 167?
LIC Jeevan Pramukh Plan 167 is a traditional savings-oriented life insurance policy. The policyholder pays premiums for a limited period, while the policy continues for the selected policy term.
In simple words, the plan combines three important components:
- Life insurance protection during the policy term
- Guaranteed Additions during the first five policy years
- Bonus participation from the sixth policy year onward
The plan does not work like a market-linked ULIP. Its maturity value is mainly built from the Sum Assured, Guaranteed Additions, vested LIC bonus, and Terminal Bonus if LIC declares it.
In the official brochure, we can see premiums could be paid yearly, half-yearly, quarterly, or monthly for the chosen premium-paying term or until earlier death of the life assured.
Is LIC Jeevan Pramukh Plan 167 Still Available?
No. LIC Jeevan Pramukh Plan 167 is a withdrawn policy. LIC’s official product page shows the withdrawal date as 24 November 2013. This means fresh purchase is not possible now.
However, withdrawal does not cancel existing policies. If the policy is active, paid-up, or approaching maturity, the policyholder can still receive benefits according to the policy conditions and LIC records.
How LIC Jeevan Pramukh Plan 167 Works
The policy works straightforwardly.
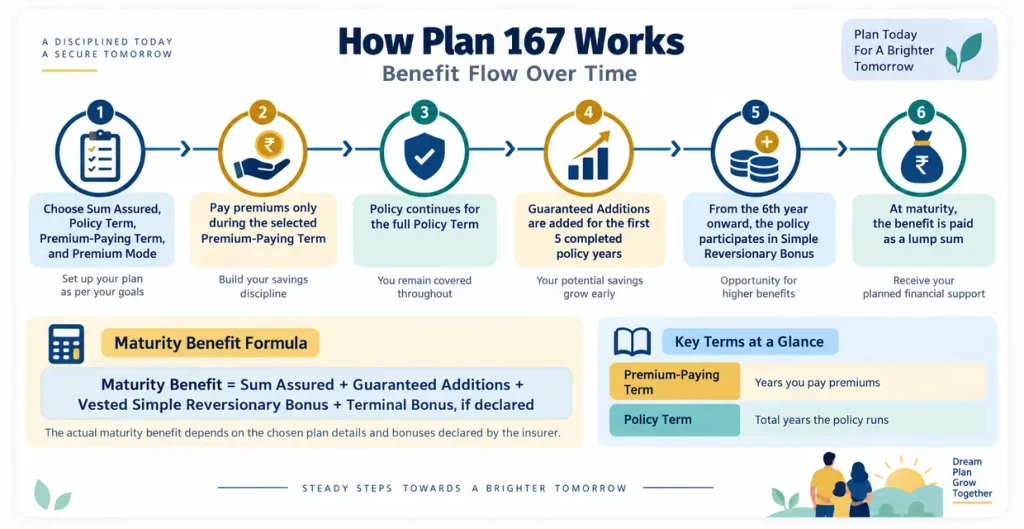
First, the policyholder selects a Sum Assured, policy term, premium-paying term, and premium mode. The policyholder pays premiums only during the chosen premium-paying term. The policy remains active for the full policy term, subject to policy conditions.
During the first five completed policy years, LIC adds Guaranteed Additions at a fixed rate. From the sixth year onward, the policy participates in LIC’s profits through Simple Reversionary Bonus.
At maturity, the benefit generally includes:
Maturity Benefit = Sum Assured + Accrued Guaranteed Additions + Vested Simple Reversionary Bonus + Terminal Bonus, if declared
Plan 167 Key Benefits
Maturity Benefit
If the life assured survives until the end of the policy term, LIC pays the maturity benefit in a lump sum.
The maturity value is not limited to only the original Sum Assured. It can include Guaranteed Additions for the first five years and vested bonus accumulated after that.
Maturity Amount = Sum Assured + Guaranteed Additions + Vested Bonus + Terminal Bonus, if any
Death Benefit
If the life assured dies during the policy term while the policy is valid, LIC pays the death claim to the nominee.
Death Benefit = Sum Assured + Accrued Guaranteed Additions + Vested Simple Reversionary Bonus + Terminal Bonus, if any
LIC states that the death benefit is payable in a lump sum during the policy term.
Guaranteed Additions
Guaranteed Additions are one of the most important features of Jeevan Pramukh Plan 167.
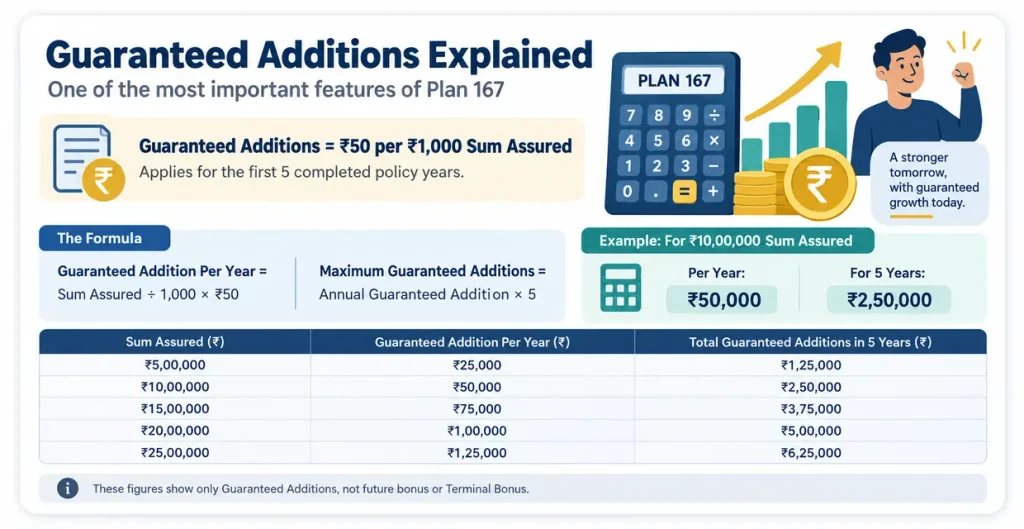
LIC provides Guaranteed Additions at ₹50 per ₹1,000 Sum Assured for each completed policy year during the first five policy years
Its formula is: Guaranteed Addition Per Year = Sum Assured ÷ 1,000 × ₹50
Maximum Guaranteed Additions = Annual Guaranteed Addition × 5
For example, for a ₹10 lakh Sum Assured: ₹10,00,000 ÷ 1,000 × ₹50 = ₹50,000 per year
For five completed years: ₹50,000 × 5 = ₹2,50,000
So, a ₹10 lakh policy can accumulate ₹2.50 lakh as Guaranteed Additions in the first five years, subject to policy conditions.
Guaranteed Additions Table
| Sum Assured | Guaranteed Addition Per Year | Guaranteed Additions for 5 Years |
|---|---|---|
| ₹5,00,000 | ₹25,000 | ₹1,25,000 |
| ₹10,00,000 | ₹50,000 | ₹2,50,000 |
| ₹15,00,000 | ₹75,000 | ₹3,75,000 |
| ₹20,00,000 | ₹1,00,000 | ₹5,00,000 |
| ₹25,00,000 | ₹1,25,000 | ₹6,25,000 |
These figures show only Guaranteed Additions. They do not include future bonus or Terminal Bonus.
How to Use LIC Jeevan Pramukh Plan 167 Calculator
The calculator above is built to make the policy easier to understand.
Step 1: Enter the Sum Assured
Enter the original Sum Assured mentioned in the policy bond.
For example: ₹5,00,000 ₹10,00,000 ₹15,00,000
The Sum Assured is the base amount used for calculating Guaranteed Additions, bonus, death benefit, and maturity benefit.
Step 2: Enter Age at Entry
Enter the age when the policy started, not the current age.
For example, if the policy started when the life assured was 35 years old, enter:
Age at entry is important because LIC premium rates depend on the age and policy term.
Step 3: Select the Premium-Paying Term
Jeevan Pramukh offered a choice of three premium-paying terms. Select the premium-paying term stated in the policy bond.
The premium-paying term means the number of years for which premiums had to be paid. It is different from the full policy term.
For example: Policy Term: 25 years
Premium-Paying Term: 3 years
In this case, premiums are paid for three years, but policy benefits continue until the end of the 25-year term.
Step 4: Enter the Policy Term
Enter the complete policy duration given in policy bond.
The policy term determines when maturity becomes payable. It also affects premium calculation and the possible bonus structure.
Step 5: Choose Premium Payment Mode
Select the payment mode used in the policy:
- Yearly
- Half-yearly
- Quarterly
- Monthly
Step 6: Click Calculate
After entering the details, click the Calculate button.
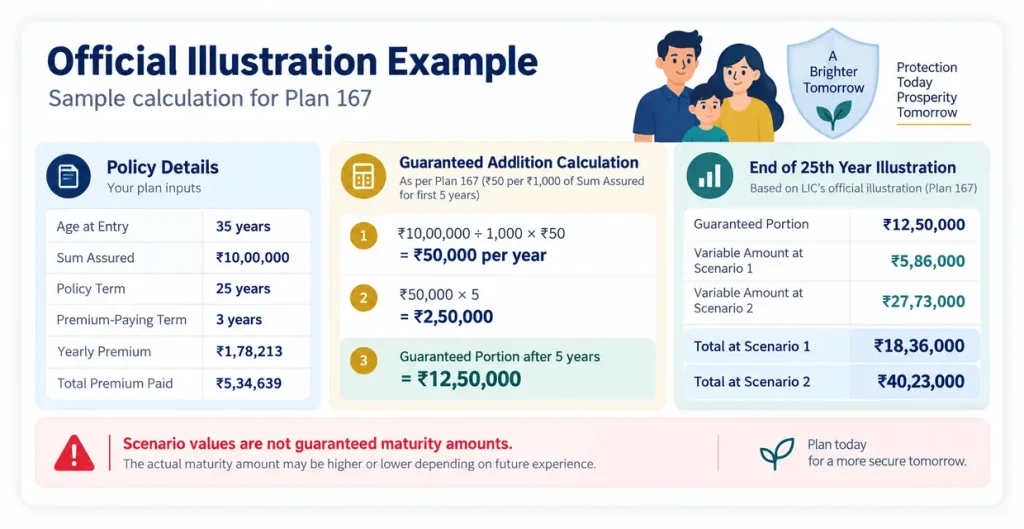
LIC Jeevan Pramukh Plan 167 Calculation Example
LIC uses an official brochure illustration for a policyholder aged 35 years. This is useful because it provides real policy-based numbers rather than assumed values.
| Particular | Official Illustration |
|---|---|
| Age at Entry | 35 years |
| Sum Assured | ₹10,00,000 |
| Policy Term | 25 years |
| Premium-Paying Term | 3 years |
| Yearly Premium | ₹1,78,213 |
| Total Premium Paid | ₹5,34,639 |
The total premium paid is calculated as: ₹1,78,213 × 3 = ₹5,34,639
Now calculate the Guaranteed Additions. ₹10,00,000 ÷ 1,000 × ₹50 = ₹50,000 per year
For the first five completed policy years: ₹50,000 × 5 = ₹2,50,000
Therefore, the guaranteed portion after five years becomes: ₹10,00,000 + ₹2,50,000 = ₹12,50,000
This means that after completion of five years, the guaranteed component of this example becomes ₹12.50 lakh before adding future declared bonus or Terminal Bonus.
The official brochure’s shows that at the end of the 25-year term, the guaranteed amount was ₹12.50 lakh. The illustration also showed variable benefit scenarios based on historical assumed return rates of 6% and 10%.
| End of 25th Year | Amount |
|---|---|
| Guaranteed Portion | ₹12,50,000 |
| Variable Amount at Scenario 1 | ₹5,86,000 |
| Variable Amount at Scenario 2 | ₹27,73,000 |
| Total at Scenario 1 | ₹18,36,000 |
| Total at Scenario 2 | ₹40,23,000 |
These scenario figures should not be treated as guaranteed maturity amounts.
LIC Jeevan Pramukh Bonus Calculation
Guaranteed Additions are fixed for the first five completed policy years. Bonus is different.
From the sixth policy year onward, Jeevan Pramukh participates in LIC’s life insurance business profits. LIC may declare a Simple Reversionary Bonus every year, usually expressed per ₹1,000 Sum Assured. Once a bonus is declared and added to the policy, it becomes vested. A vested bonus is generally added to the final policy benefit.
Annual Bonus = Sum Assured ÷ 1,000 × Declared Bonus Rate
For example, if LIC declares a bonus of ₹50 per ₹1,000 Sum Assured for a ₹10 lakh policy:
₹10,00,000 ÷ 1,000 × ₹50 = ₹50,000
That ₹50,000 becomes vested if it is officially declared and credited to the policy.
However, future bonus is not fixed. LIC officially states that future bonus depends on future profits.
Why Bonus Is Not Included in the Calculator Guaranteed Maturity Amount
Guaranteed Maturity Value = Sum Assured + Guaranteed Additions
It does not automatically add future Simple Reversionary Bonus or Terminal Bonus because these are not fixed in advance.
For an exact maturity estimate, we need these details from LIC:
- Policy commencement date
- Sum Assured
- Policy term
- Premium-paying term
- Number of premiums paid
- Policy status
- Vested bonus
- Final Additional Bonus or Terminal Bonus, if declared
Terminal Bonus and Final Additional Bonus
LIC brochure says that Terminal Bonus may be paid at death or maturity, if applicable. It is not automatic for every policy.
An LIC valuation report for the period ended 31 March 2021 showed a Final Additional Bonus rate of ₹125 per ₹1,000 Sum Assured for Jeevan Pramukh Plan 167 policies meeting the qualifying condition of 15 years or more. This was a valuation-specific declaration and should not be treated as a permanent or universal rate for every claim.
For a ₹10 lakh Sum Assured, a historical rate of ₹125 per ₹1,000 would equal:
₹10,00,000 ÷ 1,000 × ₹125 = ₹1,25,000
But this amount should only be included after confirmation from LIC. The eligibility, policy status, duration, and valuation applicable to the claim can affect the final amount.
LIC Jeevan Pramukh Plan 167 Surrender Value
Surrender means closing the policy before maturity and taking the available cash value.
LIC states that Guaranteed Surrender Value becomes available after more than one year’s premium has been paid.
Its official formula is:
Guaranteed Surrender Value = 30% × (Total Premiums Paid − First-Year Premium − Extra Premium)
Suppose the yearly premium is ₹1,78,213 and three yearly premiums have been paid.
Total Premium Paid = ₹1,78,213 × 3 = ₹5,34,639
Now remove the first-year premium: ₹5,34,639 − ₹1,78,213 = ₹3,56,426
Calculate 30%:
₹3,56,426 × 30% = ₹1,06,927.80
So, the approximate Guaranteed Surrender Value would be: ₹1,06,928
This is just an example. LIC also mentions Special Surrender Value, which may become available after at least three years from the policy commencement date. The actual surrender amount can be lower than the total premiums paid, especially in the early years.
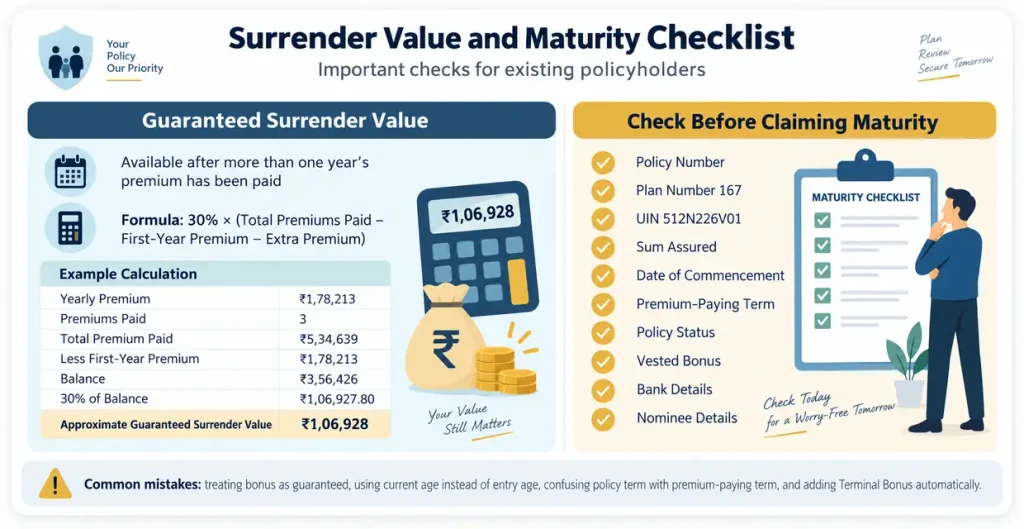
Important Things to Check Before Claiming Maturity
Before approaching LIC for maturity, we need to verify these following details:
| Checkpoint | Why It Matters |
|---|---|
| Policy Number | Required for policy identification |
| Plan Number | Must show Plan 167 |
| UIN | Should match 512N226V01 |
| Sum Assured | Base for all benefits |
| Date of Commencement | Helps determine maturity date |
| Premium-Paying Term | Shows required premium duration |
| Policy Status | In-force, paid-up, lapsed, or surrendered |
| Vested Bonus | Needed for exact maturity estimate |
| Bank Details | Required for claim payment |
| Nominee Details | Important for death claim |
The original policy bond is the most important document. It contains the exact contractual terms, premium amount, policy term, commencement date, and Sum Assured.
Common Mistakes While Calculating LIC Jeevan Pramukh Maturity
Treating Bonus as Guaranteed
Guaranteed Additions are fixed under the policy terms. Future bonus is not guaranteed before LIC declares it.
- Using Current Age Instead of Entry Age
- Confusing Policy Term With Premium-Paying Term
- Adding Terminal Bonus Automatically
- Ignoring Policy Status
- Expecting a Money-Back Benefit
Also Check:
- LIC New Jeevan Anand
- LIC Jeevan Lakshya Plan 733
- LIC Nav Jeevan Shree Plan 912
- LIC New Jeevan Sathi – Single Premium
- LIC New Jeevan Sathi – Limited Premium
FAQs
Is LIC Jeevan Pramukh Plan 167 still available for purchase?
No. LIC lists Plan 167 as a withdrawn plan, with withdrawal dated 24 November 2013.
What is the Guaranteed Addition in Jeevan Pramukh Plan 167?
LIC provides Guaranteed Additions at ₹50 per ₹1,000 Sum Assured for every completed policy year during the first five years.
How is the maturity value calculated?
The maturity value is generally:
Sum Assured + Guaranteed Additions + Vested Bonus + Terminal Bonus, if applicable
Does Jeevan Pramukh Plan 167 provide bonus?
Yes. The policy participates in LIC’s profits from the sixth policy year onward through Simple Reversionary Bonus.
Is bonus guaranteed in this LIC plan?
Future bonus is not guaranteed. Once LIC declares and vests a bonus, that vested amount becomes part of the policy benefit.
Can the policy be surrendered?
Yes. The brochure states that Guaranteed Surrender Value is available after more than one year’s premium has been paid, subject to the stated formula and policy conditions.
Does the calculator include Terminal Bonus?
No. Terminal Bonus is not added automatically because it depends on LIC’s declaration and policy eligibility.
Conclusion
LIC Jeevan Pramukh Plan 167 is an old participating endowment policy that remains important for existing policyholders. Its basic structure is simple: pay premiums for a limited period, receive life cover during the policy term, earn Guaranteed Additions for the first five years, and become eligible for bonus participation from the sixth year onward.
The LIC Jeevan Pramukh Plan 167 Calculator helps estimate premiums, Guaranteed Additions, total premium paid, and the base maturity amount. For final maturity, surrender, death claim, vested bonus, or Terminal Bonus confirmation, rely on the original policy bond and LIC’s official policy records.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.