LIC Jeevan Sugam Plan 813 is a non-linked, single-premium life insurance plan. It provided life cover for ten years and paid a selected Maturity Sum Assured with Loyalty Addition, if declared, at the end of the term.
The plan carried UIN 512N273V01 and was withdrawn on 11 April 2013. It was sold only for a short period and had a fixed ten-year term. Therefore, policies issued under Plan 813 should already have reached maturity by 2023.
The LIC Jeevan Sugam Plan 813 Maturity Calculator is mainly useful for checking an old maturity calculation, understanding a completed death claim, or reviewing an unpaid or unclaimed policy amount. It also helps to understand the original premium, Basic Sum Assured, maturity incentive, and Loyalty Addition. Final values must be checked from the policy schedule and LIC records.
What is Jeevan Sugam Maturity Calculator?
This Jeevan Sugam maturity calculator uses the main benefit rules of Plan 813. The maturity value is based on the selected Maturity Sum Assured, any applicable high-value incentive, and the Loyalty Addition declared for the relevant maturity year.
Death cover is calculated differently. The Basic Sum Assured equals ten times the net single premium paid. Service tax and extra premium charged for an individual policy are not included in this calculation.
LIC’s public brochure gives premium rates for only four sample ages. To get the most accurate result, we need to use policy documents.
Quick Overview of Plan 813
| Particular | Plan details |
|---|---|
| Plan name | LIC’s Jeevan Sugam |
| Plan number | 813 |
| UIN | 512N273V01 |
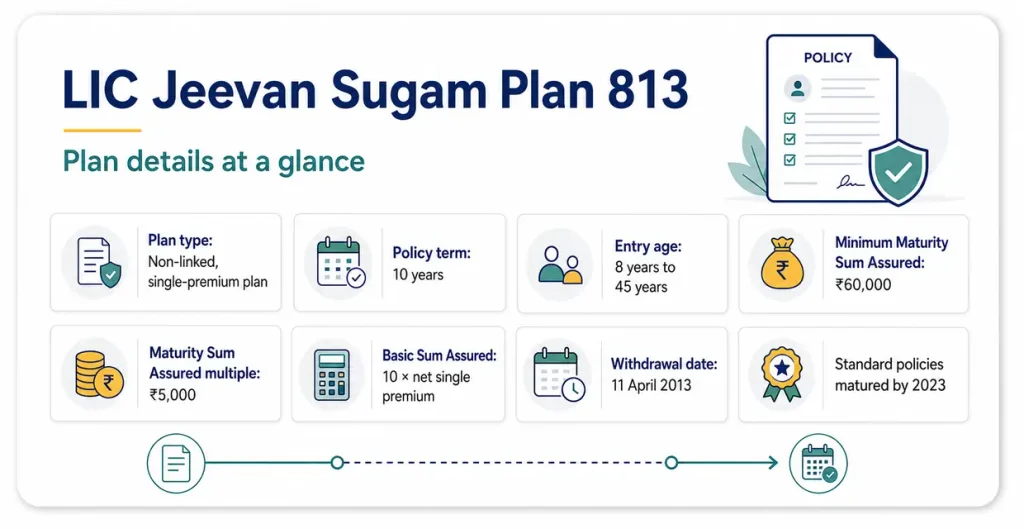
| Plan type | Non-linked, single-premium plan |
| Withdrawal date | 11 April 2013 |
| Policy term | 10 years |
| Entry age | 8 years completed to 45 years nearest birthday |
| Minimum Maturity Sum Assured | ₹60,000 |
| Maximum Maturity Sum Assured | No fixed limit |
| Maturity Sum Assured multiple | ₹5,000 |
| Basic Sum Assured | Ten times the net single premium |
| Maturity benefit | Applicable Maturity Sum Assured plus Loyalty Addition, if any |
| Current position | Standard policies should already have matured |
What is LIC Jeevan Sugam Plan 813?
Jeevan Sugam is a savings and protection plan requiring only one premium payment. The policyholder selected a Maturity Sum Assured when purchasing the policy. LIC calculated the single premium according to the entry age and selected amount.
The policy provided death cover throughout its ten-year term. During the first five policy years, the Basic Sum Assured was payable on death. After completion of five policy years, Loyalty Addition could also become payable if LIC declared it for that claim year.
On survival to the end of ten years, the applicable Maturity Sum Assured and declared Loyalty Addition became payable. Policies with a higher selected Maturity Sum Assured received an automatic increase in the maturity amount.
How to Use Jeevan Sugam Plan 813 Calculator?
An LIC Plan 813 maturity calculator requires the entry age and selected Maturity Sum Assured shown in the policy bond. The policy term should remain fixed at ten years.
For the most accurate calculation, enter the net single premium from the policy schedule. This means the premium excluding service tax and any extra premium charged by LIC. If the exact premium is unavailable and the entry age is 10, 20, 30 or 40, the official sample rate may be used for an estimate.
Select the type of calculation required: maturity, historical death benefit or historical surrender value. Loyalty Addition should be entered only when the rate or total amount for the correct event and year is available from LIC records.
Premium and Basic Sum Assured Calculation
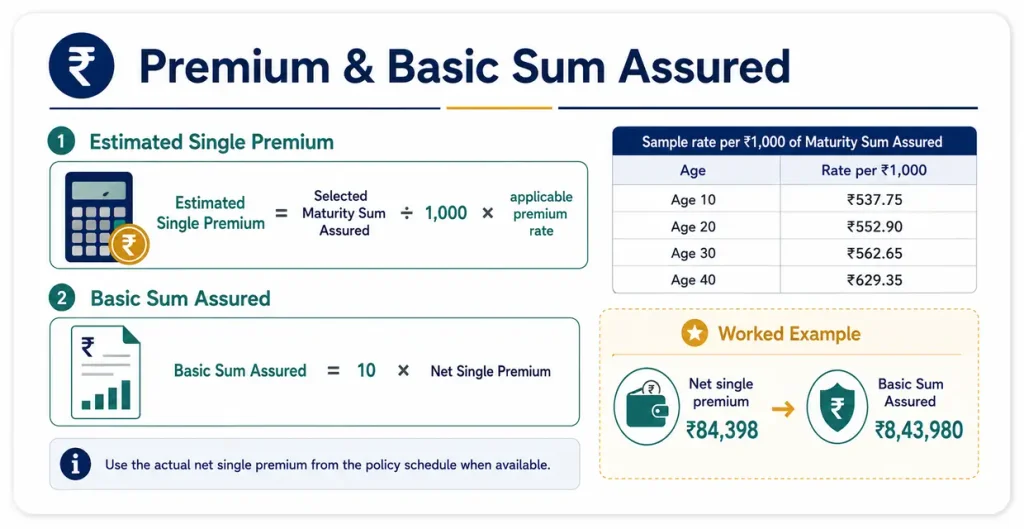
LIC quoted the sample single-premium rates per ₹1,000 of selected Maturity Sum Assured.
Estimated Single Premium = Selected Maturity Sum Assured ÷ 1,000× Applicable premium rate
In the official brochure, LIC gave these sample rates, excluding service tax:
| Age at entry | Sample rate per ₹1,000 MSA |
|---|---|
| 10 years | ₹537.75 |
| 20 years | ₹552.90 |
| 30 years | ₹562.65 |
| 40 years | ₹629.35 |
These rates should be used only for the exact sample ages. Other ages require the official rate table or actual policy premium.
The Basic Sum Assured is calculated from the premium actually recorded in the policy:
Basic Sum Assured = 10 × Net Single Premium
Service tax and extra premium are excluded. If the policy schedule shows a net single premium of ₹84,398:
Basic Sum Assured = ₹84,398 × 10 = ₹8,43,980
Using the recorded premium avoids differences caused by rounding an estimated rate-based premium.
Maturity Sum Assured Incentive
LIC automatically increased the maturity amount for higher selected Maturity Sum Assured levels.
| Selected Maturity Sum Assured | Increase |
|---|---|
| Below ₹1,50,000 | Nil |
| ₹1,50,000 to ₹3,99,999 | 3.50% |
| ₹4,00,000 and above | 4.50% |
For a selected Maturity Sum Assured of ₹1,50,000:
Incentive = ₹1,50,000 × 3.5= ₹5,250
Increased Maturity Sum Assured =₹1,50,000 + ₹5,250 = ₹1,55,250
This incentive increases the maturity amount only. It does not increase the single premium or Basic Sum Assured.
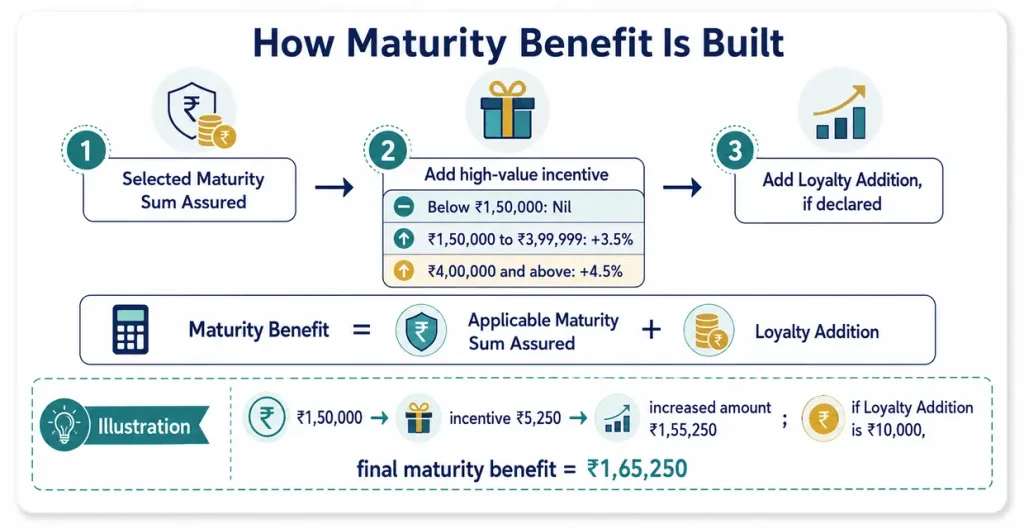
Maturity Benefit
The basic formula is:
Maturity Benefit =Applicable Maturity Sum Assured+ Loyalty Addition, if declared
Where the incentive applies, the increased Maturity Sum Assured is used as the maturity amount. If the applicable amount is ₹1,55,250 and LIC confirms a Loyalty Addition of ₹10,000, the maturity benefit would be:
₹1,55,250 + ₹10,000 = ₹1,65,250
The ₹10,000 used here is only an example. The actual Loyalty Addition must be taken from the maturity-year record.
Death Benefit in This Policy
| Timing of death | Benefit payable |
|---|---|
| During the first five policy years | Basic Sum Assured |
| After completion of five policy years | Basic Sum Assured plus Loyalty Addition, if declared |
For a net single premium of ₹84,398, the Basic Sum Assured would be ₹8,43,980. This amount would be the normal death benefit during the first five policy years.
For death after five years, the Loyalty Addition rate had to match the policy year in which death occurred. A maturity-year rate should not be applied automatically to an earlier death claim.
Any policy loan, unpaid interest, or another amount due to LIC can reduce the final claim payment.
How Loyalty Addition Works
Loyalty Addition was not guaranteed. LIC declared it for policies issued under this plan.
It could become payable in three situations:
- Death after completion of five policy years;
- Surrender during the last policy year; or
- Maturity after ten years.
Declared rates were generally expressed per ₹1,000 of Maturity Sum Assured:
Loyalty Addition = Applicable Maturity Sum Assured ÷ 1,000 × Declared rate for the event and year
The correct rate depends on the event and timing. Death in policy year six, surrender in the last year, and maturity in year ten can have different rates.
LIC’s original brochure showed a projected rate of ₹120 per ₹1,000 under its historical 10% investment-return illustration. The same illustration showed no Loyalty Addition under the 6% scenario. Therefore, ₹120 was not a guaranteed or universally declared rate.
Complete Calculation Example
Consider these details:
| Input | Value |
|---|---|
| Entry age | 30 years |
| Selected Maturity Sum Assured | ₹1,50,000 |
| Official sample premium rate | ₹562.65 per ₹1,000 |
| Net single premium recorded after rounding | ₹84,398 |
The estimated premium before rounding is:
₹1,50,000 ÷ 1,000 × ₹562.65= ₹84,397.50
Using the recorded net premium:
Basic Sum Assured = ₹84,398 × 10 = ₹8,43,980
The maturity incentive is: ₹1,50,000 × 3.5% = ₹5,250
Therefore:
Increased Maturity Sum Assured = ₹1,55,250
The final maturity payment is: ₹1,55,250 + Confirmed Loyalty Addition
The calculator should not insert an assumed Loyalty Addition into the confirmed result unless it is clearly labelled as an illustration.
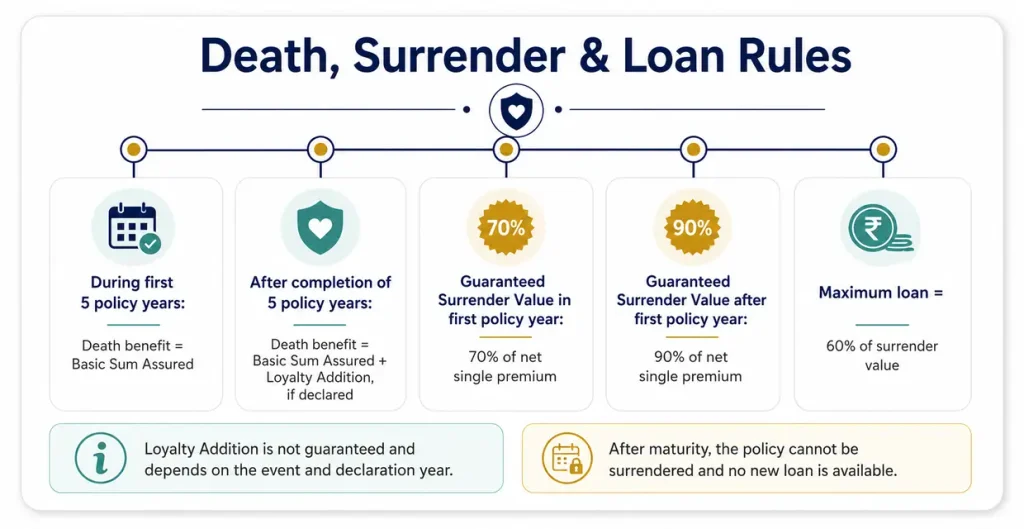
Surrender and Loan Rules
Surrender was allowed at any time while the policy remained active. The Guaranteed Surrender Value was based on the net single premium, excluding service tax and extra premium.
| Surrender period | Guaranteed Surrender Value |
|---|---|
| During the first policy year | 70% of net single premium |
| After the first policy year | 90% of net single premium |
LIC could pay a higher Special Surrender Value based on the discounted Maturity Sum Assured. Loyalty Addition could apply if surrender occurred during the last policy year.
Loan facility is available during the active term in this policy: Maximum loan = 60% of surrender value
These were historical facilities. After maturity, the policy could no longer be surrendered or used for a new loan.
Tax Benefits
The actual service tax paid in 2013 may be taken from the original premium receipt when calculating the total amount paid. A current GST or tax rate should not be applied to the old policy.
Total amount paid = Net Single Premium + Actual service tax paid + Extra premium, if any
The single premium may have qualified for a deduction under Section 80C, subject to the rules and limits applicable when it was paid. Tax treatment of maturity, death, and surrender payments depends on the policy details and applicable law. No amount should be described as tax-free without checking the individual policy.
Also Read:
- LIC Jeevan Madhur Plan 182
- LIC Jeevan Tarang Plan 178
- LIC Jeevan Anurag Plan 168
- LIC Jeevan Saral Plan 165
Important Points to Remember
- Standard Plan 813 policies should already have matured.
- The actual net single premium should be taken from the policy schedule.
- The high-value incentive changes the maturity amount, not the death cover.
- Loyalty Addition depends on the event, policy year and LIC declaration.
- Surrender and loan were available only before maturity.
Frequently Asked Questions
Is LIC Jeevan Sugam Plan 813 still active?
No. LIC withdrew the plan on 11 April 2013. Because the term was fixed at ten years, standard policies should already have reached maturity.
How is the maturity benefit calculated?
The maturity benefit equals the applicable Maturity Sum Assured, including any high-value incentive, plus Loyalty Addition declared for the maturity year.
How is the death benefit calculated?
During the first five years, the Basic Sum Assured was payable. After five years, the Basic Sum Assured plus Loyalty Addition, if declared for that death year, was payable.
Is Loyalty Addition guaranteed?
No. It depended on LIC’s declaration. A rate shown in an old benefit illustration was not necessarily the actual rate payable on a policy.
Can a Plan 813 policy still be surrendered or used for a loan?
Surrender and loan were available only during the active ten-year term. They are not available after the policy has matured.
Conclusion
The LIC Jeevan Sugam Plan 813 Maturity Calculator helps explain the premium, Basic Sum Assured, maturity incentive, and Loyalty Addition of an old policy. The most reliable calculation uses the actual net single premium and Maturity Sum Assured recorded in the policy schedule.
Because standard Plan 813 policies should already have matured, the calculator is best used to review an old settlement or understand a pending or unclaimed amount. LIC records remain final for all maturity and claim payments.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.