LIC Money Plus-I Plan 193 Calculator
Optional Policy Details
| Calculation Summary | |
|---|---|
| Selected UIN | — |
| Fund / FMC | — |
| Total Amount Allocated to Fund | — |
| Policy Administration Charges | — |
| Mortality Charges | — |
| Rider Charges | — |
| Fund Management Charges | — |
| Tax on Charges Entered | — |
| Basic Death Benefit Before Maturity | — |
| Accidental Death Benefit (if eligible) | — |
| Critical Illness Rider SA | — |
| Surrender Value at End of Term | — |
Year-wise Projection
| Year-wise Fund Projection | |||||
|---|---|---|---|---|---|
| Year | Premium | Allocation | Other Charges | Fund Value | Death Benefit |
The LIC Money Plus-I Plan 193 Calculator helps estimate how premiums, investment returns, and policy charges affect a Money Plus-I policy. It explains the amount allocated for investment, projected maturity value, and basic death benefit.
Money Plus-I a unit-linked insurance plan, or ULIP. Its maturity amount was not fixed because the policy invested in market-linked funds. LIC withdrew Plan 193 on 1 September 2010.
Table of Contents
What Is LIC Money Plus-I Plan 193?
LIC Money Plus-I combined life cover with investments made through regular premium payments. After an allocation charge, the remaining premium was used to purchase units in a selected fund. Other charges reduced the number of units available during the policy term.
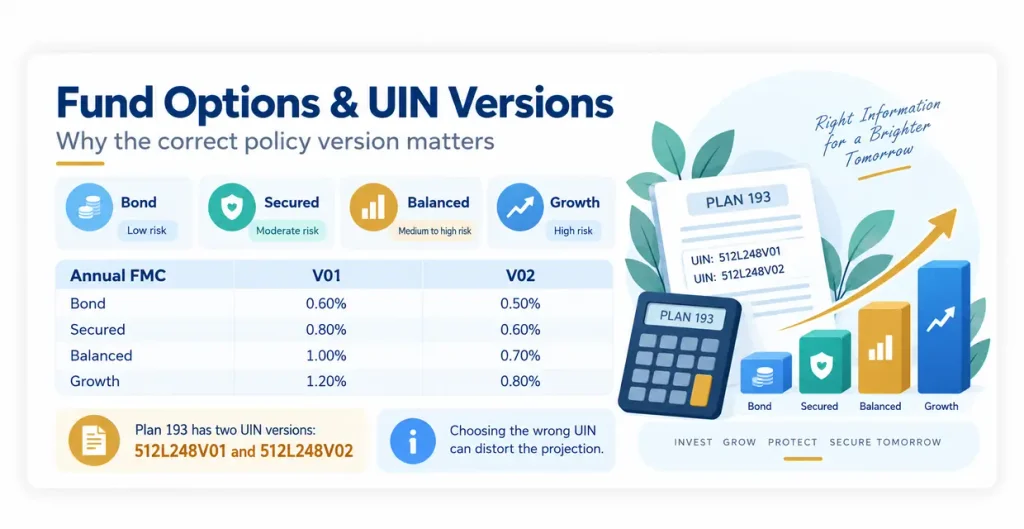
UIN versions in this plan are 512L248V01 and 512L248V02. Their published Fund Management Charges differ, making the UIN on the policy bond important for any calculation.
What Is the LIC Money Plus-I Plan 193 Calculator?
The Money Plus-I calculator is an estimation tool to understand the investment and insurance components of a policy. In its calculation, its use details such as entry age, policy term, premium, payment frequency, basic sum assured, and fund, and provides estimated investment returns.
Its purpose is to show how the fund might develop under the chosen assumptions. A constant-return projection from the original premium does not determine the actual value of an existing policy today.
Current Fund Value and Future Maturity Value
The direct calculation for a current policy value is:
Current Fund Value = Actual Units Held × Applicable NAV
For example, if a statement shows 8,000 units and the applicable NAV is ₹35, the fund value is ₹2,80,000. These are assumed figures for explanation, not a current LIC quotation.
Both units and NAV must relate to the relevant valuation date and correct fund. Fund Management Charge is already reflected in the published NAV and must not be deducted again.
Future maturity is different. The final units and NAV are not known in advance, so a future-value calculation needs assumptions about returns, premium payments, charges, and withdrawals.
Money Plus Plan 193 Calculator Highlights
The main value of a plan-specific calculator is the separation of premiums, charges and projected benefits. The year-wise projection helps explain why total premiums paid and fund value are different amounts.
Selecting a UIN helps ensure accurate published FMC rates are applied. Premium frequency matters because annual and monthly payments are credited to the fund at different times. Optional rider and withdrawal details should only be included where the calculation supports their full impact.
Charges in LIC Money Plus-I Plan 193
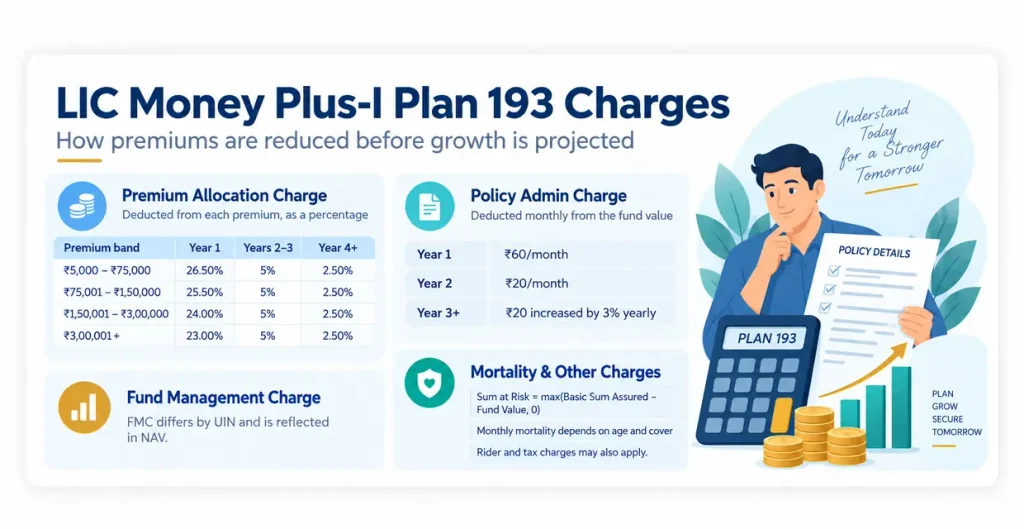
The table below shows the charges as described in the published policy documents.
Premium Allocation Charge
An allocation charge is deducted from each premium before investment. The rate is determined using the annual premium band and policy year.
| Annual premium band | First year | Years 2 and 3 | Year 4 onwards |
|---|---|---|---|
| ₹5,000–₹75,000 | 26.50% | 5.00% | 2.50% |
| ₹75,001–₹1,50,000 | 25.50% | 5.00% | 2.50% |
| ₹1,50,001–₹3,00,000 | 24.00% | 5.00% | 2.50% |
| ₹3,00,001 and above | 23.00% | 5.00% | 2.50% |
Allocation Charge = Premium Instalment × Allocation Rate
Allocated Premium = Premium Instalment − Allocation Charge − Tax on That Charge, if Applicable
The premium band is not selected from the size of a monthly or quarterly instalment alone.
Policy Administration Charge
| Policy year | Monthly charge |
|---|---|
| Year 1 | ₹60 |
| Year 2 | ₹20 |
| Year 3 onwards | ₹20 increased by 3% annually from year 3 |
The third-year monthly amount is ₹20.60. For policy year n from year 3 onwards, the scheduled monthly amount is ₹20 × 1.03^(n − 2). The increase happens once a year; the charge is deducted monthly through cancellation of units.
Fund Management Charge
| Fund | 512L248V01 annual FMC | 512L248V02 annual FMC |
|---|---|---|
| Bond | 0.60% | 0.50% |
| Secured | 0.80% | 0.60% |
| Balanced | 1.00% | 0.70% |
| Growth | 1.20% | 0.80% |
LIC reflects FMC in its daily NAV calculation. A simplified projection may instead model it monthly. That monthly method is an approximation.
Mortality Charge
Mortality charge is the cost of life cover. It depends on the applicable age-based rate and the amount of insurance risk remaining after considering the fund.
Sum at Risk = Maximum of (Basic Sum Assured − Fund Value After Other Charges, 0)
Estimated Monthly Mortality Charge = Sum at Risk ÷ 1,000 × Annual Mortality Rate ÷ 12
The policy uses the age nearer the birthday at the relevant policy anniversary. Individual health and underwriting conditions can also affect the charge. Even when the age-based rate rises, the rupee charge may fall if the fund value increases sufficiently.
Rider and Tax Charges
Optional Accident Benefit and Critical Illness cover have separate charges and eligibility conditions. They should not be treated as automatic benefits of every policy.
Historical service tax could apply to relevant charges. A single assumed tax rate over the whole policy is only a simplification. Setting tax to zero excludes it from the illustration; it does not mean that no tax was historically charged.
Fund Options
The plan offered bond, secured, balanced, and growth funds, with one option selected at a time. Their published risk descriptions ranged from low risk for bonds to high risk for growth, with secured and balanced falling in between.
A projection that assumes the same fund throughout cannot replicate the experience of a policy in which funds are switched. Actual switches alter the units and investment exposures recorded in the policy.
Maturity and Death Benefits
Maturity Benefit
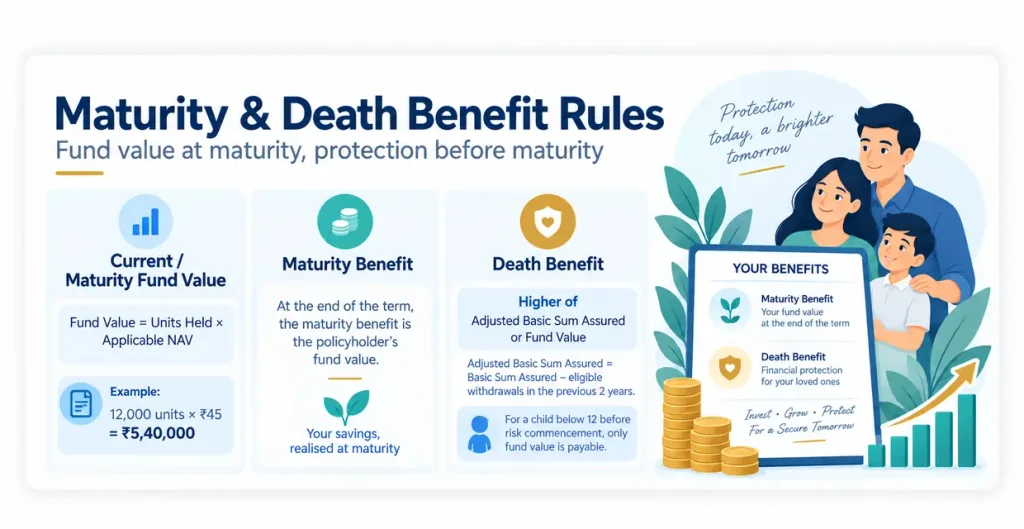
On survival to the end of the term, the maturity benefit is the policyholder’s fund value:
Maturity Benefit = Units Held at Maturity × Applicable Maturity-Date NAV
There is no traditional reversionary bonus or Final Additional Bonus to add to this formula.
Death Benefit
Before maturity, when full life cover is in force:
Adjusted Basic Sum Assured = Basic Sum Assured − Applicable Withdrawals Within the Previous Two Years
Basic Death Benefit = Higher of Adjusted Basic Sum Assured or Fund Value
If a child under 12 years of age dies before the commencement of risk, only the fund value will be payable. The terms of a lapsed policy may also remove normal life cover. Eligible accident rider benefits vary and depend on the rider’s in-force status.
The death benefit should be calculated for a date prior to maturity and should not be automatically compared to the projected fund at the end of the policy term.
Surrender and Partial Withdrawal Rules
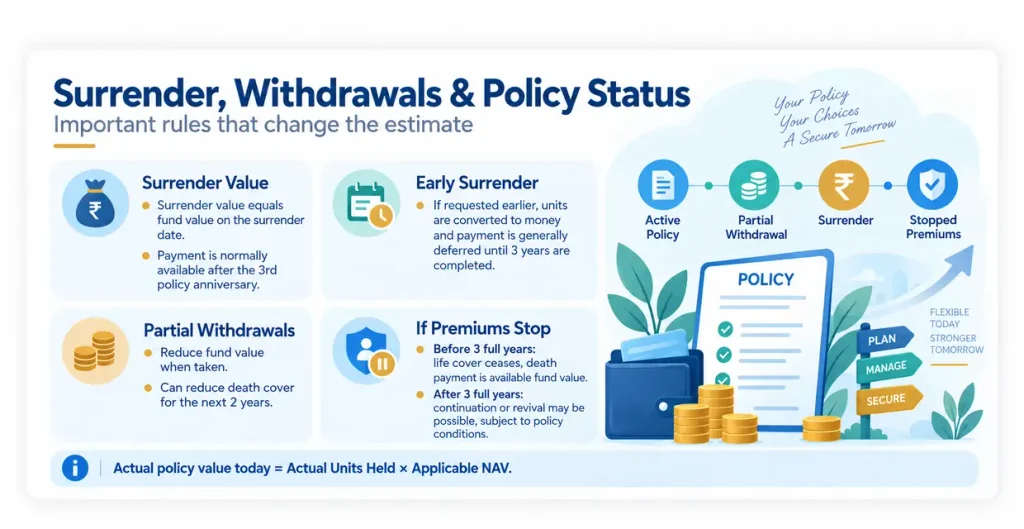
The policy states that the surrender value is the fund value on the applicable surrender date, excluding any separate surrender charges. Payments are typically made after the third policy anniversary. If surrender is requested earlier, the units are converted into cash, further charges are stopped, and payments are typically deferred until the completion of three years, subject to the death-related exceptions in the policy.
Withdrawals depend on the policy’s timing, age, and minimum-balance conditions. Withdrawals reduce the investment fund. This also impacts the sum assured used for the death benefit over the next two years.
What If We Stop Paying Premiums?
If premiums are stopped before the full 3 years, the life and rider cover terminates, and the death benefit is the available fund value. After 3 years, depending on the policy terms and fund balance, cover may continue during a revival period. Continuing cover beyond this period requires exercising the applicable option within the required time and is not automatic.
The estimate should reflect the actual policy status, premiums paid, and any continuation options recorded by LIC—do not assume that all premiums have been paid for the entire term.
How to Use Money Plus-I Plan 193 Calculator
First, select the UIN printed on the policy bond. Enter the recorded entry age, policy term, and Basic Sum Assured. The term and other details should match the policy schedule, not merely the range accepted by an input field.
Enter the annual basic premium and choose the payment frequency. If the calculator asks for an instalment premium instead, enter the actual instalment amount. Do not enter an annual amount into an instalment field or multiply it by the payment frequency twice.
Select the fund and enter an assumed gross annual return before FMC. Include supported rider, tax, and withdrawal details where applicable. Then calculate the projection and read its assumptions alongside the result.
Formulas Used in Plan 193 Calculator
A simplified monthly model converts an assumed gross annual return into a monthly rate:
Monthly Gross Growth Rate = (1 + Gross Annual Return)^(1/12) − 1
Rates must be expressed as decimals: 8% becomes 0.08.
The model adds each allocated premium when due, applies assumed growth, and deducts relevant charges. A monthly FMC approximation is fund value × annual FMC rate ÷ 12. The order and timing of these operations must remain consistent throughout the projection.
Calculation Example for Premium Allocation
In this example, we use a V02 policy with a yearly premium of ₹50,000 paid for all 20 years. Assume no riders or withdrawals, and exclude tax for this allocation example.
| Period | Calculation | Allocation charges |
|---|---|---|
| Year 1 | ₹50,000 × 26.50% | ₹13,250 |
| Years 2–3 | ₹50,000 × 5% × 2 | ₹5,000 |
| Years 4–20 | ₹50,000 × 2.50% × 17 | ₹21,250 |
| Total | ₹13,250 + ₹5,000 + ₹21,250 | ₹39,500 |
Total scheduled premiums are ₹50,000 × 20 = ₹10,00,000.
After allocation charges, the total amount contributed for investment before other charges is:
₹10,00,000 − ₹39,500 = ₹9,60,500
This money enters the fund over 20 years, not at the start. ₹9,60,500 is therefore neither the opening investment nor the maturity benefit. Administration, mortality, FMC, applicable tax and actual returns still affect the outcome.
Calculation Example: Value from Units and NAV
Suppose a policy has 12,000 units on its maturity date and the applicable NAV is ₹45:
Maturity Fund Value = 12,000 × ₹45 = ₹5,40,000
This is a separate assumed example, not the projected outcome of the premium-allocation example above. It shows how known units and NAV determine the fund value without inventing a future return.
Also Check:
Frequently Asked Questions
Is LIC Money Plus-I Plan 193 still available?
No. The plan was withdrawn on 1 September 2010. Existing policies are governed by their original conditions, endorsements and current status.
How is the maturity amount calculated?
It is the policyholder’s fund value at maturity, calculated using the units held and the applicable maturity-date NAV. Before that date, a future amount is only a projection.
Does Money Plus-I guarantee an 8% return?
No. An 8% rate entered in a calculator is an assumption, not a promise from LIC. Actual investment performance can be higher or lower, and charges affect the final value.
Why does the calculator need the UIN version?
V01 and V02 have different published Fund Management Charges. Selecting the wrong version can distort a projection even when all other inputs remain the same.
What happens if premiums have stopped?
Benefits depend on the premiums already paid, the revival or continuation position, and the available fund. Full life cover should not be assumed without checking the LIC policy record.
Conclusion
The LIC Money Plus-I Plan 193 Calculator helps explain the relationship between premiums, policy charges and projected benefits. The correct UIN, premium timing and policy status are essential for a useful estimate.
For an actual value, the relevant units and official NAV are the starting point. Future projections should clearly separate assumptions from confirmed policy figures.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.
1 thought on “LIC Money Plus-I Plan 193 Calculator”