LIC Profit Plus Plan 188 Calculator
Optional Rider & Withdrawal Details ⌄
| Premium & Investment Summary | |
|---|---|
| Total Premium Paid | ₹0 |
| Premium Allocation Charges | ₹0 |
| Net Premium Allocated | ₹0 |
| Selected Fund / FMC | — |
| Estimated Net Annual Growth | — |
Charge Details ⌄
| Estimated Policy Charges | |
|---|---|
| Policy Administration Charges | ₹0 |
| Mortality Charges | ₹0 |
| Accident Benefit Charges | ₹0 |
| Critical Illness Charges | ₹0 |
| Partial Withdrawal | ₹0 |
Year-wise Projection ⌄
| Policy Year | Projected Fund Value |
|---|
LIC Profit Plus Plan 188 was a unit-linked insurance plan from the Life Insurance Corporation of India. Its policy value depended on the number of units held in the selected fund and the applicable net asset value (NAV). Unlike traditional endowment plans, it did not offer a fixed maturity amount or annual bonuses.
The LIC Profit Plus Plan 188 calculator helps you estimate the current fund value, estimated maturity value, death benefit, and surrender value. It also explains how premium allocation, policy administration, mortality, and fund management charges affect your investment.
Profit Plus is a discontinued plan and is no longer available for purchase. LIC withdrew it on September 1, 2010. The calculator is primarily useful for checking existing policies or understanding old policy statements.
Table of Contents
What Does the Calculator Show and Supported UIN?
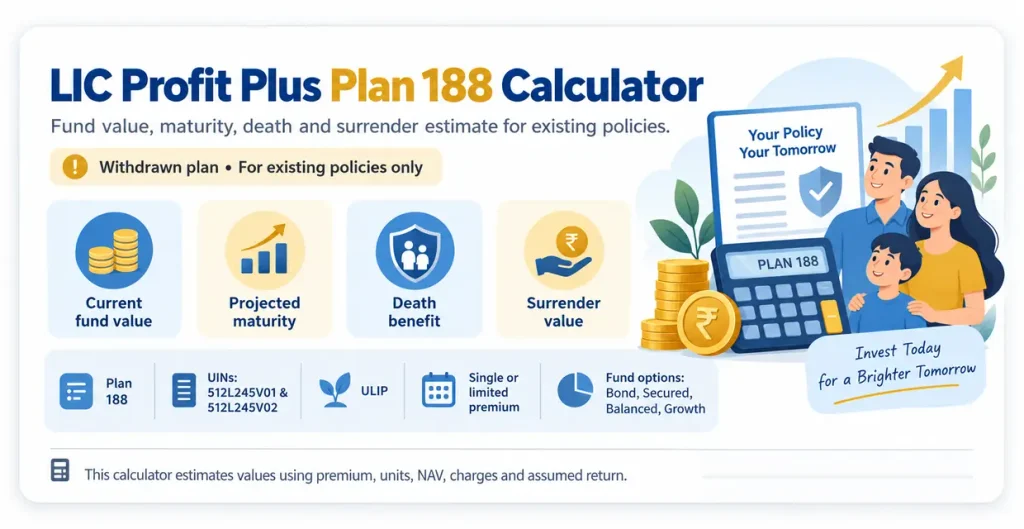
The calculator supports both UIN versions of Plan 188.
- 512L245V01
- 512L245V02
After the correct UIN is selected, the calculator applies the relevant formula and charge structure. It will show the premium invested after allocation charges, estimated policy charges, projected fund value, maturity benefit, death benefit, and surrender value.
For the most accurate result, we need to enter the number of units and NAV from LIC records.
LIC Profit Plus Plan 188 Quick Overview
| Particular | Details |
|---|---|
| Plan name | LIC Profit Plus |
| Plan number | 188 |
| UIN versions | 512L245V01 and 512L245V02 |
| Plan type | Unit-linked insurance plan |
| Premium options | Single premium or limited premium |
| Limited premium-paying term | 3, 4 or 5 years |
| Fund options | Bond, Secured, Balanced and Growth |
| Maturity benefit | Fund value on the maturity date |
| Normal death benefit | Higher of the applicable Basic Sum Assured or fund value |
| Policy loan | Not available |
| Withdrawal date | 1 September 2010 |
What Is LIC Profit Plus Plan 188?
LIC Profit Plus Plan 188 combines life insurance with market-linked investments. After deducting applicable allocation charges, the remaining premium is used to purchase units in a selected fund. The value of those units may increase or decrease with the NAV. Other policy charges were recovered upon cancellation of units. These included policy administration and mortality charges. Rider, switching, service tax, and alteration charges may also apply.
This plan did not offer traditional simple reversionary bonuses, loyalty additions, or final additional bonuses. The maturity amount depended on the policyholder’s fund value.
Eligibility Criteria
Profit Plus is closed to new buyers. The original plan allowed single-premium policies and limited-premium policies, with premium-paying terms of 3, 4, or 5 years. The policy term, entry age, premium limits, and basic sum assured had to meet the rules applicable at the time of policy issuance.
The minimum annual premium band varied between UIN versions. It started at ₹10,000 in the earlier version and ₹15,000 in V02. Exact eligibility should be checked with the policy bond, as age, term, sum assured, and underwriting requirements may vary between policies.
How Does LIC Profit Plus Plan 188 Work?
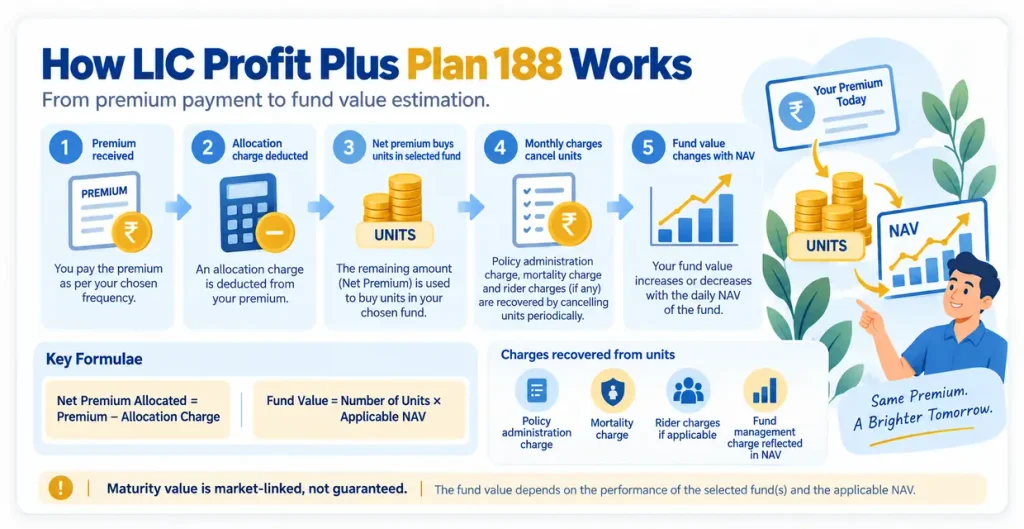
This process begins when LIC receives the premium. First, the applicable premium allocation charge is deducted. The remaining amount is used to purchase units in the selected fund at the applicable NAV. During the policy term, administrative, mortality, and applicable rider charges are recovered by canceling units. The fund management charge is reflected when calculating the NAV. As the NAV changes and units are added or canceled, the fund value also changes.
The current fund value is calculated as:
Fund Value = Number of Units × Applicable NAV
If the policy matures, the Fund Value on the date of maturity will be paid. If death occurs before maturity while full risk cover is in effect, the higher of the applicable Basic Sum Assured or Fund Value will generally be paid. Surrender and partial withdrawals are subject to policy terms.
Benefits of LIC Profit Plus Plan 188
Maturity Benefit
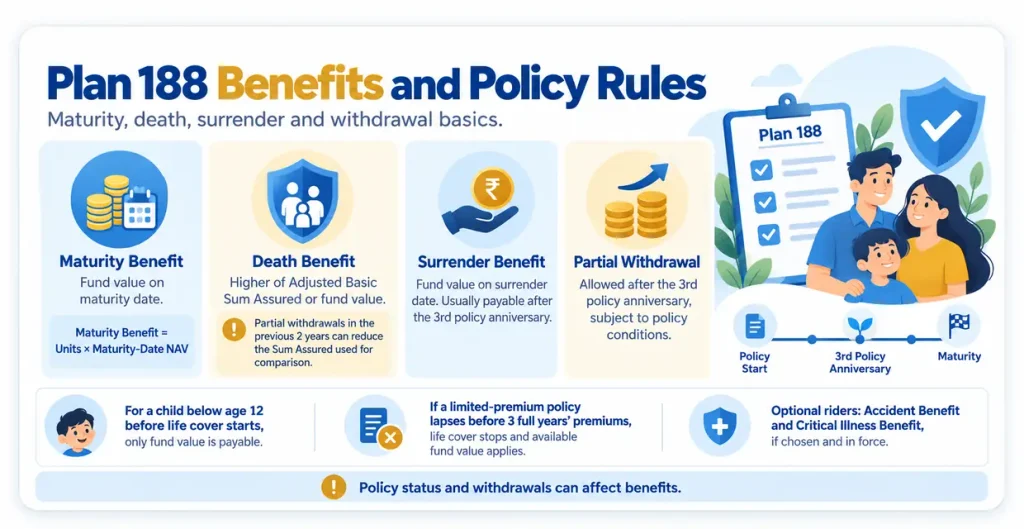
If the life assured survives to the maturity date, LIC pays the policyholder’s fund value:
Maturity Benefit = Units on the Maturity Date × Maturity-Date NAV
The maturity value is market-linked and is not guaranteed in advance.
Death Benefit
When full life cover is in force, the basic death benefit is:
Death Benefit = Higher of Adjusted Basic Sum Assured or Fund Value
If partial withdrawals were made during the two years before death, the Basic Sum Assured is reduced by those withdrawals before making the comparison.
For a child aged below 12 before life cover had started, only the fund value was payable. Policy status also matters. If a limited-premium policy lapsed before three full years’ premiums were paid, life and rider covers stopped, and only the available fund value was payable on death.
Surrender Benefit
The surrender value is the fund value as of the surrender date, and the policy had no extra surrender charges. But the payout is only allowed after the third policy anniversary is completed.
If a surrender request is made within the first three years, the units are converted into cash using the applicable NAV. Further charges are waived, and the amount is usually disbursed after the policy has completed three years.
Partial Withdrawal
Partial withdrawals are permitted after the third policy anniversary, depending on the policy terms. For minors, this is only permitted after the age of 18 years on or after the policy anniversary. Partial withdrawals reduce the death cover sum assured for two years.
Optional Rider Benefits
Accident Benefit and Critical Illness Benefit could be selected where permitted. These benefits were available only if the rider shown in the policy schedule was in effect, and all rider conditions were met. Rider charges were deducted separately from the fund.
Fund Options and Their Risk Profile
Only one fund could be selected at a time. A switch moved the entire fund value to the newly selected fund.
| Fund | Main investment approach | Risk profile |
|---|---|---|
| Bond Fund | Debt and short-term instruments; no equity exposure | Low |
| Secured Fund | Mainly debt with limited equity exposure | Lower to medium |
| Balanced Fund | Mix of debt and equity | Medium |
| Growth Fund | Higher equity exposure for long-term growth | High |
The policy allowed four free switches in a policy year. Further switches were subject to the applicable switching charge. Switching was not allowed while the policy was lapsed.
Charges in LIC Profit Plus Plan 188
Premium Allocation Charge
This charge was deducted from each premium before units were purchased:
Allocation Charge = Premium × Applicable Rate
Amount Invested = Premium − Allocation Charge
For single-premium policies under both versions:
| Single premium | Allocation charge |
|---|---|
| Up to ₹4,00,000 | 5.00% |
| ₹4,00,001 and above | 4.50% |
For limited-premium policies with a 3-year or 4-year premium-paying term:
| Annual premium | First-year charge | Later-year charge |
|---|---|---|
| Up to ₹1,50,000 | 10.50% | 2.50% |
| ₹1,50,001 to ₹3,00,000 | 10.00% | 2.50% |
| ₹3,00,001 to ₹4,50,000 | 9.50% | 2.50% |
| ₹4,50,001 and above | 9.00% | 2.50% |
For policies with a 5-year premium-paying term:
| Annual premium | First-year charge | Later-year charge |
|---|---|---|
| Up to ₹1,50,000 | 24.00% | 4.00% |
| ₹1,50,001 to ₹3,00,000 | 23.50% | 4.00% |
| ₹3,00,001 to ₹4,50,000 | 23.00% | 4.00% |
| ₹4,50,001 and above | 22.50% | 4.00% |
The first premium band began at ₹10,000 under the earlier version and ₹15,000 under V02.
Fund Management Charge
Fund Management Charge was reflected in the NAV. The two UIN versions used different rates:
| Fund | UIN 512L245V01 | UIN 512L245V02 |
|---|---|---|
| Bond Fund | 0.75% yearly | 0.50% yearly |
| Secured Fund | 1.00% yearly | 0.60% yearly |
| Balanced Fund | 1.25% yearly | 0.70% yearly |
| Growth Fund | 1.50% yearly | 0.80% yearly |
When an assumed gross return is used for a future projection, the calculator adjusts the return for FMC. When actual units and LIC’s published NAV are used, FMC must not be deducted again because it is already reflected in the NAV.
Policy Administration Charge
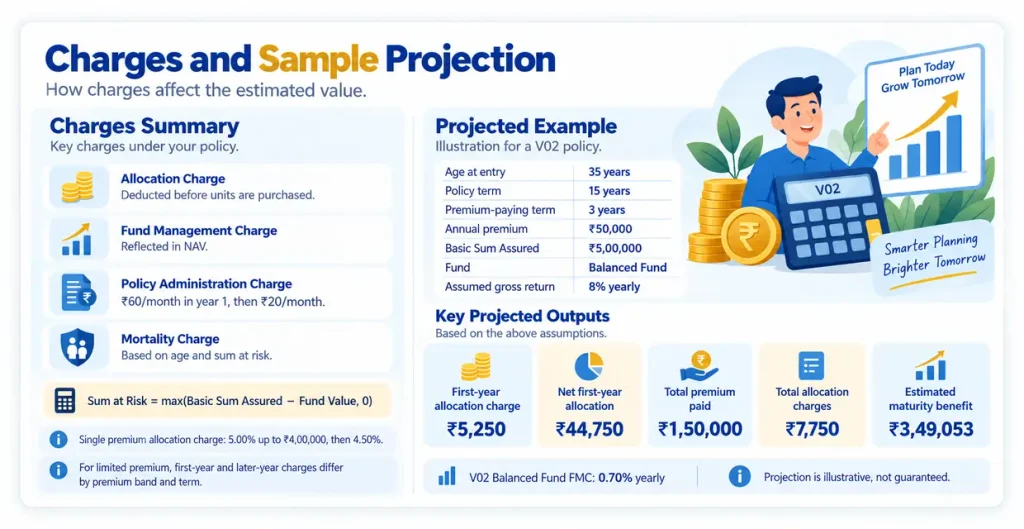
The charge was ₹60 per month during the first policy year and ₹20 per month afterwards. LIC recovered it monthly by cancelling units.
Mortality Charge
Mortality charge paid for the life cover. It depended on the age nearer birthday, health or underwriting conditions and the amount at risk.
Sum at Risk = Maximum of (Basic Sum Assured − Fund Value, 0)
Monthly Mortality Charge = Sum at Risk ÷ 1,000 × Age-wise Annual Rate ÷ 12
The calculation used the fund value after other applicable charges. Therefore, mortality cost could change every month and normally increased as age increased.
Rider and Other Charges
Accident Benefit was charged at the applicable rider rate. Critical Illness Benefit used an age-based rate. Switching, alteration and historical service-tax charges could also reduce the policy value. A projection that excludes these items must clearly say so.
Formulas Used in LIC Profit Plus Plan 188 Calculator
The main formulas are:
Current Fund Value = Number of Units × Applicable NAV
Net Premium Allocated = Premium − Premium Allocation Charge
For a projection based on a gross annual return:
Net Growth Rate = [(1 + Gross Return) × (1 − FMC)] − 1
The calculator applies growth and deducts monthly charges. This is a simplified projection. Actual LIC values depend on exact premium dates, daily NAVs, unit purchases, unit cancellations and policy transactions.
How to Use LIC Profit Plus Plan 188 Calculator
Select the UIN given on the policy bond. Then select single premium or limited premium and enter the policy term, age at entry, premium, Basic Sum Assured, and fund type.
For an actual current-value calculation, enter the number of units and applicable NAV from the latest LIC statement. For a future projection, enter an assumed gross return. This return is not guaranteed.
Enter any partial withdrawal and rider details that apply. Select the required calculation, such as maturity, death or surrender, and press Calculate. Use Reset to clear the fields.
Projected Calculation Example
In this calculation, we use a 512L245V02 policy with these details using the Profit Plus Plan 188 AMturity Calculator:
| Detail | Value |
|---|---|
| Age at entry | 35 years |
| Policy term | 15 years |
| Premium-paying term | 3 years |
| Annual premium | ₹50,000 |
| Basic Sum Assured | ₹5,00,000 |
| Fund | Balanced Fund |
| Assumed gross return | 8% yearly |
| Partial withdrawal | Nil |
| Rider | Nil |
The first-year allocation charge is:
₹50,000 × 10.50% = ₹5,250
The amount allocated in the first year is:
₹50,000 − ₹5,250 = ₹44,750
The allocation charge in each of the next two years is:
₹50,000 × 2.50% = ₹1,250
Total premium paid is ₹1,50,000. Total allocation charges are ₹7,750, leaving ₹1,42,250 for investment before the other policy charges.
For the V02 Balanced Fund, FMC is 0.70% yearly. Using the simplified formula, an 8% gross return becomes approximately 7.244% after FMC.
Under a monthly projection, administration charges total ₹4,080 over 15 years. Estimated mortality charges are about ₹12,763. The projected maturity fund value is approximately:
₹3,49,053
Therefore:
Estimated Maturity Benefit = ₹3,49,053
This result is not guaranteed. It excludes historical service tax, rider charges, switching charges, withdrawals and individual underwriting adjustments.
Death and surrender must be calculated at dates before maturity. Under the same assumptions, the estimated fund value after policy year 10 is about ₹2,51,083. If death occurred at that time while full cover was in force, the estimated basic death benefit would be:
Higher of ₹5,00,000 or ₹2,51,083 = ₹5,00,000
If the policy were surrendered at the end of year 10, the estimated surrender value would be about ₹2,51,083, based on the projected fund value on that date.
What If We Stopped Paying Premiums?
For limited-premium policies, missing a premium can cause the policy to lapse. If at least three full years’ premiums have been paid, life and eligible rider cover can continue during the allowed revival period, provided the fund value is sufficient, and the policy terms are in place.
If less than three full years’ premiums have been paid, the life and rider coverages lapse. In that case, only the available fund value is payable upon death. Other applicable charges may continue until the policy is revived or terminated.
Therefore, the calculator ask for the policy status and the number of years in which full premiums have been paid. It should not automatically display full death cover for every lapsed policy.
Tax Benefits
Premium paid under the policy may have qualified for a deduction under Section 80C, subject to the conditions and limit that applied when the premium was paid. For policies issued before 1 April 2012, the premium-to-Sum-Assured condition under the tax rule is generally based on a 20% limit.
Tax treatment of maturity and surrender payments depends on whether the policy follows the applicable Section 10(10D) conditions. An eligible death benefit is generally exempt, subject to the law. Historical service tax and later tax changes can also affect records. Tax results should be checked from the policy details and applicable tax rules instead of describing every payment as tax-free.
Frequently Asked Questions
Is Policy Loan is available in LIC Profit Plus Plan 188?
No policy loan is available under Profit Plus Plan 188.
How is the current fund value calculated?
Multiply the number of units by the applicable NAV. Both figures should be taken from the relevant LIC unit statement or official record.
Is the maturity value guaranteed?
No. The maturity benefit is the fund value on the maturity date. It depends on units, NAV, investment performance, charges and policy transactions.
How is the death benefit calculated?
When full cover is in force, the basic death benefit is normally the higher of the adjusted Basic Sum Assured or fund value. Partial withdrawals, the commencement of risk for a child and policy status can change this result.
What happens when the policy is surrendered?
The surrender value is the policyholder’s fund value on the surrender date, with no separate surrender charge. It was payable only after completion of the third policy anniversary. An earlier surrender request was handled under the policy’s delayed-payment rules.
Conclusion
The LIC Profit Plus Plan 188 Maturity Calculator helps explain how premiums, units, NAV and charges affect an old Profit Plus policy. Selecting the correct UIN is essential because the Fund Management Charges and minimum premium bands differed between the versions.
For a current value, units multiplied by the applicable NAV gives the clearest estimate. Future maturity, death and surrender projections should be treated separately and should never be presented as guaranteed amounts.

Amit Kushwaha is a financial content creator and SaaS tool developer based in Lucknow, Uttar Pradesh. He has more than seven years of experience creating insurance-related content, online calculators, and practical digital tools for LIC policyholders, insurance buyers, and LIC agents.
Through LICPolicyCalculator.com, he focuses on simplifying complex LIC policy information into easy-to-understand guides and calculators. His work covers LIC premium estimates, maturity calculations, surrender value tools, policy return calculations, term insurance planning, and plan-specific calculator pages.
1 thought on “LIC Profit Plus Plan 188 Calculator Maturity, Return, Surrender Value”