LIC Money Plus Plan 180 Calculator
| Calculation Summary | |
|---|---|
| Premium Type | — |
| Annual / Single Premium | — |
| Basic Sum Assured | — |
| Allowed SA Range | — |
| Fund | — |
| Gross Return Assumption | — |
| Fund Management Charge | — |
| Estimated Charge Breakdown | |
|---|---|
| Premium Allocation Charges | — |
| Policy Administration Charges | — |
| Fund Management Charges | — |
| Mortality Charges Used | — |
| Accident Benefit Charges | — |
| CI Charges Used | — |
| Year | Premium Paid | Estimated Fund Value |
|---|
Important: This is an estimated ULIP projection. The original Money Plus Plan 180 public material does not provide the complete age-wise mortality and CI charge tables, so those charges are included only when entered manually. Actual historical NAV, taxes and transaction timing can change policy value.
Quick Overview of Money Plus Plan 180
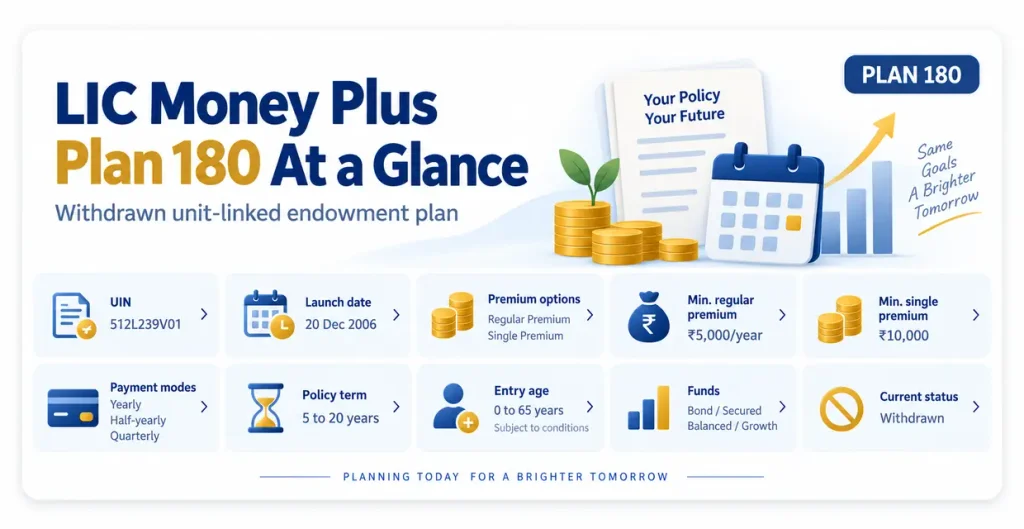
| Particular | Details |
|---|---|
| Plan | LIC Money Plus Plan 180 |
| UIN | 512L239V01 |
| Launch date | 20 December 2006 |
| Plan type | Unit-linked endowment insurance plan |
| Premium options | Regular Premium and Single Premium |
| Minimum regular premium | ₹5,000 per year |
| Minimum single premium | ₹10,000 |
| Regular payment modes | Yearly, half-yearly, and quarterly |
| Policy term | 5 to 20 years |
| Entry age | 0 to 65 years, subject to conditions |
| Investment funds | Bond, Secured, Balanced, and Growth |
| Current availability | Withdrawn |
Table of Contents
LIC Money Plus Plan 180 Calculator
LIC Money Plus Plan 180 is a unit-linked insurance plan offered by LIC India. It combined life insurance with market-linked investment. Unlike other traditional LIC plans, it did not add yearly bonuses to a fixed maturity amount. After applicable charges were deducted, part of the premium was used to purchase investment units. The value of those units changed according to the fund’s NAV.
The LIC Money Plus Plan 180 Calculator helps estimate premium allocation, policy charges, projected fund value, maturity value, and death benefit. This LIC Money Plus Plan 180 maturity calculator is mainly useful for existing policyholders because Plan 180 has been withdrawn and cannot be purchased now.
What Does the Calculator Show?
The calculator uses the entered policy details and applies the relevant Plan 180 rules. It estimate:
- Total premium paid;
- Premium allocation charge;
- Estimated amount allocated to units;
- Policy administration and fund-management charges;
- Projected fund value at maturity;
- Estimated death benefit;
- Year-wise fund growth; and
- Current fund value when the units and NAV are available.
The calculator supports Regular Premium and Single Premium policies. Regular Premium policies can have yearly, half-yearly, or quarterly payment modes. The result is an estimate, not an official LIC quotation or settlement statement.
What Is LIC Money Plus Plan 180?
LIC Money Plus Plan 180 was a unit-linked endowment plan. A part of each premium was deducted as an allocation charge, and the remaining amount was used to buy units in the selected fund. Other charges could be deducted from the policy or reflected through the fund’s NAV.
The basic process was:
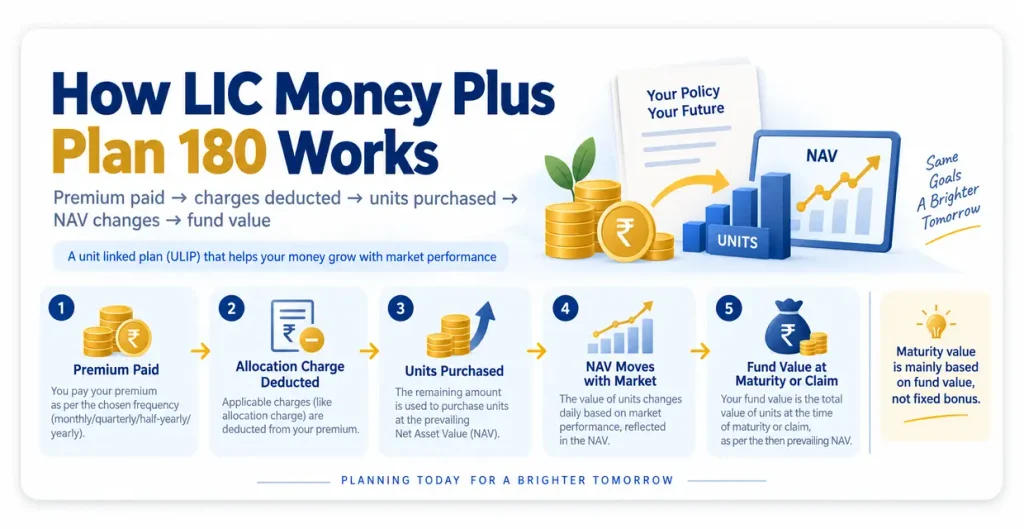
Premium paid → charges deducted → units purchased → NAV changes → fund value calculated
The plan provided insurance protection during the applicable risk period. Its maturity value was mainly based on the fund value on the maturity date, rather than on a guaranteed bonus formula.
Benefits and Features
Money Plus combined life cover with a choice of investment funds. Because the fund value was linked to market performance, it could rise or fall.
The Bond, Secured, Balanced, and Growth funds had different levels of investment risk. A conservative fund does not guarantee a positive return, and a higher-risk fund does not guarantee a higher return.
Optional Accident Benefit and Critical Illness-related benefits could apply only when selected and when a claim met the original policy conditions.
At maturity, the value of the remaining units was payable according to the policy rules. There was no fixed maturity amount that could be determined from the premium and policy term alone.
Eligibility and Policy Conditions
LIC’s official Plan 180 brochure gives an entry-age range beginning at age 0 and extending up to age 65, subject to the maturity-age limits. The minimum maturity age was 18, and the maximum maturity age was 75. The policy term could be between 5 and 20 years.
For Regular Premium policies, the minimum Basic Sum Assured generally used the higher of:
5 × annual premium or 0.5 × policy term × annual premium
For eligible age groups, the maximum Regular Premium cover could be 20 times the annual premium or 10 times the annual premium, depending on age and policy conditions.
For Single Premium policies, the minimum Basic Sum Assured was generally 1.25 times the single premium. The maximum multiple depended on the maturity age and whether the Critical Illness rider was selected. The calculator should not show a Sum Assured as valid unless the age, term, and rider conditions have been checked.
Risk Commencement for Children
When the life assured was a minor, full life risk did not always begin immediately. The risk commencement date depended on the child’s age at entry and the policy conditions. Before risk commencement, the payable amount could differ from the normal death benefit. The policy bond should therefore be checked before estimating a child’s claim.
How Does LIC Money Plus Plan 180 Work?
The policyholder first pays either a regular premium or a single premium. The applicable allocation charge is deducted before the remaining amount is used to buy units.
The units are purchased at the applicable NAV. Policy administration and mortality-related charges may then reduce the fund. The Fund Management Charge is reflected through the NAV of the selected fund.
The fund value changes according to the number of units held, NAV movements, later premium allocations, and applicable deductions. At maturity, the value of the units remaining in the policy forms the maturity benefit, subject to the policy conditions.
Charges in the Plan
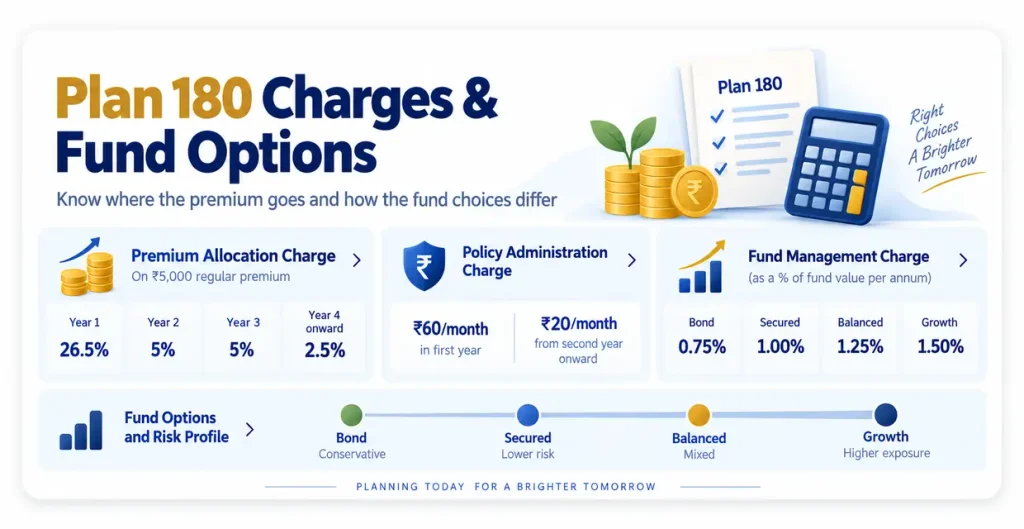
Premium Allocation Charge
The allocation charge is deducted before units are purchased.
Allocation Charge = Premium × Allocation Charge Rate
For a ₹5,000 Regular Premium, the rates used in the calculator are:
| Policy year | Allocation charge |
|---|---|
| First year | 26.50% |
| Second year | 5.00% |
| Third year | 5.00% |
| Fourth year onwards | 2.50% |
Rates can vary by premium band and may be different for Single Premium policies. The policy schedule or the calculator’s documented rate table should be checked.
Policy Administration Charge
The original Plan 180 structure used ₹60 per month during the first policy year and ₹20 per month from the second year onwards.
Fund Management Charge
| Fund | Annual Fund Management Charge |
|---|---|
| Bond Fund | 0.75% |
| Secured Fund | 1.00% |
| Balanced Fund | 1.25% |
| Growth Fund | 1.50% |
Mortality, Accident Benefit, and Critical Illness charges may also apply. They depend on the policy details and should not be filled with assumed values unless reliable records are available.
Fund Options and Risk Levels
The Bond Fund was the relatively conservative option and had a 0.75% Fund Management Charge. The Secured Fund was another lower-risk option with a 1% charge. The Balanced Fund combined different asset types and had a 1.25% charge. The Growth Fund had greater exposure to growth-oriented investments and a 1.5% charge.
These descriptions indicate relative risk only. They do not promise any particular return.
Formulas Used in LIC Money Plus Plan 180 Calculator
Net Allocated Premium
Net Allocated Premium = Premium − Premium Allocation Charge
For example, on a ₹5,000 premium with a 26.5% allocation charge:
Allocation charge = ₹5,000 × 26.5% = ₹1,325
Net allocated premium = ₹5,000 − ₹1,325 = ₹3,675
This ₹3,675 is the amount available before other applicable deductions and investment growth.
Fund Value
Fund Value = Number of Units × Applicable NAV
For future projections, the calculator estimates the effect of new allocated premiums, assumed growth, and charges over each policy period.
LIC Money Plus Plan 180 Maturity Value
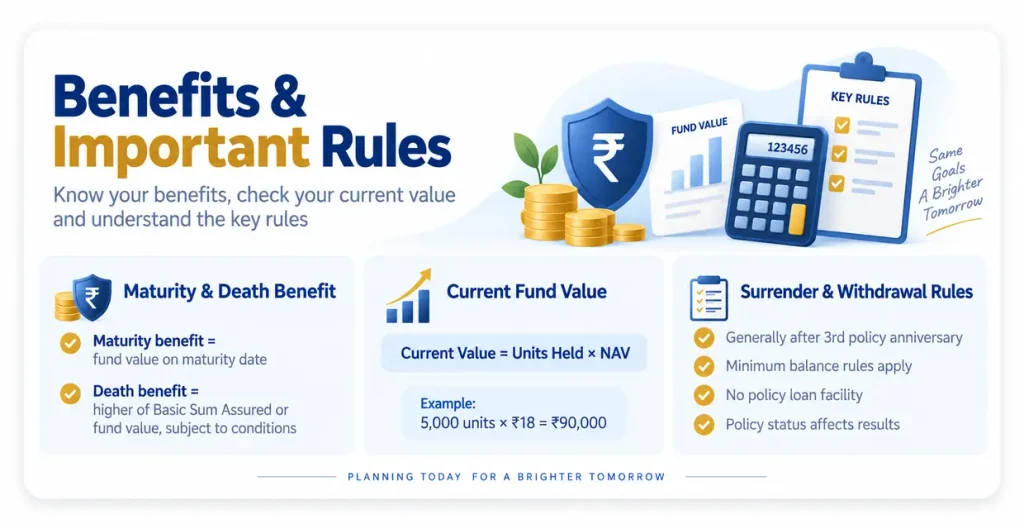
Maturity Benefit = Fund Value on the Maturity Date
This differs from a traditional LIC formula such as Sum Assured plus bonus.
Death Benefit
The basic death benefit is generally the higher of the applicable Basic Sum Assured or the fund value, subject to the original policy conditions. A LIC Money Plus Plan 180 death benefit calculator can provide only an estimate because risk commencement, policy status, and rider conditions may change the payable amount.
If an Accident Benefit rider was selected, its additional amount may be payable only when the claim qualifies. Partial withdrawals, risk commencement, policy lapse, and other provisions can affect the final amount.
How to Use LIC Money Plus Plan 180 Calculator
Select Plan 180 and enter the age at entry, premium type, premium amount, payment mode, policy term, and Basic Sum Assured. Select the fund shown in the policy records.
For a Regular Premium policy, enter the annual premium and choose yearly, half-yearly, or quarterly payment. For a Single Premium policy, enter the one-time premium amount.
Select the expected return. The 6% and 10% options are historical illustration assumptions, not guaranteed returns. A custom rate can be used only for comparison.
Add rider, charge, or unit details only when they are available from reliable policy records. Then select Calculate. Use the year-wise result to understand how the projected fund changes. Wherever possible, use the actual units and applicable NAV for the current fund-value option.
Premium Allocation Example
Assume:
- Regular Premium: ₹5,000 per year
- Payment mode: yearly
- Policy term: 5 years
- Fund: Bond Fund
- First-year allocation charge: 26.5%
Total scheduled premium:
₹5,000 × 5 = ₹25,000First-year allocation charge:
₹5,000 × 26.5% = ₹1,325Amount left from the first premium before other deductions:
₹5,000 − ₹1,325 = ₹3,675The allocation charge is 5% in the second and third years and 2.5% from the fourth year onwards under the stated calculator table. Administration, fund-management, mortality, and other applicable charges must then be considered.
The final projected fund value depends on the timing of premium payments, assumed growth, and charge treatment. It should not be described as a guaranteed maturity amount.
Current Fund Value of an Old Policy
For an existing policy, the LIC Money Plus Plan 180 fund value calculator can provide a basic estimate. However, the actual current fund value is better obtained from the policy statement than from a future projection.
Current Fund Value = Units Held × Applicable NAV
For example:
5,000 units × ₹18 NAV = ₹90,000The actual amount may still be affected by policy status, deductions, or outstanding adjustments. LIC’s policy statement remains the reliable source.
Surrender and Partial Withdrawal
Surrender and partial withdrawal are subject to the original policy conditions. Under the available Plan 180 conditions, surrender and partial withdrawal are generally available after completion of the third policy anniversary. The payable amount is linked to the fund value and may differ from a maturity projection.
For a Regular Premium policy, the fund should generally retain at least two times the annualised premium after a partial withdrawal. For a Single Premium policy, the minimum fund balance is generally ₹5,000. A minor may make a partial withdrawal only after the applicable policy anniversary on or after attaining age 18.
Partial withdrawals reduce the available fund and can affect the Sum Assured for the applicable period. The minimum balance, policy-anniversary requirement, and withdrawal rules should be checked before using an estimate.
If premiums were stopped, the original insurance cover may not continue in the same way. A lapsed or discontinued policy can have different rules from an in-force policy. The policy status and LIC records must be checked before estimating surrender or death benefits.
Plan 180 does not provide a policy loan facility. Surrender, partial withdrawal, and current fund value should not be confused with a loan amount.
Tax Rules and Important Caution
Tax treatment depends on the policy issue date, premium, Sum Assured, policy conditions, and the law applicable when the premium was paid or the benefit was received. Tax, rider charges, and other deductions should not be treated as investment returns.
The calculator estimates policy values; it does not decide whether a deduction or exemption is available. The latest tax rules and policy documents should be checked before making a tax claim.
Important Points to Remember
LIC Money Plus Plan 180 is withdrawn and cannot be purchased as a new policy. It was market-linked, so the 6% and 10% illustration rates are not guaranteed returns.
The actual value depends on the units, NAV, selected fund, premium history, allocation charges, administration charges, mortality charges, riders, withdrawals, and policy status. Complete age-wise mortality and Critical Illness charge tables should not be invented when reliable records are unavailable.
Also Check:
Frequently Asked Questions
Is LIC Money Plus Plan 180 still available?
No. Plan 180 is a withdrawn plan and is no longer available for new purchases. The calculator is intended mainly for existing policyholders.
How is the LIC Money Plus Plan 180 maturity value calculated?
The LIC Money Plus Plan 180 maturity calculator estimates the maturity value mainly from the fund value on the maturity date. It depends on the units held and the applicable NAV after relevant deductions.
What is the death benefit under Plan 180?
The basic death benefit is generally the higher of the applicable Basic Sum Assured or the fund value, subject to risk commencement, policy status, withdrawals, and other policy conditions.
Are the 6% and 10% returns guaranteed?
No. They are illustration assumptions used to show possible outcomes. Actual returns depend on fund performance and NAV movements.
How can the current value of an old policy be checked?
Multiply the number of units by the applicable NAV for an estimate. The official LIC policy statement should be used when an exact current value is required.
Conclusion
LIC Money Plus Plan 180 differed from a traditional LIC policy because its value depended on market-linked units rather than fixed bonuses. Premium allocation, policy charges, fund choice, NAV movement, and policy status all affect the result.
The LIC Money Plus Plan 180 Calculator provides a practical estimate of these values. For an old policy, the most reliable calculation uses the actual units, NAV, and policy records. All future projections should be treated as estimates, not guaranteed LIC benefits.
1 thought on “LIC Money Plus Plan 180 Calculator: Calculate Fund Value, Maturity”